
You sit at the kitchen table, staring at the denial letter or the unexpectedly high loan quote, wondering how a three-digit number got so much power over your life.
It is easy to feel like the entire system is rigged against you, built on rules nobody ever bothered to explain in plain language.
The good news is that most of what people think they know about credit scores is completely wrong, and fixing your understanding costs nothing.
Quick Tips Before You Start
Pull Your Report
Get your official reports free once a year at AnnualCreditReport.com.
Keep Old Cards Open
Closing your oldest active card shortens your credit history overnight.
Check Payment Dates
Align your bill due dates with the days your paycheck actually clears.
Ignore Credit Karma Scores
Lenders usually pull FICO scores, not the VantageScore apps show you.
1. Carrying a Balance Helps Your Score
Pay your statement balance in full every single month without exception.
The old wives tale that leaving a small balance builds credit faster is a myth invented by lenders who want to collect your interest payments.
Interest does not help your score; it only drains your cash flow by charging you an average APR of around 20% on whatever you leave behind.
Aim for zero reported balance on your statement date while using the card for everyday purchases.
Set up an auto-pay rule in your banking app today to clear the full remaining balance three days before the due date so you never pay a dime in fees.
💡 Tip: Set up auto-pay for the full statement balance so you never pay a dime of interest.
⚠️ COMMON MISTAKE
The Interest Trap
Carrying a $1,000 balance at a 21% APR just to prove you use credit costs you over $200 a year for zero scoring benefit.
2. Checking Your Own Report Lowers It
Does checking your own credit report actually lower your score?
It feels a bit like poking a sleeping bear, which is why so many people avoid looking at their reports for years out of sheer dread.
I avoided mine for almost eighteen months after a medical bill went to collections because I was genuinely terrified the score would drop just for glancing at it.
when you pull your own credit report, it counts as a soft inquiry, and soft inquiries do not affect your score by a single point.
Hard inquiries only happen when a lender checks your credit because you actively applied for a loan, a mortgage, or a new credit card.
Those hard pulls can ding your score by a few points temporarily while soft pulls leave your history entirely untouched.
Looking at your own numbers is free, completely safe, and the only reliable way to catch reporting errors or identity theft before they quietly cost you thousands in higher interest rates.
This week: pull one of your reports online through the official government-mandated site and just look at the open accounts to make sure you recognize every single one.
3. Closing Old Credit Cards Is Good
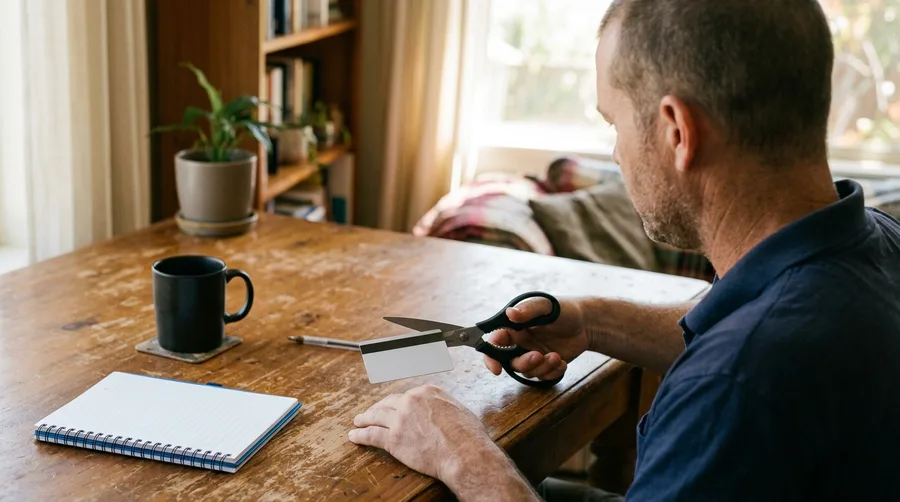
There is a deep satisfaction in snipping an old piece of plastic with kitchen shears and tossing it into the trash.
It feels like you are tidying up your financial life, but the scoring algorithm actually punishes you for doing it.
When you close an older account, you instantly shrink your total available credit limit and shorten your average account age, which can drop your score by thirty to fifty points overnight.
Instead of canceling them, we use a simple two-bucket mental model: active cards for daily spending, and history cards tucked away in a drawer just to keep your credit foundation wide.
Keep those older cards alive by assigning a single small subscription, like a $4 streaming service, on auto-pay each month, then set up a full statement balance payment so you never pay a dime of interest.
Old Card Strategy
4. Checking Rates Hurts Your Score
It is completely normal to freeze up at the idea of a hard inquiry dinging your report when you are just trying to find a decent loan.
People assume every single rate check acts like a brand-new application that damages your standing, which is how older scoring models used to operate. Modern scoring systems now give you a shopping window of 14 to 45 days where multiple hard pulls for the same loan type group together to count as a single inquiry.
Compare rates aggressively within that window instead of taking the first offer thrown your way.
Your credit score is not a measure of your moral worth or your income. It is simply a risk index for banks.
— What loan officers understand that borrowers miss
5. Income Directly Affects Your Score
Zero dollars of your $45,000 or $120,000 salary shows up on your credit report.
People often assume a higher paycheck automatically makes you more creditworthy to lenders, but scoring models look strictly at debt management and repayment history rather than earnings. Your income matters for qualifying for a mortgage or a car loan because banks want to see if your cash flow can cover the payments, but it has zero direct impact on your actual three-digit credit score.
When your debt-to-income ratio keeps getting rejected by housing applications, stop guessing and talk to a nonprofit credit counselor or a fee-only fiduciary to look at your actual numbers.
📈 Your 90-Day Credit Clean-Up Roadmap
Month 1
Pull all three credit reports and highlight any incorrect late payments or unknown accounts.
Month 2
Submit online dispute forms directly to Equifax, Experian, and TransUnion.
Month 3
Set up auto-pay for all statement balances and lower your credit utilization below 10 percent.
6. Annual Credit Report Review Routine
For three straight years, I never looked at my credit reports because the idea of finding an error felt terrifying.
Spread the task across the year by checking one of the three major bureaus every four months instead of pulling all of them at once.
Scan specifically for unfamiliar addresses, incorrect balances, or unauthorized accounts that could be silently dragging down your score.
Set a calendar reminder for your next review date right now.
Interest Cost of a 50-Point Score Drop
7. The Twenty Five Dollar Floor
Even $25 extra paid toward a high-interest card each month cuts down your total interest burden over time.
People often freeze up because they cannot afford to throw $500 extra at a credit card, so they figure why bother. That all-or-nothing trap keeps balances stuck for years. The mechanism is simple: every extra dollar reduces the principal balance that daily interest calculates against, saving you real money over the life of the debt.
Start with this floor and let consistency do the heavy lifting instead of waiting for a windfall. Log into your app today and set up that single recurring transfer.
8. Paying Off Debt Lowers Scores
You finally make that last lump sum payment on an old personal loan, watch the balance hit zero, and feel a wave of genuine relief that the debt is finally gone for good.
Then you check your credit monitoring app a week later and see your score dropped by two points, sending a quiet panic through your chest because you thought paying things off was supposed to make the number go up every single time.
credit scoring models like to see an active mix of open installment loans and revolving accounts, and closing that paid-off account slightly reduces your overall credit diversity.
The trade-off is completely real because you lose a microscopic bit of scoring formula points, but you instantly gain an extra $245 in monthly cash flow that was previously swallowed up by principal and interest.
Do it anyway and ignore the temporary blip, because having actual money sitting in your checking account to buy groceries matters infinitely more than guarding a stagnant, overly sensitive credit score.
Credit Impact Severity Scale
How different events affect your FICO score
- High Utilization (80%): Massive temporary penalty to your score.
- 30-Day Late Payment: Severe drop that lingers for years.
- Hard Inquiry: Minor drop that fades in months.
9. You Are Just Bad With Money
I spent three years convinced that my terrible credit score meant I was simply fundamentally broken at adulting.
You have probably told yourself the exact same thing when staring down a low number or a declined card.
Most of us learned personal finance through trial and error, usually starting with expensive mistakes in our twenties.
The financial industry actually benefits when you feel this kind of deep personal shame because shame keeps people from asking basic questions or disputing errors.
What I believe now is that credit is a mechanical tool like a table saw: dangerous if you stick your hand in the blade, incredibly useful when you respect how it works.
New belief: my score is a lagging indicator of my automated systems, not a report card on my character.
This shift changes everything about how you open mail, look at statements, and plan your next financial move.
This week: pick one old collection account or error you have been avoiding and spend 15 minutes looking at it without judgment.
10. Waiting Until Later to Fix It
Is it really that bad to wait until next month to look at my credit report?
Waiting until the week before you apply for an apartment or a mortgage is a guaranteed way to overpay thousands of dollars in lifetime interest.
The mechanism here is bureaucratic lag, because fixing credit errors or waiting for a disputed collection to drop off takes anywhere from 30 to 90 days as bureaus investigate disputes.
I put off looking at my own report for two years after college because I was terrified of what I would see, and it cost me an extra $45 a month on a car loan rate just because I rushed the process.
Start six months before any major life milestone so you actually have time to fix the damage before a lender sees it.
11. Automate Every Single Minimum Payment
You have stared at the calendar in a cold panic more times than you care to admit.
Missing a payment by just thirty days can slash your credit score by up to 80 points overnight, completely wiping out years of careful discipline over a simple forgotten envelope.
Life gets loud, bills get buried in the pile, and relying on your memory or willpower each month is a trap.
The mechanical truth is simple: banks report late payments to bureaus the exact second they cross the threshold.
Automating your minimum payments removes human error entirely from the equation.
Setting it up takes about ten minutes across your banking apps.
Once it is running, your payment clears before you even see the cash in your checking account, protecting your baseline score without requiring a single ounce of ongoing mental energy.
Do this for every single open account today and let your phone remember the dates so you do not have to.
12. You Must Fix Every Single Thing Today
Within 30 minutes, you can burn out trying to overhaul every single detail of your credit profile at once.
Fixing everything in one afternoon is a fast track to abandoning the effort entirely because the mental fatigue becomes too heavy to carry.
Pick one single task for this week, like setting up a single calendar alert to check your report, and leave the rest for later.
Frequently Asked Questions
How long do late payments stay on your credit report?
Late payments and most negative marks typically remain on your credit report for seven years, though their impact on your score fades significantly over time if your recent payment history is spotless.
Should I pay off debt or save for emergencies first?
Build a starter emergency fund of $500 to $1,000 first so unexpected car repairs do not force you back into credit card debt, then attack high-interest debt aggressively.
Does checking my own credit score hurt it?
No. Pulling your own credit report or using free monitoring apps results in a soft inquiry, which has zero impact on your actual credit score.
Is it okay to pause retirement contributions to pay off debt?
If your employer offers a retirement match, keep contributing enough to get the full match because that is an immediate 100 percent return on your money.
Start With This One
Take a deep breath and remember that your credit score is simply a number that changes as soon as your habits do.
Pick just one item from this list to tackle this week, and let the rest wait until next payday.
