
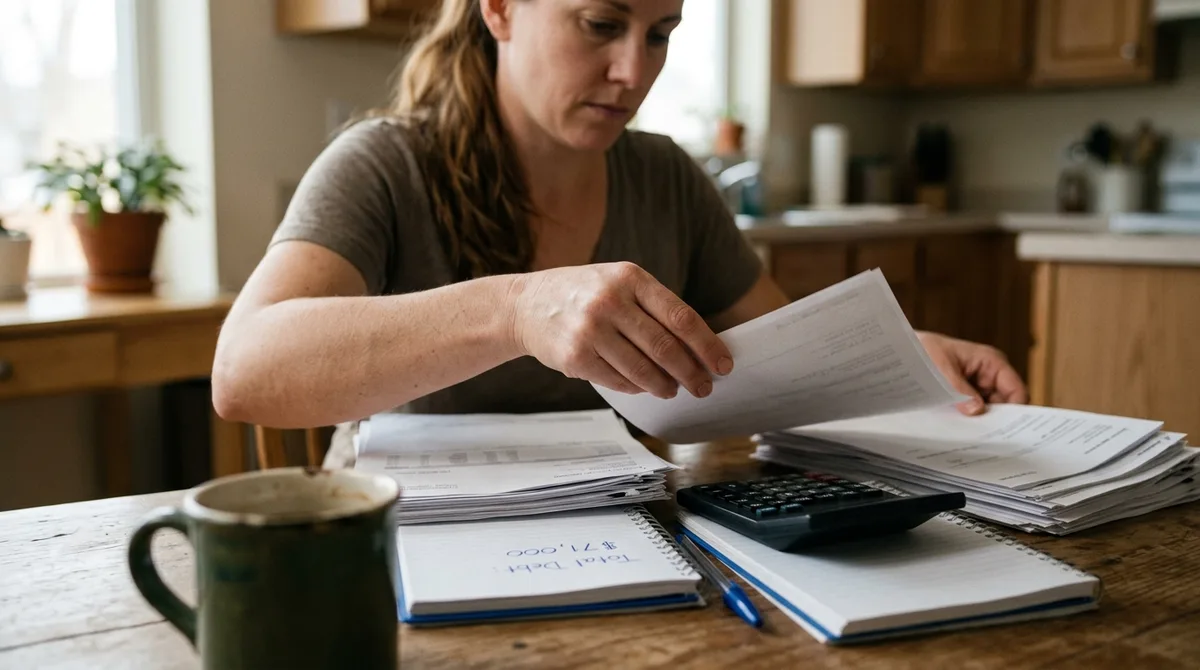
The statement sits on the kitchen counter, folded into a square, and you have not opened it since Tuesday because you already know what the balance says.
You feel like everyone else has a secret manual for money while you are just trying to make sure the debit card does not decline at the grocery store.
It is fixable, and you do not need a six-figure salary or an inheritance to start clearing the numbers that keep you awake at night.
When I stared down my own pile of student loans and credit cards on a modest income, I thought the only way out was panic.
Here is the exact order to tackle your debt, what to ignore, and how to keep breathing while you do it.
Quick Tips Before You Start
Stop Using Cards
Freeze plastic in a container of water so you cannot impulse spend.
Call Lenders
Ask every credit card company for a temporary interest rate reduction.
Track One Month
Write down every single dollar spent for thirty days without judging it.
1. Run the Numbers With a Fiduciary
You might feel like you should be able to figure this entire mess out on your own without paying a dime to anyone else.
Pride makes us want to fix our own financial wreckage behind closed doors, but tangled debt is genuinely hard to untangle alone.
The math gets tangled fast when student loans, personal lines of credit, and old car notes overlap with fluctuating monthly income.
Sometimes you need an objective third party to look at the board without judgment and help you map out a realistic sequence.
Book a single session with a fee-only fiduciary who charges by the hour rather than taking a percentage of assets you do not have yet.
Expect to spend roughly $150 to $300 for that one-time baseline review, and treat it as a targeted repair cost rather than an ongoing expense.
At a Glance
2. Scale Back Without Quitting
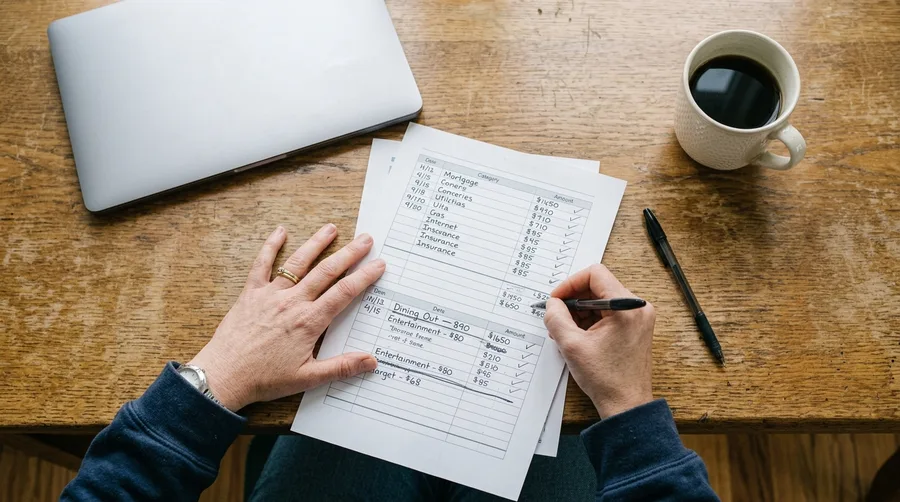
Is it actually possible to slash every discretionary expense down to zero right this second without completely burning out?
No, and trying to do so almost always backfires by triggering a massive spending binge two weeks later when the emotional friction gets too high. Cut your restaurant spending and subscription services by half instead of eliminating them cold turkey. Trimming a $200 monthly habit down to $100 keeps your sanity intact while still freeing up real cash flow.
Give yourself permission to move slowly this month, pick just two subscriptions to cancel today, and leave the rest for the next paycheck.
💡 PRO TIP
The Sustainable Cutback Rule
Cut subscriptions you have not used in sixty days first. Keep one small luxury so you do not feel deprived.
3. Overcome the Scarcity Mindset
Over 60 percent of adults worry constantly about unexpected bills, according to Federal Reserve data.
You have convinced yourself that being bad with money is a permanent personality trait rather than a set of habits you can unlearn over time.
That narrative in your head is costing you more than the actual interest rates ever will.
The mechanism here is entirely behavioral, because panic causes avoidance and avoidance lets small balances turn into crises.
Shift your internal monologue from panic to strategy right now.
Look at the ledger as a game board instead of a report card on your moral worth as a human being.
Every single dollar you redirect toward a balance is proof that you are taking your agency back from creditors.
New belief: My past mistakes describe my history, not my capacity to change the outcome.
Start with a single $25 extra payment this Friday.
The ledger is a game board, not a report card on your moral worth.
— What changes the math permanently
4. Avoid the Minimum Payment Trap
Round every single credit card payment up by at least fifty dollars starting today.
The trap is how the statement math is built. When you pay only the minimum, most of that check vanishes into interest instead of shrinking the principal balance, keeping you locked in a debt cycle that can stretch for decades. You are not irresponsible for missing this; banks deliberately design those statements to make the minimum look like safety.
Log into your portal right now and change that automated payment. That extra fifty dollars chips straight at the principal itself, turning a twenty-year sentence into a much shorter climb.
5. Attack High-Interest Balances First
When I realized my credit card was charging 22 percent interest, my stomach dropped.
That rate means nearly a quarter of every payment vanishes into thin air without touching the actual principal balance you owe.
The mechanism is punishing because high annual percentage rates compound daily, inflating the debt faster than ordinary savings can ever outpace.
Target that highest APR card aggressively right now while paying bare minimums on every other open balance.
Put an extra $200 toward that specific balance every single payday to start breaking the cycle.
The trade-off requires freezing plastic spending entirely until that single liability reaches zero.
High-Interest Debt — At a Glance
💳 Average APR
20% – 22%
🎯 Target
Highest rate first
⚡ Action
Round up payments
6. Accept the Trade-Offs
It is completely normal to feel a sudden wave of frustration when you realize how many weekend dinners, takeout nights, or small comforts you have to skip to free up an extra $300 a month for debt.
The honest cost of paying down balances aggressively is a quieter, tighter routine for twelve to eighteen months while you catch up. You are trading short-term convenience for the immense psychological relief of watching your overall debt shrink by thousands of dollars instead of treading water.
Pick one recurring non-essential expense to cancel by Friday.
7. Rebuilding My Own Balance Sheet
Facing your financial reality directly is the only reliable way to stop debt from silently haunting you at night and draining your daily mental energy.
I spent three full years completely ignoring a $12,000 car loan because opening the online payment portal gave me a genuine physical ache in my chest. Avoiding the balance felt like self-preservation at the time, but it just let the interest compound quietly in the background while I pretended ignorance was a valid strategy.
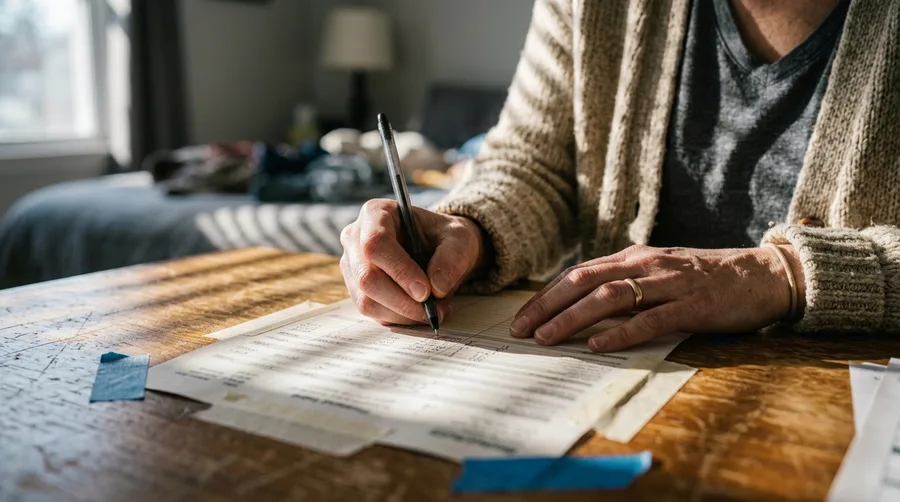
The turning point finally arrived when I printed out every single loan statement and taped them right to the inside of my bedroom closet door.
Seeing those numbers in plain daylight stripped away their paralyzing, mysterious power over my mood. Once I knew the exact enemy I was fighting, I started throwing an extra $400 a month at it by rigorously meal prepping on Sundays and canceling a storage unit I never visited.
It was tedious, unglamorous work, but watching that intimidating balance drop by a thousand dollars every eight weeks completely changed how I felt when I walked into a grocery store.
The Debt Payoff Timeline
8. Start With Twenty-Five Dollars
You might believe that saving or paying down debt only truly counts if you can throw massive sums at it every single payday.
That damaging myth keeps millions of people paralyzed on the sidelines doing nothing month after month, waiting for a mythical windfall or a raise that always seems just out of reach. It convinces you that if you cannot save two hundred dollars right now, doing twenty dollars is somehow pointless.
Even $25 a month, moved automatically into a dedicated payoff or savings account, does infinitely more than the $0 a month you keep meaning to transfer while waiting for the right moment. Consistency beats grand gestures every single time because it builds a behavioral baseline that survives tight months.
When you start small, your brain builds the muscle memory of paying yourself first without triggering financial claustrophobia or a sense of deprivation that ruins your week.
I spent years waiting until I had an extra five hundred dollars lying around to start getting serious, and every single month that hypothetical money simply vanished into groceries, gas, and unexpected utility bills. The moment I dropped the threshold to a tiny amount, the paralysis finally broke and the account actually started growing for the first time in my life.
Scale the number up by $10 every quarter as your comfort level expands and your cash flow settles into a predictable rhythm, turning a micro-habit into a real financial cushion over the course of a single year.
This week, log into your banking app and set up a recurring automatic transfer for whatever small amount you can genuinely spare without panic.
Twenty-five dollars today beats zero dollars forever.
🌱 GROWING TIP
The Micro-Transfer Method
Automate a tiny $25 transfer every Friday. You will not notice it missing from checking, but it adds up to $1,300 a year.
9. Build a Simple Three-Bucket System
Opening a banking app to categorize twenty different transactions makes you feel like you are failing an accounting test you never studied for.
You do not need a complicated budgeting software or a twenty-tab spreadsheet to fix your cash flow, but you do need hard physical boundaries.
Split your take-home pay into three distinct buckets the exact morning your paycheck lands: fixed bills, debt minimums, and flexible spending. Keep your rent and utility money in a completely separate checking account at a completely different bank so you never accidentally spend your electric bill on weekend plans or takeout.
I spent years trying to manually track every dollar until I finally realized that relying on pure daily discipline is a losing strategy.
Open one secondary account this week, calculate your exact monthly baseline for fixed housing and utility obligations, and route that precise amount there automatically every pay cycle before you touch anything else.
10. Automate the Transfers Immediately
Four days is usually how long willpower lasts before a $60 takeout order feels completely reasonable.
Willpower is a finite resource that runs out long before Friday evening, which is why relying on it to save money is a losing battle. The mechanism behind automation is simple: it removes the choice entirely by moving the funds before your brain has a chance to negotiate. I used to transfer money manually every single month and inevitably skipped it whenever things got tight. Setting up auto-pay for the exact morning your paycheck lands changes the timing so the savings happen before the spending ever begins.
Log into your banking app today and schedule a recurring transfer for the next payday.
11. Strike While Momentum Is High
Starting this month matters more than waiting for a raise or a bonus next year.
Compounding interest punishes delay ruthlessly because every month you sit on the sidelines costs you real unearned progress. If you put $300 a month into a standard growth fund earning roughly 7% a year, waiting just twelve months to start means giving up nearly $4,000 in total value over a decade. Time does the heaviest lifting in personal finance, and no amount of hustle later on makes up for lost years.
I waited six months to move my savings over a mild fear of paperwork, and that hesitation literally cost me a few hundred dollars in free growth while I dithered.
Open the account today.
12. Check In Once a Month
Pull up your accounts for twenty minutes on the first Sunday of the month, and not a minute longer.
Staring at every single past receipt makes people quit, so strip the process down and look at two numbers only: your total cash cushion and your total remaining debt balance. This keeps you from drowning in details while still letting you see if the needle is actually moving in the right direction.
Write those two figures down in a simple notebook, close the tab, and walk away. This month, set a recurring calendar reminder for twenty minutes and just do those two checks.
13. Use Cash Envelopes for Groceries
I stood at the register with a cart full of pantry staples when my debit card declined for a $142 total, and walking those groceries back to the shelves was the longest walk of my life.
Physical cash slows down spending because handing over paper bills triggers actual psychological pain that tapping a plastic card simply never matches.
Withdraw $120 in paper bills specifically for your weekly food run this Friday, leave the plastic at home, and watch how quickly you start putting back the things you do not really need.
The Cash Envelope Transformation
14. Automate Your Savings Growth
How do you manage to save more money each month when you already feel like every single dollar from your paycheck is completely accounted for before it even hits your account?
You stop trying to remember to do it.
When you rely on daily willpower at the end of a long, exhausting month, your savings account loses every single time because life always finds a practical way to absorb whatever cash is left sitting in your checking account.
You fix this systemic problem by taking your brain entirely out of the equation through automated banking rules that do the heavy lifting while you sleep, letting your money grow quietly in the background without requiring daily supervision or emotional strain.
Log into your banking app right now and set a recurring transfer for the exact morning after payday, then use the escalation feature to automatically increase that transfer by one percent every six months.
Because that percentage bump is so tiny and happens automatically behind the scenes, you will naturally adapt to the slight adjustment in your take-home pay without ever feeling pinched or deprived during your grocery trips.
This is exactly how ordinary earners with completely normal salaries manage to build substantial financial cushions over time, letting compounding interest slowly accumulate while you simply live your life and focus on other goals.
Keep your login credentials secure, check the account balance only twice a year, and let the system work.
15. Embrace the Worthwhile Trade-Offs
Every financial choice involves giving up something else.
Eating at home means passing on restaurant meals.
That trade-off buys your freedom back.
Frequently Asked Questions
Is it too late to start investing or paying off debt at 40?
It is never too late to take control of your numbers. Starting at 40 gives you decades of earning power left to shift your trajectory, provided you focus on consistency rather than perfection.
Should I pay off debt or save for emergencies first?
Build a small starter fund of $500 to cover immediate surprises so you do not add new debt, then attack high-interest balances aggressively while maintaining your minimums.
Is it okay to pause my retirement contributions while paying off debt?
If your employer offers a retirement match, keep contributing enough to capture it because that is an immediate 100 percent return. Otherwise, you can temporarily redirect extra cash toward high-interest debt.
How much should I save after having a baby on a tight budget?
Aim for a modest one-month buffer of bare expenses first. For many households, that sits between $2,000 and $3,500. Get there gradually without shaming yourself for slow progress.
What if my income is genuinely too low to budget out of debt?
A budget cannot fix an income that is too low to cover basic survival costs. Acknowledge that reality, look into local assistance programs, and focus on increasing earning power alongside cutting costs.
Make It Stick
You do not have to overhaul your entire financial life by Friday afternoon.
Pick one move from this list, set up the automation, and let consistency do the work while you get back to living your actual life.
