
You take out a consolidation loan to finally breathe a little easier after months of juggling high-interest balances.
It feels like a clean slate, dropping four separate credit card bills down to a single monthly draft that seems more manageable on paper.
Except the cards you just paid off are sitting in your wallet with zero balances, and the underlying spending habits that got you here haven't actually changed.
Before you assume the new loan solved your money stress, let's look at the quiet warning signs that consolidation might be digging you deeper.
Quick Tips Before You Start
Pull Real Balances
Print every current statement before comparing loan offers.
Freeze the Cards
Put consolidated credit cards in a drawer instead of carrying them.
Check Total Interest
Look at lifetime loan costs rather than just the monthly payment.
Audit Payday Dates
Align your new loan auto-pay with the day after your paycheck lands.
1. The Empty Cards Fill Back Up Within Six Months
Review your credit card statements on the first of every single month to see if empty plastic is quietly creeping back into your wallet.
Consolidation only moves debt from one ledger to another; it never fixes the underlying cash flow gap that created the balance in the first place. When you clear four separate cards at once, your available credit jumps instantly, creating a dangerous psychological illusion of newfound wealth that tricks your brain into feeling richer than you actually are.
I watched a close friend fall into this exact trap, feeling a profound sense of relief right before charging groceries and gas back onto the newly emptied cards out of sheer habit.
If you charged everyday essentials to those accounts within six months, the loan didn't solve anything at all. It simply layered a brand-new fixed payment right on top of your regenerated revolving debt, leaving you in a much worse financial position.
Open your banking app and check now.
Consolidation Jargon Decoded
2. Your Overall Interest Costs Quietly Went Up
A lower monthly payment often hides a much higher total cost over the life of the loan.
Extending a 24-month payoff out to 60 months dramatically increases the total interest you pay, even if your interest rate dropped by a few percentage points. Lenders make money by keeping you in debt longer.
It is entirely okay if you need to pause and rethink this right now, especially if the math turned out worse than you hoped. Take twenty minutes this week to pull the original amortization schedule and look at the actual sum you agreed to repay.
⚠️ COMMON MISTAKE
The Extended Term Trap
Never judge a consolidation loan by the monthly payment alone. Look at the total payout box on the Truth in Lending disclosure.
3. Origination Fees Ate Your Emergency Cushion
You stare at the loan approval screen feeling like you finally beat the system, convinced the hard part of fixing your debt is officially behind you.
I borrowed $15,000 to clear out three store cards and a personal line, assuming the math was straightforward and clean.
What I missed in the fine print was a 5% origination fee that was silently subtracted right off the top before the funds ever hit my creditors.
That meant $750 vanished instantly, leaving my old accounts slightly short and forcing me to scramble to cover the remaining balances out of pocket.
The mechanism here is a quiet trap: lenders deduct upfront fees directly from your total payout while keeping your borrowed principal at full price, which means you are paying monthly interest on money you never actually received in your hands.
I had to dip into my already fragile emergency savings to clear those remaining fractions, leaving myself completely unprotected for the rest of that year.
The trade-off is brutal because you trade immediate relief for a depleted cash cushion that cannot survive even a minor unexpected car repair or medical bill.
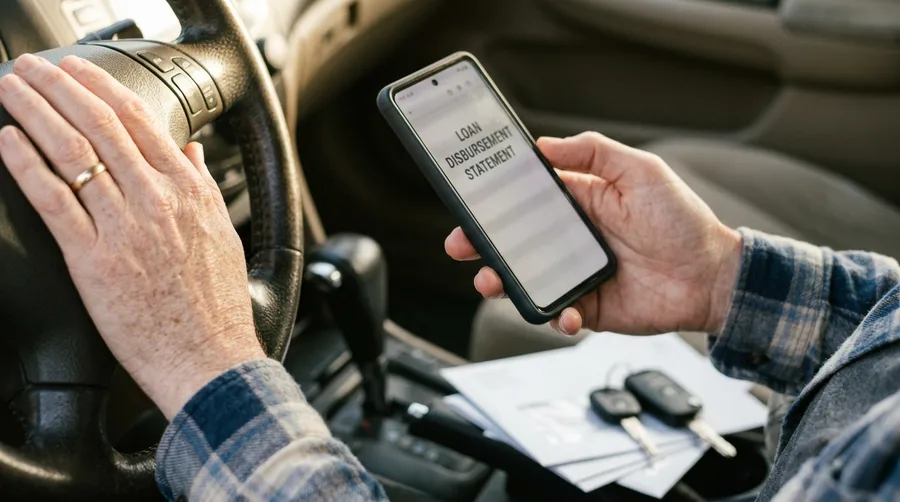
This week: check your original loan disbursement statement to see if fees were deducted from your total.
Origination Fees — The Fine Print Details
📋 Typical Fee Range
1% to 8% of total
✂️ Interest Impact
Charged on unreceived funds
💸 Savings Buffer Needed
At least 1 month of fees
⚠️ Skip This If
Deduction drains your last cash
The Math Check
Always calculate your net payout before telling old creditors your accounts are closed.
4. You Started Small With Just $50 a Month
People assume that if you cannot save hundreds of dollars right after a debt consolidation loan, you might as well not bother saving at all.
That is completely backwards, because even $25 a month, moved automatically straight to a separate account on payday, does more real work than $0 you keep meaning to set aside when things settle down.
Starting tiny is entirely valid when your income feels tight and your new loan payment left you with zero breathing room. Consistency beats perfection every single time, so open a separate account and set a tiny $25 or $50 automatic transfer today.
5. You Ignored the Root Cause of Your Debt
It is completely normal to look at a consolidated loan approval and feel like you have finally crossed the finish line.
Many people treat consolidation as a permanent cure rather than a temporary restructuring tool. If your monthly expenses consistently exceed your take-home pay by even $150 or $200, a lower interest rate only buys you a few months of runway before the exact same shortfall quietly returns.
I made this exact mistake years ago when I first consolidated my balances, breathing a massive sigh of relief while keeping my daily spending habits entirely intact.
The real fix requires tracking where your money goes every single pay period instead of hoping the loan math takes care of lifestyle creep. You are not doing this to feel bad about past purchases; you are doing it so next month's bills are a conscious choice rather than a surprise.
Face that underlying deficit head-on by listing your actual fixed expenses over the last ninety days.
Consolidation Red Flags
6. Your Debt-to-Income Ratio Barely Moved
Forty-three percent is the threshold where most lenders draw a hard line on your debt-to-income ratio, signaling whether a consolidation loan is actually sustainable over a three-to-five-year term.
Total household debt in the United States sits around $18 trillion, and revolving balances continue to strain family budgets across every income bracket without slowing down.
When you consolidate, lenders look closely at this exact ratio to decide if you can carry the new payment structure without buckling under pressure.
If your ratio remains stuck above that crucial boundary, a single consolidation loan will not protect you from a future income shock or an unexpected job disruption.
According to Federal Reserve consumer credit data, unsecured debt burdens often require structural income changes alongside refinancing rather than a simple paperwork shuffle.
This metric matters far more than your credit score alone because it measures your actual cash flow rather than just your history of borrowing.
Run your own numbers against your current net pay before signing any long-term agreement that locks you into a fixed obligation.
When personal finance decisions get complex or involve heavy trade-offs, consult a fee-only fiduciary or a nonprofit credit counsellor who looks at your whole picture.
Debt Reality Checks
7. You Feel Trapped by the New Fixed Payment
I remember staring at my bank app after my first fixed loan payment hit, realizing I had locked myself into a $650 monthly anchor that didn't care if my freelance clients paid late or if my car needed a new alternator.
Sound familiar? You traded variable credit card minimums that you could flex down in a lean month for a rigid fixed loan payment.
Scarcity mindset tells you that locking everything into one massive monthly obligation is the only way forward.
The reframe: flexibility in your cash flow matters just as much as chasing a lower interest rate, because rigidity breaks when life happens.
What I believe now is that a rigid payment can break your budget faster than a flexible one if your income fluctuates.
Take fifteen minutes this week to map out your lowest earning month, not your average one, to see if your current payment leaves any breathing room at all.
💡 PRO TIP
Build Flexibility First
Keep a small cash buffer in a separate account before locking yourself into rigid fixed debt payments.
8. Manual Payments Keep Failing Your Routine
Did you set up your new loan payment for the last day of the month instead of payday morning?
End-of-month payments rely on whatever cash survives, and what survives is usually zero. When you schedule the transfer for the exact morning your paycheck lands, you take willpower completely out of the equation.
Take four minutes in your banking app right now and shift that $450 automatic payment to hit on the first. Do it today and stop letting bad timing wreck your routine.
9. You Borrowed More Than Your Original Balances
Lenders sometimes dangle a little extra cash on top of your consolidation total as discretionary funds for home repairs or a holiday.
That extra money feels like a helpful cushion, but it actually turns a debt cleanup tool into a brand new spending spree disguised as financial help.
The mechanism is simple math working against you, because every extra dollar borrowed increases your monthly obligation and extends your timeline unnecessarily.
Keep your loan amount strictly tied to the specific balances you set out to eliminate without taking on a single cent of bonus padding.
For example, if your lender offers $20,000 when your actual debt total sits at $17,000, borrow exactly $17,000 and reject the buffer completely.
Frequently Asked Questions
Is it ever a good idea to consolidate high-interest debt?
Yes, if your new interest rate is significantly lower, you don't extend your repayment timeline excessively, and you close or freeze the underlying credit cards so you don't run them back up.
Will a consolidation loan hurt my credit score?
It causes a temporary dip due to the hard credit inquiry and a new account opening. However, if it lowers your credit utilization ratio and you make consistent on-time payments, your score typically recovers and improves over time.
Should I pay off debt or build an emergency fund first?
Aim for a small starter cushion of $500 to $1,000 first so minor emergencies don't immediately force you back onto credit cards. Once that baseline exists, attack high-interest debt aggressively.
What happens if I miss a payment on my consolidation loan?
Missing a fixed loan payment triggers late fees and can severely damage your credit score much faster than revolving minimums because lenders report missed fixed installments immediately.
How can I avoid running my credit cards back up after consolidating?
Remove the card numbers from all online shopping profiles, freeze the physical cards in a block of ice or a drawer, and shift your flexible spending to a debit card or weekly cash envelope.
Your Next Step
You do not have to fix your entire financial history by Friday afternoon.
Pick one move from this list—whether that's freezing your cards, checking your total interest payout, or setting up payday automation—and do that one thing today.
