
You stare at the bank statement on your kitchen table, wondering how the numbers stopped matching reality months ago.
It is easy to feel like every dollar is already spoken for before the paycheck even clears your account.
You do not need to live on rice and beans or give up your car to find breathing room in your budget.
Here is the exact framework used to trim $1,900 a month by looking where nobody else looks.
Quick Tips Before You Start
Pull Three Months
Gather your last three bank statements before opening any apps.
Ignore the Groceries
Leave your food budget alone for now; attacking food causes burnout.
One Hour Limit
Spend no more than sixty minutes on your first audit session.
1. Give Yourself Permission to Pause
I sat at my kitchen table for three straight hours with a red pen and a stack of overdue statements, convinced I could erase five years of bad habits in one single afternoon.
That kind of manic pressure is exactly why you throw the envelope back in the drawer and avoid looking at your banking app for another month.
Drop the imaginary deadline entirely.
Pick one tiny leak today, save $25 this week, and leave the rest alone until Monday morning.
💡 PRO TIP
The One-Hour Rule
Stop auditing after sixty minutes. Decision fatigue ruins more budgets than overspending ever does.
2. Audit Your Insurance Policies Now
That renewal notice is sitting right there on the kitchen counter, unopened because looking at it feels like facing another invisible tax on just trying to live.
Insurance companies rely heavily on your fatigue and sheer inertia to quietly hike rates by 10 to 15 percent every single year while your coverage stays completely identical. They bet you are too busy to notice, letting the automatic renewal drain your checking account a little more each month without offering anything in return.
Call your current provider today to demand every discount you qualify for, or spend twenty minutes pulling quotes from two competitors to see what the market actually costs. That simple action routinely drops combined auto and home bills by $60 to $120 a month for anyone who has not shopped around in the last three years.
It is an irritating chore that tests your patience on hold, but saving over $1,000 a year for twenty minutes of hassle is one of the highest hourly rates you will ever earn.
Open the envelope before tonight.
Insurance Policy Audit Lanes
- Raise Auto Deductible to $1,000 — Saves up to $40 a month if you keep an emergency fund for the difference.
- Keep Bundled Home and Auto — Check if unbundling saves money, but verify discounts first.
- Ignore Collision on Old Cars — Paying for comprehensive coverage on a car worth $2,000 wastes cash.
3. Talk to a Fee-Only Fiduciary
Schedule a single one-hour consultation with a fee-only fiduciary to review your accounts.
You might look at your retirement accounts and wonder if hidden costs are quietly eating half your future returns.
Most retail investors pay hidden mutual fund fees ranging from 0.5% to 2% annually, which drains tens of thousands of dollars over a working lifetime through compounding expenses.
The mechanism is simple: every percentage point paid in advisory or fund fees is money that stops generating returns for you.
Find an expert who charges a flat hourly rate rather than taking a percentage of your assets under management so your interests stay aligned.
They will review your exact portfolio allocations and point out redundant funds or high expense ratios that quietly drain your net worth.
This is not about chasing market returns or trying to time the next big stock.
It is about plugging structural leaks in accounts you already own so your hard-earned savings actually stay in your pocket.
Fiduciary Check — What to Bring & Ask
4. Build a Three-Bucket Cash Flow System
Divide your checking account into three distinct digital buckets the morning your paycheck lands.
Money disappears simply because it sits in one big pool where rent, groceries, and weekend plans all blur together into one confusing number.
By splitting the funds into fixed bills, debt minimums, and flexible spending, you create boundaries that stop accidental overspending without requiring you to track every single receipt or coffee purchase.
Keep the fixed rent money right where it is, set your debt payments to clear automatically two days later, and move your remaining flexible cash over to a separate debit card you use for everything else.
I spent years watching my balance drop toward zero and wondering where it all went until I separated the rent money from the grocery money.
Log into your banking app today, open two new sub-accounts, and assign your next paycheck a clear job before the week even starts.
The Payday Flow Routine
5. Accept the Trade-Offs of Subscriptions
Cutting five streaming services saves about $65 a month, which adds up to roughly $780 a year if you leave it alone.
The downside is genuinely annoying because it means giving up the shows you actually watch to unwind after a long shift.
Keep the single platform that brings you real value and cancel the rest today before the next auto-renewal hits your account.
⚠️ COMMON MISTAKE
The Streaming Trap
Don't pause subscriptions with annual discounts if you use them weekly. Cut the ones you forgot existed.
6. Establish a Monthly Review Cadence
Why does a budget that felt so solid on the first of the month always seem to unravel by week three?
The answer is simple: a budget is not a monument you carve in stone, but a living ledger that requires a twenty-minute look once every thirty days.
Most of us build a spreadsheet, walk away for six months, and wonder why the math stops matching reality.
prices creep, subscriptions renew quietly, and small lifestyle habits expand to fill every available dollar without you ever noticing.
Put a recurring calendar reminder for the final Sunday of every month to check your totals against your actual bank statements.
Focus your eyes on three specific items during that scan: your fixed bill creep, your total active subscription count, and your current savings transfer rate.
Catching a thirty-dollar unexpected fee increase after thirty days is entirely manageable, whereas catching that same surprise after a full year costs you hundreds of unrecoverable dollars.
Keep the session strictly timed and brief so it feels like a routine household chore rather than an emotional trial you need to avoid.
This week: open your calendar app and drop that recurring Sunday reminder right now.
Monthly Review Checklist — At a Glance
📅 Frequency
Last Sunday
⏱️ Time Spent
20 Minutes
📊 Metrics
3 Key Items
💰 Target Save
Unseen Leaks
Golden Rule
Keep reviews brief to prevent financial burnout.
7. Fix Utility Bill Leaks Quietly
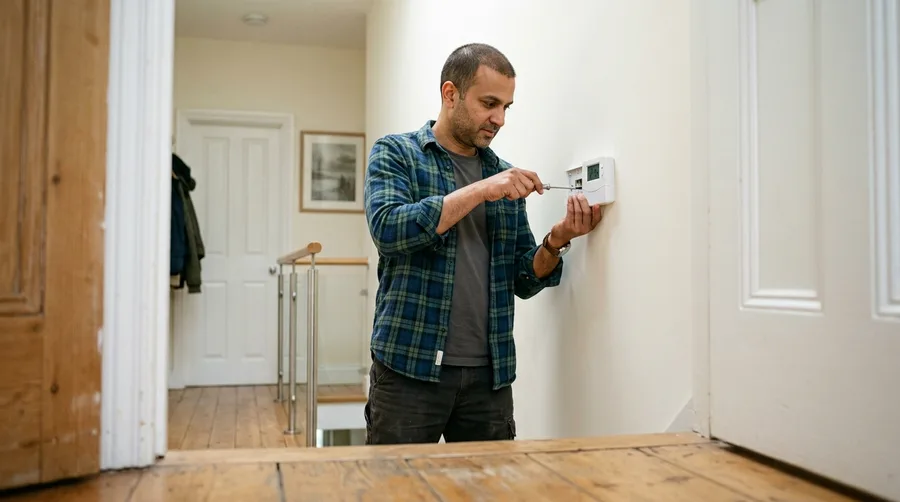
Your utility bills creeping upward doesn't mean you are failing at managing your home.
Most of us assume it is simply the unavoidable cost of existing in a house, resigning ourselves to opening ever-larger billing envelopes every single month without questioning the baseline draw or looking for hidden mechanical drains.
The real waste usually comes from phantom loads and inefficient thermostats quietly running in the background. The common mistake is trying to freeze or sweat it out instead of targeting actual mechanical drains like swapping your incandescent bulbs to LEDs and installing a programmable thermostat set to adjust two degrees while you sleep.
These small adjustments routinely drop utility expenses by $40 to $80 a month without changing your daily comfort at all. I put off doing it for a year because dealing with the settings felt tedious, but the savings hit my very next statement.
Pick one room to update this weekend and let the system do the work for you.
🗺️ Your 30-Day Cash Flow Roadmap
Week 1
Pull three months of statements and highlight fixed bills.
Week 2
Call insurance and telecom providers to negotiate rates.
Week 3
Establish your three-bucket automated transfer system.
Week 4
Cancel unused subscriptions and set your monthly review reminder.
8. My Audit Story With Debt Consolidation
People often assume that once you are buried in high-interest debt, sheer willpower is the only way out of the financial hole.
When my credit card interest crossed 22 percent, I panicked and kept making minimum payments while my balance stayed completely flat month after month. Every statement felt like a personal failure, even though I was pouring every extra dollar I had into keeping up.
The brutal mechanism at play is that high interest devours your cash before it ever touches what you actually borrowed. I finally stopped hiding from the numbers, swallowed my pride, and consolidated $14,000 onto a zero-percent balance transfer card with a 3 percent transfer fee.
That single move saved over $200 a month in interest charges alone, giving me actual breathing room to finally attack the principal instead of watching my payments vanish into thin air. It changed the math overnight.
Check your APRs this week and calculate what you are wasting on interest. A transfer card might be the exact reset you need to start moving forward.
9. Start With the Twenty-Five Dollar Floor
Drop the idea that saving only counts if it is a large, impressive number.
Waiting until you can manage $500 a month means you will likely keep waiting forever, leaving your account at zero while you chase a target that feels too heavy to lift. Even $25 transferred automatically every payday builds the habit, rewires your default spending behavior, and quietly proves to yourself that you can actually live on slightly less than you earn.
Consistency beats financial heroics every single time.
Open your banking app right now and schedule a recurring $25 transfer for the day after your next paycheck hits.
10. Negotiate Your Internet and Phone
It feels intensely awkward to call your internet provider and pretend you are ready to leave, which is why most people just keep paying the creeping rate increase every single year.
retention departments have explicit margins to keep existing subscribers rather than lose them to a local competitor. A quick ten-minute phone call will almost always drop your monthly bill by $30 to $50 just by asking for the current new customer promotional rate.
Make the call on your lunch break this week, and put that thirty dollars back in your pocket.
11. Overcoming the Scarcity Mindset Trap
I spent three years looking at my banking app through one eye because every single dollar felt like proof that I was failing at being an adult.
Scarcity thinking tells you that every restriction is permanent and that wanting to save money means signing up for a life of endless, joyless sacrifice.
That belief keeps you paralyzed in a cycle of total avoidance.
Budgeting feels like a punishment rather than a design choice when you view every purchase as a moral failure.
When you frame financial adjustments as buying your actual freedom instead of just cutting your fun, the heavy emotional resistance starts to vanish.
You are not giving up your entire life; you are simply redirecting money away from mindless autopilot spending toward goals that genuinely matter to you.
Replace the heavy thought that you are broke with the practical realization that your cash just needs a much clearer job description.
Write down three things you value most in your daily life and fund them first before anything else gets a dime.
12. Automate Your Savings Transfers
You can just rely on sheer willpower to transfer money at the end of the month.
That belief is why most savings accounts stay completely empty.
When you wait until the last day to move what is left over, you are betting against your own fatigue and every single impulse purchase that happened during the last four weeks. What survives is usually nothing because convenience always wins when you are tired.
The fix is entirely mechanical rather than behavioral: set an automatic transfer for the morning your paycheck hits, moving at least $50 or $100 straight into a separate account before you even look at your balance. The money disappears before your brain has a chance to negotiate with it, taking the emotion out of the equation completely.
I used to think automation was lazy until I watched my balance finally grow for the first time in three years. Log into your banking app right now and schedule it for your next payday.
13. Stop Paying for Bank Account Fees
It is easy to assume that losing twelve dollars a month to bank fees just means you are bad at managing money, but banks design these charges to quietly slip past your attention.
Paying those monthly maintenance fees on a checking account wastes roughly $120 a year for no reason at all.
The mechanism is simple automated extraction, where traditional institutions rely on consumer fatigue to keep profitable balances trapped.
Switch to a no-fee online bank or set up a direct deposit minimum to waive the charge today.
14. The Real Trade-Off of Cash Flow Audits
$40 a month stops looking small once you spend four hours tracking it down across three different portals and a stack of paper bills.
Cutting fixed expenses takes an annoying Saturday afternoon of phone calls and spreadsheet updates that nobody actually wants to do.
The trade-off is temporary boredom for permanent monthly breathing room, which makes spending your weekend on hold entirely worth it.
15. Review Your Subscription Stack Today
Open your bank app right now and search for recurring monthly charges.
Cancel two subscriptions you haven't touched in thirty days and redirect that cash straight to your emergency buffer.
Take twenty minutes this evening to complete this final step.
Frequently Asked Questions
Is it too late to start organizing my finances if I am over 40?
It is never too late to take control of your cash flow. Starting at 40 gives you decades to compound savings and clean up fixed expenses.
How much should I keep in my emergency fund before investing?
Aim for one month of bare expenses first, then build toward three to six months as your budget stabilizes.
Should I pay off debt or save money first?
Build a small starter fund of $500 to cover immediate surprises, then attack high-interest debt aggressively.
Is it okay to pause my retirement contributions for a short time?
You can pause contributions temporarily if you are facing a severe cash crunch, but resume them as soon as your budget recovers.
Your Next Step
You do not need to overhaul your entire financial life by tomorrow morning to see real results.
Pick one item from this list, complete it today, and let that small momentum carry you forward.
