
You look at your annual salary, cross the six-figure mark, and expect a sudden sense of financial safety.
Instead, the bank account empties out right before the next direct deposit lands, leaving you wondering where every dollar went.
It is easy to blame yourself, assuming you lack discipline or spend too much on trivial luxuries.
The real problem is not your character; it is a structural leak in how modern high incomes are absorbed by silent lifestyle creep.
You can fix this without living on rice and beans, and you do not have to overhaul your entire life by Friday.
Quick Tips Before You Start
Pull Three Months
Export past bank statements to find where fixed costs quietly grew.
Audit Subscriptions
Cancel recurring digital services you have not opened in thirty days.
Separate Savings
Move cash out of your primary checking account immediately on payday.
1. Ignoring the Invisible Cost of Creeping Fixed Expenses
Everyone assumes that being broke on a six-figure salary is driven by impulsive daily spending like luxury coffee or takeout lunches.
That is rarely the actual problem. The real culprit is structural: larger apartments, nicer leased cars, and bundled utility packages that lock up your cash flow before you even see it.
When fixed commitments consume eighty percent of your take-home pay, a single unexpected expense creates an immediate crisis.
The trade-off is deeply uncomfortable. Downsizing your car or moving to a slightly smaller space feels like a painful social step backward after years of working hard to upgrade your life.
It is also the only mathematical way to reclaim the breathing room required to build actual wealth. This week, pull up your last three bank statements and highlight every recurring monthly bill that renews without your active permission.
⚠️ COMMON MISTAKE
The High-Earner Trap
Assuming a higher salary automatically fixes a broken cash flow structure without changing underlying fixed commitments.
2. Waiting Until Next Year to Fix Your Cash Flow
Stop waiting for January or your next birthday to look at where your cash actually went this month. Every thirty-day delay lets another $250 or $350 slip into unmonitored spending while inflation quietly erodes whatever small safety baseline you managed to build.
The mechanism is simple momentum; delaying adjustments means your baseline stays entirely vulnerable to sudden price jumps. I waited until a supposed fresh start once and watched three months of savings vanish into basic living costs.
Open your banking app right now and cap one drain before Friday.
The Spending Traffic Light
- 🟢 Automated savings transfers on payday — Moves money out of reach before lifestyle creep can claim it.
- 🟡 Dining out and entertainment subscriptions — Needs strict monthly caps so it does not swallow your surplus.
- 🔴 Financing luxury vehicle upgrades — Locks up critical monthly cash flow into a rapidly depreciating asset.
3. Starting Small With Micro-Transfers That Actually Stick
Start with a tiny automated transfer of twenty-five dollars every week into a separate account.
A common mistake is trying to save half your paycheck overnight, which causes immediate burnout and frustration when you realize you cannot cover your usual grocery run.
The mechanism relies on behavioral habit formation: consistency beats massive, unsustainable contributions every single time because it avoids triggering the panic response that makes you cancel the transfer altogether.
Even small amounts build the identity of someone who saves money consistently, changing how you view your remaining balance and helping you pause before buying things you do not actually care about.
When twenty-five dollars feels effortless after a month of watching it happen automatically without you lifting a finger, bump it to fifty dollars without changing any other part of your lifestyle.
I started with thirty dollars a week when I was drowning in credit card debt and feeling like my income was completely pointless, and watching that tiny balance grow slowly changed how I viewed my own choices.
The goal is building a permanent habit rather than winning a temporary willpower contest that leaves you exhausted by the time Friday rolls around.
This week: log into your banking app and set up a recurring transfer of twenty-five dollars for the day after your paycheck lands, then leave it alone.
4. Automating Your Savings Before Bills Hit
Seventy-two hours into the new pay period, checking accounts are usually sitting near zero if you rely on saving what is left at the end of the month.
End-of-month saving relies entirely on discipline, which always fails the moment a tiring week or a random expense hits. Shifting that transfer to the exact morning your paycheck lands takes willpower completely out of the equation. You are fixing a timing problem instead of constantly blaming yourself for a lack of focus.
Open your banking app right now and schedule a recurring $50 transfer for every single payday morning.
The Seven-Day Reset Challenge
5. Learning From My Own Expensive Mistakes
When I first crossed into a six-figure salary, I assumed I had earned the right to stop tracking every minor purchase.
That lack of awareness led directly to three thousand dollars in credit card debt accumulated purely through casual dining and rideshares over the course of a single year.
a larger income completely masks sloppy spending patterns until the bill finally catches up to you.
Fixing it required treating my checking account like a closed loop rather than an endless well where money just appeared.
Once I automated my core savings and capped my discretionary spending at $400 a month, the daily financial anxiety finally started to lift.
💡 PRO TIP
The Closed-Loop Account Strategy
Keep your fixed bills and discretionary spending in separate institutions so you are never tempted to bleed across categories.
6. Knowing When to Consult a Fee-Only Professional
You might worry that talking to a professional means you do not know enough, or that your balance sheet is too small to matter.
The truth is that complex tax brackets, employer stock options, and high-income debt structures can quickly outgrow DIY spreadsheets.
When your financial life reaches a certain level of moving parts, guessing can cost you thousands of dollars a year in missed efficiency.
Running your specific numbers past a fee-only fiduciary ensures you are not missing major optimization opportunities.
This is not about buying complex investment products; it is about getting an objective set of eyes on your cash flow.
This week: look up a local fiduciary association online and spend fifteen minutes checking their fee structure before you book a call.
High-Earner Financial Jargon Busted
7. Breaking Free From the High-Earner Comparison Trap
You look around your social circle and assume everyone else easily affords luxury cars, designer wardrobes, and frequent vacations.
Sound familiar?
That comparison game drives high earners to spend every single dollar keeping up appearances, often leaving them with $0 at the end of the month despite pulling in six figures.
The reframe is simple: net worth is what you keep, not what you display on social media or in your driveway.
What I believe now: financial peace looks boring on Instagram, and that is precisely why it works.
This week, track just one category of spending driven entirely by outside eyes and redirect $50 of it straight into your savings account.
Signs of Lifestyle Inflation
8. Setting Up Your Automatic Monthly Transfer Rule
How do you finally stop spending money you meant to save?
Calculate exactly ten percent of your net monthly pay and schedule an automatic transfer for the day after payday.
If you leave this to manual execution every month, you will inevitably find a convincing reason to skip it just this once. Automation removes human emotion from the equation entirely, ensuring the math happens before your daily spending habits get a chance to interfere with your actual goals.
9. Scaling Back Without Feeling Deprived
You have probably tried cutting every single fun thing out of your spending plan at least once, only to watch the whole system implode in a massive takeout binge two weeks later.
Extreme restriction triggers a psychological rebound every single time because willpower is a finite resource, not an infinite well. When you treat budgeting like a jail sentence, the moment you get a key, you run.
Drop the harsh cuts and scale back to just one small pause instead, saving $30 a month on a single subscription while keeping your favorite weekly coffee intact.
Where High Incomes Leak
Federal Reserve SHED 2024 context on hidden cash flow drains
10. Building a Three-Bucket Cash Flow Structure
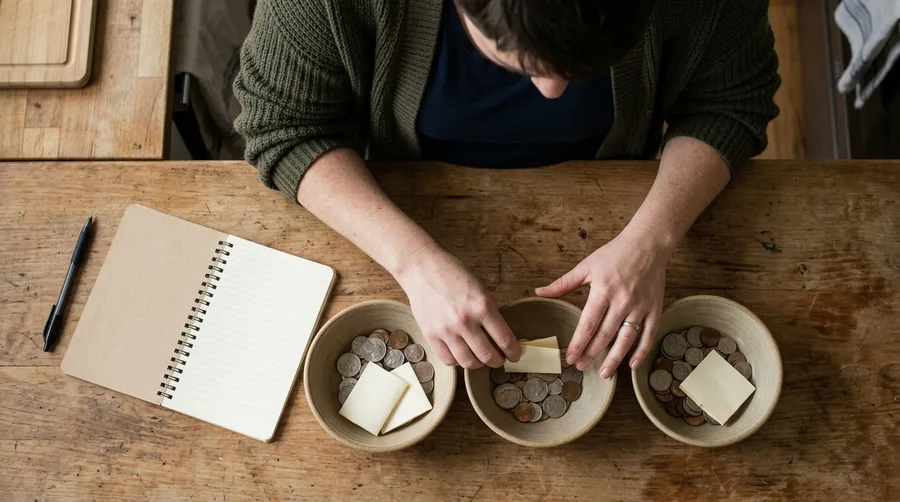
Divide your take-home pay into three distinct buckets the moment your paycheck hits your account.
Bucket one covers your non-negotiable fixed bills like housing, utilities, and insurance, held in an account completely separate from your daily spending card so you are never tempted to dip into it for groceries or coffee.
Bucket two handles every debt obligation via automatic scheduling set precisely two days after your payday arrives, ensuring the minimums get paid before you even look at the remaining balance.
Bucket three takes whatever is left over for groceries and discretionary items, withdrawn in a fixed weekly amount. I used to keep everything in one giant pool and accidentally spend my grocery money on takeout, which made every month a frantic guessing game.
The mechanism stops you from accidentally spending your rent money on weekend dinners because the cash pools are walled off by design. You literally cannot spend what you cannot see, which removes the daily willpower drain of having to make a hundred tiny financial choices.
If you fall short because of an expensive week, fund buckets one and two fully while bucket three takes the temporary hit until payday rolls around again.
This simple structure eliminates mental fatigue and keeps your financial foundation intact without constant spreadsheet maintenance. It turns money management from an exhausting daily chore into a background system that runs quietly on autopilot.
This week, log into your primary bank and open one secondary checking account to become your fixed bills pool.
11. Reviewing Your Numbers Once Every Three Months
You do not need to check your bank account every morning, and ignoring it completely until tax season is how a ten-dollar mystery fee turns into a four-hundred-dollar overdraft headache.
Set a calendar alert for once every ninety days to look at two things only: your subscription stack and your actual savings rate.
Open your calendar right now and drop in the next reminder for three months out, then close the app and leave your balance alone until then.
12. Fixing the Common Mistake of Ignoring Small Drains
Where does all the money actually go when you are making decent wages and still watching the balance slide backward by the third week of the month?
It leaves in increments so small you never bother to look at them.
People routinely dismiss twelve-dollar app subscriptions, twenty-dollar service fees, and daily delivery charges as the cost of getting through a demanding week, treating them as rounding errors that do not matter.
The mistake is not that you enjoy those little conveniences, but that you assume they live in a vacuum where a dozen isolated charges have zero cumulative power over your financial life.
Those minor expenses compound silently across a twelve-month period, draining hundreds or even thousands of dollars that could otherwise quietly fund your emergency cushion or clear out a stubborn balance.
When you add up twelve dollars a month for a streaming service you forgot about, fifteen dollars for a utility fee, and forty dollars in delivery markups every week, you are looking at nearly $2,500 disappearing into the background every single year without you ever making a conscious choice to spend it there.
The correction is ruthless subscription auditing: cancel every single recurring charge you have not actively utilized, opened, or benefited from in the last thirty days.
The mechanism here is purely about restoring cash flow visibility and teaching your brain to attach real weight to intentional spending instead of letting financial friction bleed you dry.
Once you eliminate mindless recurring charges, you suddenly find hundreds of dollars available for actual wealth-building goals that felt completely out of reach when every dollar was spoken for.
This week: open your online banking portal, pull the transaction history for the past sixty days, highlight every single recurring charge, and kill three of them before you close the tab.
13. Capturing the Power of Compounding This Month
Twelve months of hesitation costs you real growth.
Compound growth works through time rather than luck. When your savings sit in an account earning a return, those earnings generate their own earnings day after day. Waiting a year to start means missing out on the period when that momentum accelerates.
If you put $300 a month into a standard market index fund that averaged 7 percent annually, your balance after ten years would reach roughly $50,000. That is illustrative math rather than a guarantee, because markets drop in some years and rise in others. The exact figure matters less than the shape of the curve.
Starting this month instead of next year lets you capture that initial growth sooner without needing a massive deposit. Even $50 saved right now beats $500 planned for next spring.
Open your savings account today and move your first transfer before the weekend.
14. My Personal Turning Point With Credit Card Debt
I spent years paying minimums on a five-thousand-dollar balance while making a decent salary, wondering why my net worth stayed flat.
The turning point came when I redirected half my monthly bonus straight toward clearing that balance in one lump sum instead of letting it slip into general checking.
That single move saved me hundreds in interest charges over the year and proved that a high income means nothing without aggressive principal reduction.
Open your statements today and calculate what you paid in interest last month, then put one extra fifty-dollar payment toward the principal before the week ends.
15. Starting Your Tiny Wealth Foundation Today
You have probably told yourself that you need thousands of dollars in spare cash before you can finally start building real wealth.
That belief keeps thousands of people paralyzed because it makes saving feel like an exclusive club you are locked out of.
The truth is that compound interest and asset accumulation do not care if your initial deposit looks impressive on paper.
Commit to moving just $25 into a separate savings account before this current week officially comes to an end.
The exact dollar amount matters far less than finally establishing the habit of paying your future self first.
Build from there at your own steady pace, and watch your daily financial anxiety slowly give way to lasting security.
Frequently Asked Questions
Is it too late to start saving and investing if I am already in my 40s?
It is never too late to begin restructuring your cash flow. While starting earlier helps, increasing your savings rate and maximizing tax-advantaged accounts in your 40s can rapidly accelerate your net worth.
How much should I keep in my emergency fund as a high earner?
Aim for three to six months of essential bare-bones living expenses held in a high-yield savings account. High earners often need robust buffers due to variable bonuses or commission structures.
Should I pay off debt or save for investments first?
Knock out high-interest consumer debt above eight percent APR immediately while maintaining a small starter emergency fund. Lower-interest debt can be tackled alongside steady retirement contributions.
Is it okay to pause my retirement contributions for a short while?
Pausing contributions temporarily to handle an acute financial emergency or clear high-interest debt is acceptable. Resume them as soon as possible to avoid breaking your long-term compounding momentum.
Start With This One Move
If you take only one action from this entire guide, open a separate savings account today and automate your first transfer.
You do not need to fix everything by Friday, but you do need to take that first small step toward keeping what you earn.
