
You sit down with a cup of coffee, look at your bank login, and immediately want to close the tab. The month slipped away, the savings number didn't move much, and you have that lingering feeling that you are missing something important.
It is not that you are bad with money. It is just that life gets loud, automated payments run in the background, and you never actually pause to look at the whole picture.
You do not need a three-day retreat or a finance degree to fix this. You need ninety minutes, a quiet kitchen table, and a structured way to look at where your dollars are actually going.
I spent years dreading this exact audit until I built a simple checklist that took the emotion out of it. Here is how to run your own annual money review this weekend without losing your mind.
Quick Tips Before You Start
Clear the Table
Put away your phone and grab a physical notebook so you are not tempted to open ten browser tabs.
Set a Timer
Ninety minutes is plenty of time if you do not let yourself get bogged down searching for old passwords.
Drop the Guilt
You are looking at data, not grading your moral character, so keep your breathing steady.
1. Stop Believing You Are Behind Everyone Else
You open Instagram and assume everyone your age owns a home, maxes out their retirement accounts, and never stares anxiously at a grocery receipt. That invisible benchmark makes you feel so far behind you avoid opening your bank app for weeks.
The reality is much messier behind closed doors, where roughly 60 percent of households live month to month and juggle surprise expenses. New belief: your financial life is not a race against strangers on a screen. This week, close the apps, open your actual statement, and write down just one number-what you actually have right now, without shame.
2. Give Yourself Full Permission to Scale Back
You feel like if you cannot save $500 a month, saving $50 is completely pointless. That all-or-nothing trap destroys more monthly budgets than inflation ever did.
Drop the heavy goals for right now and scale your targets down until they feel ridiculously easy to hit. Consistency beats intensity every single time because a $25 weekly transfer that actually happens beats a $400 goal you abandon by March.
I spent years quitting programs because I could not hit the max amount right away. Lower the bar on purpose so you can keep moving. This week: cut your current target in half without guilt.
Review Snapshot
3. Automate Your Savings Before Payday Hits
Set an automatic transfer for the morning after your paycheck lands so the savings happen without requiring your active permission every single time.
Willpower is a terrible budgeting tool after a long week at work, and if money sits in your main checking account, everyday expenses will always find a way to absorb it. I used to think I just lacked discipline, but relying on myself to manually move money on a Friday afternoon meant I missed months at a time because life simply got in the way.
The mechanism relies entirely on cash flow timing rather than extra effort, locking away a specific slice-start with an honest $50 or $100 per check if that is what your budget handles-before you ever see it in your available balance. That tiny forced friction completely changes what you spend for the rest of the pay period without requiring a single spreadsheet.
It takes about four minutes inside your banking app to link the accounts and establish this recurring rule so you never have to think about it again.
Set it up today and let it run quietly in the background.
💡 Tip: Split your direct deposit if your employer allows it so the savings never touch your main spending account.
💡 PRO TIP
The Power of Friction
Delete shopping apps from your phone. Adding a two-step web login requirement cuts impulsive spending by half.
4. Count the True Cost of Your Subscriptions
Subscription creep happens ten dollars at a time until you are bleeding one hundred and fifty dollars a month on streaming services, fitness apps, and delivery boxes you completely forgot existed.
A fifteen dollar monthly fee is actually one hundred and eighty dollars a year, plus the extra taxed income you had to earn just to cover it.
The trade off here is entirely honest and slightly painful: cancelling these services takes an annoying afternoon of hunting through support chats and password resets.
Do it anyway to free up immediate cash flow for things that actually move the needle on your debt or savings.
Open your last bank statement right now, find three recurring charges you have not used in thirty days, and cancel them before you close the tab.
Money Terms Decoded
5. Build a Simple Three-Bucket Cash Flow System
Why does your checking account always seem to hit zero before payday, even when you feel like you are being careful?
Money management falls apart when all your cash sits in one big pool where rent, groceries, and weekend plans fight for dominance. I rebuilt my own finances around this exact split after running out of money two days before payday and staring down a tank of gas I could not afford. When everything mixes together, you are forced to guess what you can safely spend every single day, and that mental load exhausts you.
The fix is to separate your cash into three clear buckets: fixed bills, debt minimums, and flexible spending. Here is the mechanism: when your fixed bills have their own designated home, you stop accidentally spending your rent money on groceries or dinner out.
Aim to fund fixed expenses first, minimum debt payments second, and let flexible spending take whatever remains. If your pay fluctuates from month to month, fund the absolute necessities first and keep a $300 buffer in your checking account to catch the dips. This order protects your housing and your baseline survival before fun gets a single vote.
The trade-off is real: setting up multiple accounts and splitting your direct deposits takes about twenty minutes of administrative hassle, some initial setup friction, and remembering which card is tied to which bucket.
Do it anyway, because willpower alone cannot defeat a messy cash flow.
This week, open one separate savings account for upcoming annual bills like car insurance so they never ambush your monthly cash flow again.
Three-Bucket System — The Numbers Behind It
🏠 Bucket 1 Target
One full month of fixed bills, held one paycheck ahead
💳 Bucket 2 Target
Every minimum payment, automated two days after payday
🍕 Bucket 3 Limit
Withdrawn weekly, not daily, to control small leaks
Skip This If
Your pay lands more than twice a month — use a weekly percentage split instead.
6. Beat the Credit Card Interest Trap Now
I stared at a $4,200 credit card balance for six months while making minimum payments and wondering why the principal barely moved an inch.
Carrying that balance on a card charging 21% APR means your hard work is funding bank profits instead of your own future.
The average credit card rate sits around 20% to 21% according to Federal Reserve data, making high-interest debt the most expensive emergency you can carry, so tackle this this month by calling your issuer to request a rate reduction or moving the balance to a lower-cost option.
⚠️ COMMON MISTAKE
The Minimum Payment Trap
Paying only the minimum due on credit cards stretches a $2,000 balance into a multi-year debt sentence.
7. Fix Your Emergency Fund Allocation Mistakes
Stop letting your emergency cash sit dead in a checking account earning zero point zero percent interest.
Most people make one of two severe allocation mistakes with their safety net. They either keep zero cash and live one flat tire away from a payday loan, or they let $10,000 idle in a traditional checking account where inflation slowly eats its purchasing power every single month.
an emergency fund is insurance against bad Tuesdays, not an investment vehicle. Keeping three months of bare expenses in a high-yield savings account gives you a reliable cushion while beating inflation slightly better than a standard brick-and-mortar bank.
Start with one month of bare expenses, which for many households falls somewhere between $2,000 and $3,500. Get there first, and then steadily build toward three full months.
If one month feels completely out of reach right now, aim for a $500 starter buffer instead to block the most common financial surprises.
I kept all my savings in my primary checking account for years until an unexpected car repair completely wiped out my grocery money for the week.
The trade-off is lower immediate returns compared to putting that cash into the stock market, but absolute peace of mind is worth the yield difference.
This week: open a separate online savings account and move your emergency cash into it immediately.
Emergency Fund Realities
8. Learn From My Balance Transfer Missteps
The panic of watching interest swallow your minimum payment is a heavy thing to sit with at midnight.
I thought I outsmarted it a few years ago by moving $4,500 of credit card debt to a zero-percent balance transfer card, breathing a massive sigh of relief. But I made the mistake of leaving my underlying spending habits untouched, and the old card filled right back up within six months.
You cannot out-transfer a spending leak, so pause the card applications and track exactly where your cash went last week before moving a single dollar.
9. Schedule Your Monthly Money Check-Ins
I used to open my banking app with my heart in my throat, terrified of what I might find waiting for me on the screen.
That avoidance is why I missed a stray subscription fee that quietly drained $15 a month for nearly half a year.
A yearly review gives you direction, but monthly check-ins keep you from drifting off course before small leaks turn into major damage.
Set a recurring calendar reminder for the first Sunday of every month to look over your accounts without judgment.
Take twenty minutes to check your balances, verify your savings transfers happened, and adjust your grocery category if needed.
Consistency beats perfection every single time.
Monthly Money Routine
10. Update Your Retirement Contributions Today
Log into your workplace retirement portal and bump your contribution percentage up by just 1% this week.
Leaving your retirement percentage at the default setting means you miss out on years of compounding growth, which is simply interest earning interest on itself over time. I left mine at the default minimum for three years because touching it felt like extra paperwork I simply did not have the mental bandwidth for, and I quietly lost ground I did not need to lose.
If you increase your contribution by 1% right now, you will honestly not even notice the difference in your take-home pay when it hits your account. For someone earning $50,000 a year, that small shift amounts to roughly $10 a week, yet it fundamentally alters your long-term trajectory without forcing a harsh lifestyle overhaul or cutting things you enjoy.
Take four minutes right now to open the system, find the contribution settings, and make the adjustment before you close out of your browser.
11. Know When to Talk to a Professional
Book time with a fee-only fiduciary when your financial questions involve legal penalties or major structural changes that articles simply cannot solve.
Reading guides helps build a foundation, but complex tax situations, sudden inheritances, or untangling tangled debt require an expert pair of eyes to look at your actual numbers.
A single consultation can save you thousands of dollars in costly mistakes, and paying for professional guidance once is far cheaper than fixing a $5,000 tax error on your own next April.
12. Start Small With the Twenty-Five Dollar Floor
Can you actually build any real momentum when you only have a few spare dollars left at the end of the month?
The short answer is yes, because the math matters far less than the habit in the beginning.
When your checking account is hovering near zero, staring at a massive savings goal makes you want to close the banking app and ignore the problem entirely.
if you cannot save $200 right now, your brain tells you that saving nothing at all is the only logical choice.
The mechanism behind a tiny floor is simple behavioural momentum.
When you set aside a tiny amount automatically, you start seeing yourself as someone who saves money, which quietly shifts your entire financial identity over time.
I started with $15 a week when my freelance income dipped so low I was eating plain pasta for dinner.
It felt ridiculous at the time, like bailing out the Titanic with a teaspoon.
The trade-off is brutally slow initial progress, and your balance will not look impressive after six months of consistency.
Build the habit first, because the math only starts working for you once the transfer actually happens without your active permission.
If $25 is too much for this paycheck to handle without bouncing a utility bill, drop it down to $10.
This week: open your app and set up a recurring automatic transfer for whatever tiny amount you will not notice missing.
13. Review Your Annual Financial Checkpoints
Reviewing your whole financial life once a year sounds terrifying if you picture it as an audit where you find out you failed.
It is actually just a quiet 90-minute scan to make sure your net worth and insurance coverage still match your actual life.
Most people never look at their beneficiaries again after they fill out the onboarding paperwork at a new job, which means old names stay on accounts for decades.
Take one afternoon this month to open your portals, check that your policies reflect your current stage, and log your total assets minus debts so you can see the trajectory instead of guessing.
This simple habit takes the panic out of the numbers because nothing stays hidden in the dark for years at a time.
14. Take Advantage of Compounding Before Next Month
There is a quiet panic that sets in when you look at the calendar and realize another year has slipped past without your savings growing the way you hoped.
You tell yourself you will start once things settle down, once the car is paid off, or once you finally get that raise at work.
The hidden cost of waiting is not just the missed deposits, but the loss of compounding time, which is the mechanism where your earnings start generating their own earnings day after day.
If you invest $200 a month starting at age thirty instead of thirty-five, that five-year gap can change your final balance by tens of thousands of dollars over the long term, though no specific market return can ever be promised.
Open that account this afternoon and move your first $50 into it, because starting right now beats waiting for a better month that never seems to arrive.
15. Establish Your Three-Bucket Savings Routine
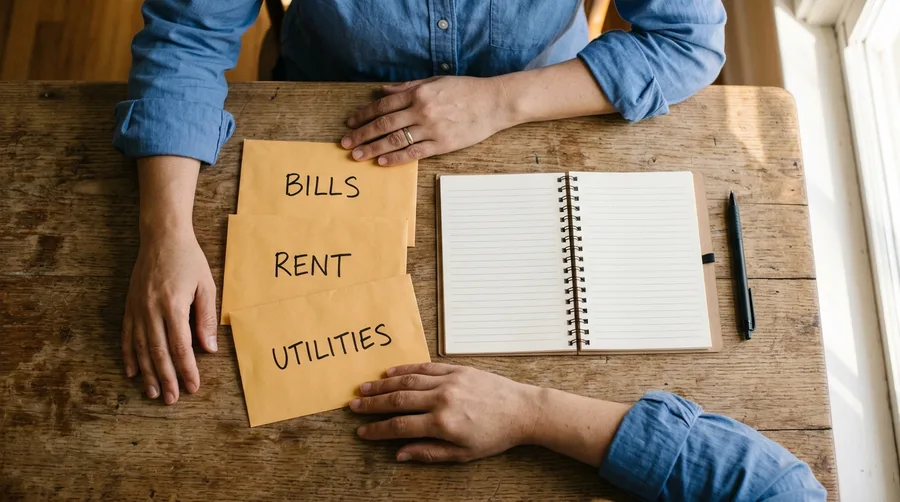
Most people assume a financial routine requires managing a dozen different accounts every single week.
That is a myth that guarantees burnout within a month.
Instead, divide your money into three distinct buckets for fixed bills, debt payments, and flexible spending.
Automate the first two on payday morning so they happen without your active participation.
Let whatever remains sit in the flexible bucket for your daily expenses, capping that amount at roughly $400 a week.
Review the whole system once a year to adjust for raises or new bills, and you are done.
Frequently Asked Questions
Is it too late to start investing at 40?
It is definitely not too late. Starting at 40 still gives you two decades or more of compound growth, especially if you focus on consistent monthly contributions.
How much should I have in my emergency fund?
Aim for three to six months of bare living expenses, but start with a $500 buffer if that feels overwhelming right now.
Should I pay off debt or save first?
Build a small starter fund of $500 first to stop new debt, then aggressively tackle high-interest credit card balances before building a larger cushion.
Is it okay to pause my retirement contributions for a while?
Yes, if you face a genuine financial hardship like job loss or medical emergency. Just set a calendar reminder to restart them as soon as you stabilize.
Your Next Step
You do not need to overhaul your entire financial life by tonight. Pick just one move from this list—open that separate savings account or bump your automatic transfer by $25—and get it done.
Progress comes from small, repeated actions taken at your kitchen table, not perfection.
