
You keep seeing the same viral video on your feed: a creator holding up a single piece of paper, claiming it is a secret legal loophole that forces credit bureaus to erase every negative mark from your report in thirty days. It sounds like the relief you have been waiting for, especially when your score is sitting lower than you want.
It is tempting to believe there is a magic trick to bypass years of financial history. The reality is far more ordinary, and understanding how the process actually works will save you time, money, and frustration.
Section 609 of the Fair Credit Reporting Act gives you the right to request a copy of your credit file and ask the bureaus to verify the information they are reporting. That is it. There is no hidden legal cheat code, but knowing how to use your actual rights properly can still help you clean up reporting errors.
Quick Tips Before You Start
Send via Mail
Always mail your requests with tracking so you have proof of delivery.
Allow 30 Days
Bureaus legally have thirty days to respond once they receive your letter.
Keep Copies
Keep a physical folder with every letter, report, and response you receive.
Focus on Errors
Your energy is best spent disputing actual mistakes, not valid debts.
1. Requesting Your Official Credit File
You stare at your phone screen, watching your credit score drop ten points because of a medical bill you already paid six months ago, and the familiar panic of feeling completely powerless sets in.
Under federal law, you are entitled to see every piece of data the major bureaus hold on you without paying a third-party service twenty or thirty dollars a month for the privilege.
Order your reports directly through the official government-mandated site at annualcreditreport.com instead, and set a recurring calendar alert for every four months to keep an eye on things without spending a dime.
💡 PRO TIP
Get All Three Reports
Pull your files from Equifax, Experian, and TransUnion at the same time. Lenders rarely report to all three, so an error on one might not appear on the others.
2. Understanding the Fair Credit Reporting Act
Is there a secret shortcut hidden inside federal statute books that lets you wipe your credit slate clean overnight?
Online forums and social media video clips make it sound like an absolute certainty, promising total deletion of negative marks if you just use the right legal phrasing or magic words.
The Fair Credit Reporting Act was actually written to ensure reporting accuracy and protect consumer data, not to provide a get-out-of-jail-free card for valid financial obligations or past missed payments.
The honest trade-off here is that accepting this reality feels frustrating because it strips away the fantasy of a quick fix, leaving you with the slower, unglamorous work of finding actual factual discrepancies instead.
This week, skip the secret loophole forums entirely, pull your actual paper or digital reports, and spend 30 minutes looking for an error involving a wrong balance or an outdated date of last activity.
What the Law Covers
3. Starting Small With Bureau Disputes
Only $25 a month goes toward your credit builder account, and you probably wonder if such tiny steps even matter when your report looks like a mess.
Consistency beats grand gestures every single time because small, repeatable actions keep you from burning out under the weight of bureaucratic paperwork. When I first tried cleaning up my history, I wanted to challenge everything by Friday, which only left me staring blankly at dispute forms until midnight.
Pick one single inaccurate trade line to dispute first instead of trying to tackle twenty items at once.
Credit Dispute Realities
4. Recognizing Credit Repair Myths
You might feel like everyone else has pristine credit while you are left dealing with past financial mistakes all by yourself.
That heavy feeling of isolation is completely normal, but it is fueled by viral internet myths rather than actual legal reality. When online personalities claim that a specific secret template completely erases bankruptcies or major collections, they are selling false hope instead of law. The credit bureaus process millions of dispute letters annually, and they easily spot mass-produced scripts that lack individual context or specific evidence.
Real progress is far less glamorous.
True credit correction comes from methodical verification under federal law, not from mailing unverified loopholes that cost $50 or more for a generic downloadable PDF template.
What I learned the hard way is that simple, careful consistency beats any viral shortcut every single time. This week, throw away any pre-written script you bought online and spend 30 minutes drafting one plain-language note focused solely on a single inaccurate line item on your report.
⚠️ COMMON MISTAKE
Avoid Paid Template Sites
Never pay money for proprietary dispute letters online. The information required to challenge an inaccurate entry is already publicly available.
5. Building a Reliable Dispute System
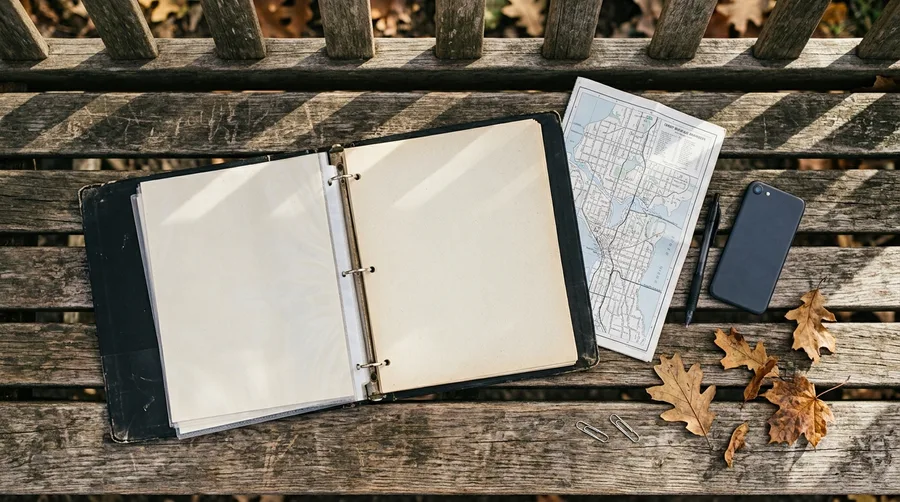
Grab a physical three-ring binder and twelve plastic sheet protectors before you mail anything to the credit bureaus.
Most people keep dispute paperwork scattered across browser tabs and random desktop folders until a collection agency calls, and that chaos is exactly how deadlines slip.
A paper trail changes the power dynamic completely because financial institutions operate on documentation, not memories or frustration.
Slide your printed credit report into the first sleeve, use a highlighter to mark the specific account number you are challenging, and keep every single certified mail receipt tucked right behind it.
Set a calendar alert for exactly thirty-five days from the date your envelope hit the post office, giving the bureau the statutory thirty days to investigate plus five days for mail transit.
When that reminder notification pops up on your phone, you will not have to guess whether they received your letter or wonder what to do next because the certified mail tracking number proves delivery.
I used to throw away green cards and panic when a new bill arrived, but organizing the correspondence physically stopped the dread from creeping in every time I checked the mailbox.
Open your binder tonight, slide in your current reports, and write down your first thirty-day follow-up date in ink.
Dispute Tracking System — At a Glance
📁 Storage
Physical binder
📬 Delivery
Certified mail
⏰ Window
30 days strict
📋 Log
Date and response
Golden Rule
If it is not in writing with a receipt, it did not happen.
6. Reviewing Your Progress Regularly
I checked my own reports every quarter for a full year after my divorce, watching small errors slowly disappear.
Review your scores every three months, focusing on whether disputed items were updated, verified, or deleted.
Take fifteen minutes with your coffee to look over the changes and ensure your credit file is finally moving in the right direction.
7. Timelines and Verification Deadlines
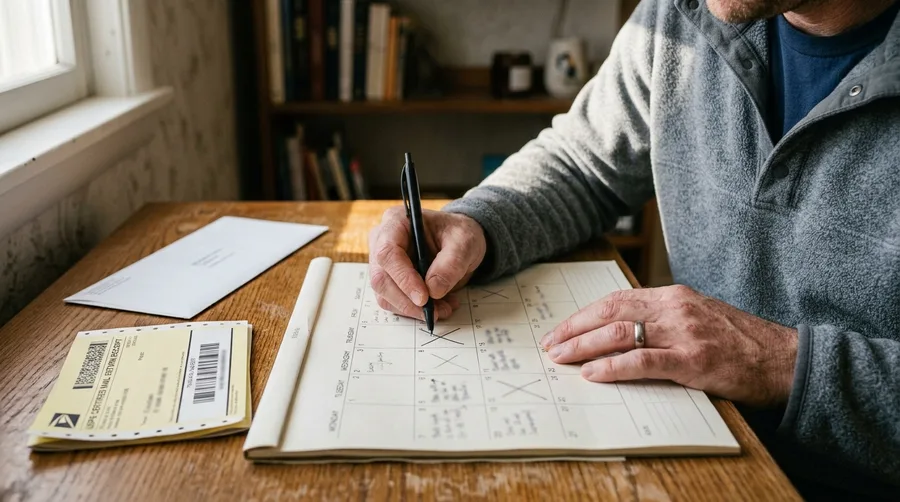
Many people assume that if a credit bureau takes thirty-one days to reply, the disputed debt automatically vanishes forever.
That is a widespread misconception that ignores how credit bureau operations actually function behind the scenes.
Under the law, the standard investigation window is thirty days from the date they receive your notice, though it can stretch to forty-five days if you submit additional information during that same dispute cycle.
If they miss the statutory window, they are required by regulation to remove the disputed item, but creditors often simply re-verify and re-insert the data later once the paperwork catches up.
I watched a collection account disappear on day thirty-two only to reappear three weeks later with a fresh update date, which taught me that timing matters less than having a paper trail.
This week: mark a strict thirty-day calendar reminder the moment your certified mail return receipt arrives, and do not panic if the response lands on day twenty-nine.
Credit Bureau Terminology
8. My Experience With Bureau Disputes
I once spent four months arguing back and forth about an incorrect late payment that dropped my credit score by forty points right when I was trying to map out a modest car loan.
It took three separate certified letters with tracking numbers and a direct online complaint to the consumer protection bureau before the phantom debt finally vanished from my credit file entirely.
Persistence pays off, but patience is your real currency when dealing with automated bureaucratic loops, so use this week to mail your documentation and track the thirty-day response window closely.
9. Common Disputing Mistakes to Avoid
It is completely normal to want every single blemish gone from your credit report all at once.
When you are looking at a score that feels like it is holding you back from renting an apartment or buying a car, the temptation to dispute twenty things on a Friday night is almost overwhelming.
The mistake is firing off a massive wave of blanket challenges against every collection account and late payment simultaneously.
The credit bureaus see this shotgun approach coming from a mile away.
Under the rules governing these disputes, they have the legal right to label your claims as frivolous and simply ignore them if they lack specific reasoning.
When you flood the system with dozens of simultaneous claims without a targeted focus, you instantly lose the credibility that makes a legitimate dispute work.
Instead of trying to wipe the slate clean in one chaotic afternoon, pull back and select the two or three most glaring errors on your report to start.
Build a clean paper trail for each specific item, give each claim the attention it requires, and let the methodical correction process protect your standing for the long haul.
Dispute Strategies Compared
What Works
- Targeting specific reporting errors
- Using certified mail with return receipt
- Attaching supporting document copies
- Waiting out the 30-day statutory window
What Fails
- Using secret legal loop-hole templates
- Disputing every single account at once
- Calling phone support without a paper trail
- Expecting overnight score miracles
10. Knowing When to Consult a Professional
I remember staring at a collection notice for a medical debt I had already paid, feeling that familiar chest-tightening panic creep in while trying to figure out the legal jargon on my own.
Sometimes your credit situation involves identity theft, complex legal judgments, or collection agencies violating federal laws repeatedly, and trying to fix every single error by yourself only leads to burnout.
When dealing with severe reporting violations or harassment, running it alone might not be enough because the legal system has specific rules that everyday consumers rarely encounter.
Consult a certified consumer protection attorney or a reputable non-profit credit counselor to review your specific numbers before taking further legal steps.
Gather your paper trail and schedule a free consultation this week to get expert eyes on your file.
11. Scaling Back When You Feel Overwhelmed
30 days is usually all it takes for routine financial housekeeping to turn into a full-blown mental exhaustion trap if you let the process run your daily life.
I spent three straight months staring at dispute letters and credit dashboards until my eyes blurred, genuinely believing that if I took my foot off the gas for even a single week, my score would plummet back down.
That is completely false, because credit healing is built on slow multi-month trends rather than daily score fluctuations, and stressing yourself out over a single point does nothing to speed up the bureaus.
It is entirely okay to step back and pause your credit repair efforts for a month when life gets heavy, your family needs your attention, or work demands everything you have left.
Burnout happens when you treat routine financial maintenance like an emergency room visit where every slight delay feels catastrophic, draining the exact mental energy you need to handle your actual living expenses.
Scale your process right back to checking your dashboard just once a month for a maximum of 15 minutes, and explicitly promise yourself you will not mail out a single new letter during that time.
True consistency means staying in the game at a sustainable pace over the course of an entire year, rather than running yourself completely into the ground trying to fix a multi-year reporting problem in a fortnight.
Close the extra browser tabs tonight.
12. Submitting Your First Formal Dispute
Most people assume you can fire off a quick online form or an angry email to fix credit report errors in five minutes. You cannot.
Mail your typed dispute letter to the specific bureau address listed on your official credit report.
Include your full legal name, current address, date of birth, and a clear copy of a government-issued ID to prevent delays. Do this this week to get your thirty-day clock moving.
13. Managing Expectations and Slow Progress
You do not have to fix your entire credit history by next Friday to make meaningful financial progress.
Scores rise slowly as old negative marks age and new positive habits take root in your profile, often taking anywhere from 30 to 90 days for a single adjustment to fully register across all three major reporting bureaus.
Focus on maintaining your current accounts with zero missed payments while waiting for bureau responses to clear through the slow-moving system.
Patience is your best ally when dealing with institutional bureaucracy that moves at a snail's pace, and checking your report every single morning will only drive you crazy without speeding up the timeline by a single day.
Close the tab, set a calendar reminder for 30 days from now, and go spend your evening on something that actually brings you peace.
14. Reviewing Results After Thirty Days
Log into your online credit portal on day thirty-one to check the exact status of your disputed item.
The reporting agencies operate under a strict thirty-day window by law, meaning you need to verify whether they deleted the error, updated the details, or verified it as accurate. Checking right on schedule stops you from second-guessing your timeline or losing track of your next move.
Write the final outcome, the specific response code, and today's date into your physical binder immediately so you maintain a completely bulletproof paper trail for your records.
15. Correcting Stubborn Reporting Errors
Hitting a brick wall when a credit bureau verifies an inaccurate debt anyway makes you want to throw your laptop out the window and give up entirely.
The mistake most people make right here is firing off the exact same dispute letter a second time, which usually results in a speedy automated rejection.
Bureau systems process millions of generic dispute forms through automated filters, meaning persistent errors rarely get a nuanced human look the second time around.
Shifting your strategy to contact the original creditor directly with your paper trail bypasses the bureaucratic bottleneck entirely.
Send a concise, factual letter with copies of your proof attached, giving them 30 days to update their records or face potential regulatory scrutiny.
This pivot changes the entire dynamic because the original creditor holds the actual ledger and hates compliance risks more than anyone else.
Frequently Asked Questions
Does the Section 609 letter legally erase valid negative marks?
No. Section 609 gives you the right to request your credit file and ask bureaus to verify data. If a negative mark is accurate and verifiable, the bureau is not legally required to delete it just because you mailed a specific letter.
Can I use free online templates for my credit disputes?
You can use standard dispute templates, but you should avoid paying companies for secret legal formulas. The bureaus process template letters daily, and your success depends entirely on pointing out actual reporting errors rather than using special phrasing.
How long do credit bureaus have to respond to a dispute?
Under the Fair Credit Reporting Act, credit reporting agencies generally have thirty days from the date they receive your dispute to investigate and respond to your request.
What should I do if a bureau verifies an incorrect debt?
If a bureau verifies an inaccurate item, your best next step is contacting the original data furnisher or creditor directly with your supporting documentation to demand a correction.
Should I pay a credit repair company to handle this for me?
Most credit repair services charge monthly fees to do tasks you can easily do yourself for free. If your situation involves complex legal judgments or identity theft, consulting a consumer protection attorney is a safer alternative.
Start With This One
Fixing your credit report does not require secret loopholes or paid services. It takes patience, accurate documentation, and a willingness to focus on real errors instead of chasing internet myths.
Pull your official reports today, pick one single mistake to challenge, and take the first step at your own pace.
