
You look at the balance on your screen, and the math simply does not close.
When revolving interest hovers around twenty percent while you are trying to catch up on retirement savings in your late forties, standard advice breaks down completely. Most planning guides assume you enter this decade with a clean slate. That is not your reality.
This is fixable, but only if you stop treating retirement savings and high-interest debt as two separate problems.
Quick Tips Before You Start
Stop New Charges
Freeze card use immediately to prevent the balance from growing.
Pull Your Reports
Check every open line and exact interest rate before making a move.
Give It Time
Expect twenty-four months of aggressive focus to turn the numbers around.
Call Lenders
Ask for temporary hardship rates to drop your interest immediately.
1. Calculate Your True Interest Drag
How much are your credit card balances actually costing you every single month?
When your card charges an annual percentage rate of twenty-one percent, every dollar you keep parked there is bleeding your future cash flow.
Multiply your total balance by your average rate right now to see the annual leakage. If you carry fifteen thousand dollars, you are paying over three thousand dollars a year just in interest that vanishes before it ever touches a principal balance.
That is money that should be compounding in a low-cost index fund tracking the whole market instead of buying bank profit.
💡 Tip: Look at the dollar cost on your latest statement, not just the percentage.
Debt Math at a Glance
2. Automate Your Debt Payments
People think discipline is the missing ingredient when automation is the real fix.
Relying on memory or manual transfers leaves room for hesitation every time payday arrives, and hesitation is usually where good intentions quietly go to die.
Set up automatic minimums plus an extra fixed amount, like an additional $150 or $250 a month, scheduled for the exact morning your paycheck hits your checking account.
This removes emotion entirely from the equation by taking the decision out of your hands before you even have a chance to second-guess it.
Your checking account quickly adapts to what is left over, making paying down balances feel like a background utility rather than a painful monthly punishment.
💡 PRO TIP
Automate the Extra Transfer
Schedule your extra debt payment for the exact morning your paycheck clears so the money disappears before you can spend it.
3. Adopt a Three-Bucket Cash Flow
The knot in your stomach usually comes from not knowing where your money goes.
Divide your take-home pay into three strict buckets immediately: fixed bills, debt minimums, and flexible spending.
Keep your bills in a completely separate account so rent and utilities never touch your grocery money.
This structure protects your basic survival while funneling every spare dollar toward high-interest balances.
When an unexpected $400 car repair pops up, you fund it from your flexible bucket without adding to your plastic debt.
This week: open one separate checking account and move your fixed bills into it.
4. Pause Aggressive Retirement Saving
It feels terrifying to dial back your 401(k) contributions when you are past forty-five and worried about the finish line.
Drop your retirement contributions down to your employer match if you have one, but pause any extra voluntary investing until your cards are at zero.
Earning seven percent in the stock market while paying twenty-one percent on credit card interest is backward math.
Clear the high-rate drag first, then turn the retirement firehose back on with full force.
⚠️ COMMON MISTAKE
The Math Trap
Never keep investing extra cash while holding twenty percent credit card balances. The interest leak eats any market gains.
5. Fix Your Spending Leak Points
Stop hunting for tiny expenses to eliminate from your daily routine.
Cutting out $4 coffees will not move the needle when your real financial leaks are hiding elsewhere, and treating yourself like a project to be punished only leads to burnout within a fortnight.
The common mistake is attacking personal joy rather than structural overhead because small cuts feel virtuous even when they do not generate enough savings to change your debt trajectory.
Look at your actual living framework instead.
Housing, transportation, and food delivery usually account for the vast majority of cash outflow, meaning a single structural adjustment there outweighs months of denying yourself simple pleasures.
Pull up your last three bank statements and scan for the three largest recurring drains that do not actually align with your day-to-day values or bring you lasting utility.
Cancel subscriptions you forgot existed, renegotiate your internet service provider rate down by thirty dollars, and meal-plan just two nights a week to effortlessly free up four hundred dollars a month for your debt payoff.
I spent years agonizing over fifteen-dollar restaurant tabs while ignoring a car payment that was three percent higher than it needed to be.
Once you plug the big holes, the math finally starts working in your favor without requiring you to live like a monk.
Audit Breakdown — Where to Look First
🚗 Transport
Car payment & insurance
📦 Subscriptions
Unused recurring apps
🍔 Dining Out
Convenience food delivery
Focus Area
Target fixed overhead before touching your groceries.
6. Consult a Professional Counselor
Some situations require external support when the numbers outpace your income.
If your total debt exceeds half your annual salary, reach out to a nonprofit credit counseling agency to discuss a debt management plan.
They can often negotiate lower interest rates directly with your card issuers without damaging your credit score further.
DIY vs Professional Debt Relief
DIY Payoff
- Full control over your accounts
- No third-party fees
- Builds lasting cash habits
Credit Counseling
- Lower interest rates negotiated
- Single monthly payment
- Structured timeline
7. Reframe Your Financial Identity
For twenty years, you have convinced yourself that you are just fundamentally bad with numbers.
That story keeps the envelope unopened on the kitchen counter for three weeks at a time because opening it feels like stepping on a scale after the holidays.
Money management is a mechanical skill like typing or parallel parking, not a personality trait you were born without.
What I believe now: you are simply reorganizing your cash flow starting today.
Pick one account, log in for ten minutes this afternoon, and look at the actual transactions without flinching.
Mindset Shifts
8. Rebuild From My Own Balance Transfer Mistakes
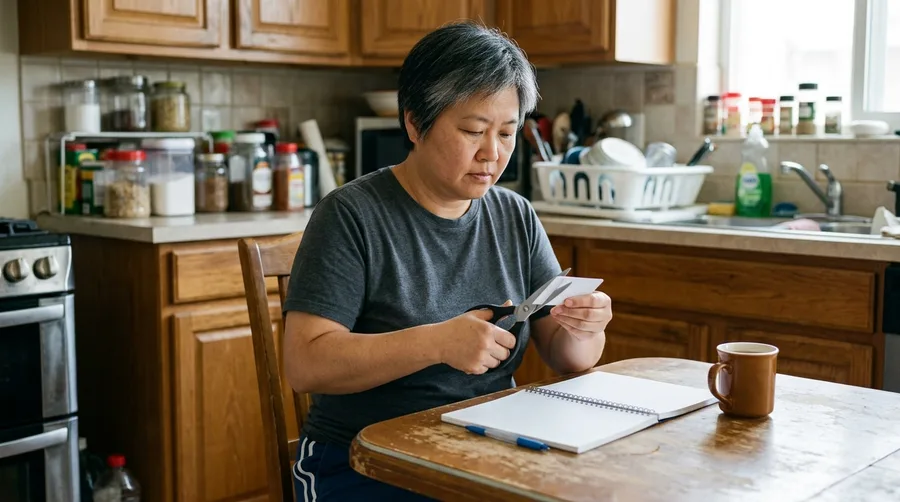
I moved ten thousand dollars to a zero-percent card and genuinely thought I had solved the entire problem.
It felt like a massive win at the time, cutting out the twenty-one percent interest rate and buying myself breathing room.
The mechanism of a balance transfer is just a relocation of stress, not a cancellation of debt, though it took me eighteen months to realize that the hard way.
Because I had not changed my underlying spending habits or closed the door on the old plastic, I ran the original card right back up within a year and a half.
Suddenly I was staring at the exact same high-interest balance plus a three percent transfer fee, and now I had two massive active payments to manage every single month instead of one.
The lesson was brutal and expensive, teaching me that a promotional transfer window is merely a pause button designed to give you a head start, not a free pass.
Once I finally cut up the source card with kitchen shears and committed to a strict, fixed twelve-month payoff schedule, the principal balance actually started shrinking for good.
The daily interest finally stopped compounding against me, and the psychological weight lifted from my chest enough to let me sleep at night.
This week: if you move your balances, close the source account immediately after the transfer clears, or do not bother doing it at all.
9. Leverage Time Windows Wisely
Everyone says debt payoff takes forever, so people delay starting.
Interest is actively working against you every single day.
That balance is not sitting still, and neither should your plan.
Aggressive payments reduce that principal faster than most calculators lead you to believe.
Starting this month instead of next year saves hundreds in interest charges over a twelve-month stretch.
Treat the timeline as a focused sprint to clear the anchor rather than a life sentence hanging over your retirement.
Open your statements today, calculate your daily interest rate, and increase your next scheduled transfer by $25.
10. Start With the Twenty-Five Dollar Floor
I kept waiting for a month with three paychecks or a sudden windfall so I could finally start my debt payoff plan with a massive $500 transfer.
Months went by and that magical month never showed up, leaving my balance sitting right where it started.
Even twenty-five dollars a month, automatically moved, does more than zero dollars you keep meaning to send.
Consistency beats perfection every single time because it builds the behavioral muscle without waiting for ideal conditions.
If your budget is tight, start with the smallest possible automated transfer to build the habit without breaking your groceries.
You can scale that number up by ten dollars each month as your cash flow stabilizes.
Set it up in your banking app today and let the habit carry the weight.
11. Accept the Trade-Offs of Aggressive Payoff
Stop pretending that paying off thousands of dollars in high-interest credit card debt over the next two or three years is going to feel fun or painless.
Cutting your discretionary spending means saying no to dinners out with friends, pausing weekend trips, and scrutinizing every single purchase that is not strictly necessary for survival.
It also means feeling restricted, tired, and occasionally resentful of the budget you have built for yourself for twelve to thirty-six months straight.
you are willingly giving up short-term comfort and lifestyle flexibility to buy back your retirement peace of mind, stopping the daily drain of 20 percent interest charges.
Is it intensely annoying? Extremely.
Is it worth trading three years of strict financial restraint for twenty years of secure retirement without credit card balances hanging over your head?
Absolutely.
The temporary trade-off is painful, but the resulting financial freedom outlasts the discomfort by decades, and this week the next action is simply listing every non-essential category you plan to temporarily trim by at least $150 to fund your aggressive payoff.
12. Review Your Progress Monthly
You are tired of opening banking apps only to feel that sick drop in your stomach because nothing ever seems to change.
Set a calendar reminder for the last Sunday of every month to check your balances, and look at two things only: total debt reduced and cash saved.
Opening that statement used to ruin my entire afternoon until I stopped tracking every single penny and focused purely on those two directional numbers moving the right way.
13. Scale Back Without Quitting
Thirty days of dropping back to minimum payments will not destroy a multi-year debt payoff plan.
Perfectionism is the quietest reason people give up on money goals entirely. When the water heater breaks or an unexpected bill eats $800, the instinct is to panic and assume the whole budget is ruined. It is not. Dropping your extra payments down to the baseline for one single month keeps you from burning out or draining your last cushion.
The mechanism here is purely behavioral: a flexible plan survives the bad months, while a rigid one shatters. Give yourself permission to pause the push, handle the crisis, and simply restart the extra transfers next month without guilt.
14. Avoid the Minimum Payment Trap
Why does that credit card balance refuse to shrink even when you faithfully make every single payment on time?
It feels like running on a treadmill because card issuers deliberately set minimum payments low, usually covering just the interest plus a tiny fraction of the principal. That means your hard-earned money goes mostly to financing charges while the actual debt stays locked in place, stretching a manageable balance across twenty years of quiet panic.
We look at that low required number on the statement and feel a small wave of relief, assuming we are winning a game that was actually rigged to keep us playing forever.
The fix does not require a complete financial overhaul or complex budgeting apps. Always add fifty dollars to whatever the statement asks for, routing that extra money straight toward crushing the underlying principal so the interest calculations finally start working in your favor instead of against you.
Open your banking app today and manually adjust that payment floor.
15. Redirect Every Cleared Balance to Retirement
Once your final credit card hits a zero balance, take that entire combined monthly payment and roll it straight into your retirement accounts.
You were already surviving without that cash flow touching your checking account, so your daily standard of living does not need to change by a single dollar.
The mechanism here is redirection rather than restriction, turning a painful monthly obligation into an automatic engine for your future security without requiring new sacrifices.
For instance, if your combined card payments totaled $450 a month, sending that exact sum to a tax-advantaged account like a traditional IRA means compounding finally works for you instead of against you.
Next month, set up that automatic transfer before you even notice the freed-up room in your budget.
Frequently Asked Questions
Is it too late to start investing at 45 if I have debt?
It is not too late, but clearing high-interest debt takes priority over new investments. Once your cards are at zero, you can use catch-up contribution limits to accelerate your retirement savings.
Should I drain my small savings to pay off credit cards?
Keep a small emergency buffer of five hundred to one thousand dollars intact so minor surprises do not force you right back onto plastic. Pay down the rest with your monthly surplus.
How much should I have in my emergency fund?
Aim for one month of bare expenses first, then build toward three to six months once your high-interest credit card balances are completely eliminated.
Should I pay off debt or save for retirement first?
Take your employer match if available, then direct all extra cash toward high-interest credit card debt because twenty percent interest beats average market returns.
Is it okay to pause my retirement contributions for a while?
Yes, pausing voluntary retirement contributions temporarily to clear high-interest debt is a sound mathematical move, provided you restart them immediately afterward.
Start With This One
Take one move from this list and set it up today.
You do not need to overhaul your entire financial life by Friday afternoon, but you do need to make the first transfer.
Your future retirement math depends entirely on what you do with the next paycheck.
