
You have heard the advice a thousand times. Just pay yourself first, drop the daily coffee, and watch the wealth roll in.
It sounds clean and effortless on paper. Then you try it on a real paycheck, rent goes up, the car alternator dies, and you are back at zero.
You are not failing because you lack discipline. You are following a sequence that assumes your life has no friction, no surprises, and no fixed bills.
The truth is simpler and harder. Paying yourself first is only step three of a ten-step ladder, and if you climb it out of order, you slip.
Here is the order that actually works when you are trying to fix your money without losing your mind.
Quick Tips Before You Start
Automate Paydays
Move savings the exact morning your check lands.
Track One Month
Write down every dollar spent before cutting anything.
Build a Floor
Aim for a small cash buffer before chasing high returns.
1. Know When to Call in a Professional
People think asking for financial help means admitting personal defeat.
It usually means you are just tired of guessing in the dark on a Tuesday night.
When your debt-to-income ratio crosses fifty percent, or tax penalties start stacking up against your paycheck, generic internet advice simply stops working.
That is the exact moment to talk to a fee-only fiduciary or a nonprofit credit counselor who looks at your actual numbers instead of a one-size-fits-all spreadsheet template.
They do not judge your past choices or lecture you about coffee, and they help you build a realistic triage plan to get your cash flow breathing again.
💡 PRO TIP
Look for Fee-Only Advisors
Always verify that any professional you hire acts as a fiduciary legally bound to put your interests ahead of their commissions.
2. Automate the Transfers That Matter
Willpower feels infinite on Sunday night, but by Tuesday afternoon it is completely gone.
If you rely on remembering to move money manually every week, you will eventually forget and spend it instead.
The mechanism here is simple removal of choice, routing a fixed amount of $150 straight to a separate savings account on the exact morning your direct deposit hits.
This takes about four minutes in your banking app to set up once, and then you never have to think about it again.
Once it runs automatically, you learn to live on what is left in the checking account without feeling like you are constantly making sacrifices.
Automation beats discipline every single time.
The Old Way vs. The Order That Works
The Generic Way
- Try to save everything at once
- Rely entirely on daily willpower
- Track every single coffee purchase
- Feel guilty when a surprise hits
The Order That Works
- Build a small buffer first
- Automate transfers on payday
- Focus on cash flow timing
- Accept trade-offs without shame
3. Stop Waiting for the Perfect Time
I spent three solid years telling myself I would finally start saving the month my salary hit $55,000, as if an invisible threshold existed where discipline suddenly became optional.
Waiting for a better income is a trap because lifestyle creep and inflation will simply swallow the raise before it ever hits your savings account.
Time in the market and building the habit matter far more than the starting figure, so move $25 into a separate account this month instead of waiting for next year.
Quick Reference — Starting Out
4. Avoid the Minimum Payment Trap
It is easy to feel a temporary sense of relief when you click submit on that tiny minimum payment, as if you successfully dodged a bullet for another thirty days. You are not irresponsible for doing it when cash is tight, but that quiet relief hides a punishing mathematical trap.
With average credit card APRs sitting around 20-21% according to Federal Reserve data, paying only the minimum means the vast majority of your hard-earned cash vanishes into interest charges rather than shrinking the actual debt. The balance stays stubbornly stuck while the treadmill just keeps spinning.
Take a breath, look at the highest interest rate on your statements today, and throw every extra ten dollars you can scrape together at that specific balance first, even if it feels painful to part with the cash.
The Debt Reality
5. Start with Twenty Five Dollars
Start with twenty-five dollars a month transferred automatically into a separate account you cannot easily touch with your debit card.
Most financial guides tell you to stash away ten thousand dollars immediately, but if you do not have that kind of cash, reading those guides just makes you close the tab in frustration.
It feels insignificant at first.
The mechanism here is purely behavioural rather than mathematical.
By lowering the barrier to entry so far that it requires zero sacrifice from your current grocery budget, you remove the friction of decision fatigue.
Consistency beats grand gestures every single day of the week.
Six months later, you look at the balance and realize you actually saved money for the first time in your adult life without radically altering your lifestyle.
I kept my first small automatic transfer at twenty dollars because twenty felt safe enough that I would not cancel it when the electric bill spiked.
Build the muscle before you worry about the weight.
Log into your banking app right now, set up a recurring transfer for twenty-five dollars on your next payday, and let the habit form itself.
🌱 GROWING TIP
Make Saving Invisible
Keep your savings account at a completely different bank than your checking account so you are not tempted to transfer funds back for weekend takeout.
6. Can You Really Build Wealth Now?
Are you convinced that investing is only for people who started a decade ago?
That belief keeps your cash sitting in a checking account losing value to inflation every single month, quietly shrinking your purchasing power by roughly 2 to 3 percent a year without you ever writing a check.
What I believe now: stop worrying about catching a missed decade and focus entirely on building your own financial floor with $50 a week into a broad market index fund, because starting today beats waiting for a time machine.
The Stability Hierarchy
From immediate survival to long-term growth
7. The Real Cost of Automated Saving
Cancel the subscriptions you forgot about and clean out your digital recurring charges this afternoon.
Cutting your spending stack back saves forty dollars a month.
It also means actually cancelling things, which takes an annoying afternoon and a frustrating amount of clicking through retention screens.
automation takes away your daily financial decisions, but it also means you cannot manually adjust when cash gets tight.
Build a three-hundred-dollar buffer in your checking account so automated pulls never trigger a thirty-five-dollar overdraft fee.
The friction is worth it once the system runs smoothly and the background transfers just happen.
8. How I Finally Fixed My Broken Budget
Three weeks is how long my color-coded, meticulously formatted budget survived before I abandoned it out of pure spite.
I spent years tracking every single penny like an exhausted accountant trying to audit a failing business, but the system kept collapsing because it treated my life like a math equation.
The turning point came when I finally stopped obsessing over a four-dollar coffee and started looking at cash flow timing instead.
The mechanism of a broken budget is almost never about willpower or discipline, but rather about the mismatch between when your bills hit and when your paycheck actually clears.
During a particularly rough patch, I had to pour one thousand dollars a month straight into mandatory survival expenses just to keep the lights on and the pantry stocked.
That wasn't in the original plan, and facing that reality is precisely why I had to tear the old budget down and rebuild it completely from scratch.
You do not need a flawless ledger to get your money together, and you certainly do not need to punish yourself for being human.
You just need a system that can survive a messy, unpredictable Tuesday without completely falling apart.
This week: open your bank app, look at your two largest upcoming bills, and call your provider to move their due dates directly to the day after you get paid.
Cash Flow Distribution
Federal Reserve SHED framework estimates for household stability
9. Set Up Your First Emergency Buffer
You do not need six months of savings right now, and worrying about it is probably why you keep putting this off.
Aim for five hundred dollars before you touch your retirement accounts or worry about extra debt payments. That number covers the minor disasters like a flat tire or an urgent copay that usually derail a tight week and force you onto a high-interest credit card.
Get there by Friday using whatever spare cash you can scrape together from selling something old or pausing a delivery app. Open a separate savings account today, transfer the money immediately, and let yourself finally breathe.
10. Build a Simple Three-Bucket System
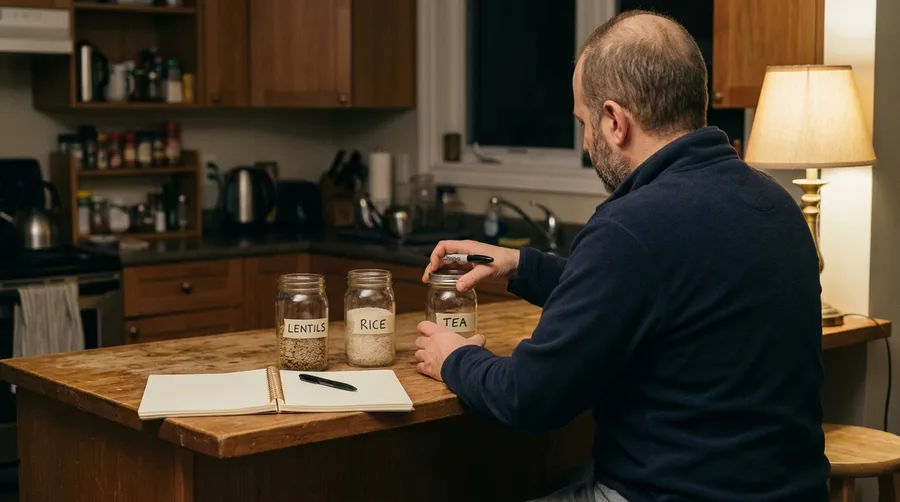
Managing all of your household money in one giant checking account is a fast track to constant stress and accidental overspending.
Split your incoming paycheck into three distinct categories the exact moment it clears: fixed bills, debt minimums, and flexible spending. For most households, setting up separate sub-accounts or using separate banks makes this physical separation real rather than just a mental note you completely forget by Tuesday.
When I first tried this system years ago, I realized half my income was bleeding out on forgotten $10 subscriptions because everything was lumped into one confusing pile where I could never see the real numbers.
Bucket one holds rent and utilities, bucket two covers your scheduled debt auto-pays, and bucket three is whatever cash is left over for groceries and gas. The trade-off is that sorting this out takes about twenty annoying minutes of initial app configuration, but it stops the guessing game completely.
Log into your banking app today and open a second account designated strictly for your fixed bills.
11. Give Yourself Permission to Do Less
Forty hours a week spent staring at spreadsheets while your chest feels tight is not the entry fee for getting your money together.
Most people crash out of financial planning not because they lacked discipline, but because they tried to change fourteen different habits across forty-eight hours.
Cutting the grocery budget, maxing out a retirement account, tracking every single penny, and throwing extra cash at debt simultaneously creates a burnout loop that guarantees you will quit by the third week.
The mechanism here is psychological capacity rather than math: willpower is a finite daily resource, and treating your paycheck like an emergency military campaign only makes the couch look like a sanctuary.
Lowering the bar is not giving up; it is building a system durable enough to survive a stressful Tuesday without imploding.
I tried to overhaul everything in January of 2019, lasted nineteen days, and bought takeout out of sheer exhaustion that erased half my savings progress.
Pick one single move from this entire list, set a timer for fifteen minutes, and let the other fourteen wait until next month.
If all you manage to do during this pay period is open a separate savings account and drop twenty-five dollars into it automatically, you have won.
This week, give yourself the literal permission to do less, because slow consistency will always beat a three-day sprint that leaves you broke and bitter.
12. Review Your Numbers Once a Month
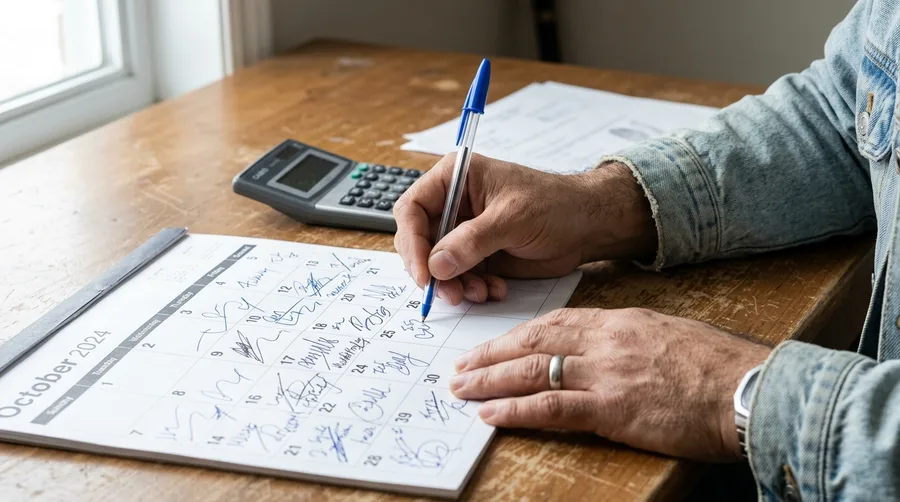
Looking at your bank statement always feels like opening an envelope you are pretty sure holds bad news.
That dread is why most people abandon budgeting entirely after three weeks, letting months slide by without checking a single balance. A monthly review stops the drift before it turns into a real crisis.
Set a recurring calendar reminder for the last Sunday of every month so you never have to guess when it is time. Look at three things only: your total savings growth, any upcoming big expenses for the next thirty days, and recurring subscriptions you forgot you were paying for. Keeping the scope narrow stops your brain from finding an excuse to shut down.
Keep the whole process under twenty minutes by setting a timer on your phone. It needs to feel like a routine check in rather than an aggressive tax audit, or you will simply avoid doing it next time.
Open your calendar right now and drop that Sunday reminder in before you close this tab.
13. Stop Buying Financial Hype Online
Every video telling you there is a secret trick to overnight wealth is selling a course.
Ignore the noise and stick to boring, consistent mechanics.
14. Check Your Progress Every Quarter
I used to look at my bank account only when something declined, which usually meant finding out my rent check cleared before my paycheck did.
Life shifts every ninety days, and your money plan needs to move right along with it. Sticking to an automatic transfer from three years ago does not make you disciplined if your rent went up by $150 or your grocery bill doubled. The quarterly review is not about grading yourself; it is about keeping your numbers honest as your actual life changes.
Take fifteen minutes at the change of each season to open your dashboard and check just two things: what your automatic savings rate is versus what you actually spent.
15. The Real Trade Off of Saving Early
Are you actually willing to give up small luxuries today for peace of mind tomorrow, or are you just trying to do what everyone else tells you to do on the internet?
That is the fundamental trade-off of personal finance, and nobody likes to talk about the part where you actually have to say no to things you enjoy.
The mechanism is straightforward compound growth, but the human cost is that every $50 you lock away this month is $50 you cannot spend on dinner out or a weekend trip.
It is not about living like a monk or cutting out every joy in your life, but about choosing what actually brings you lasting value versus what drains your paycheck on autopilot.
This week, look at one recurring expense over $30 and decide if keeping it is worth delaying your cushion by another month.
Frequently Asked Questions
Is it too late to start investing at 40?
It is never too late to start building consistency. While starting early helps, putting away small amounts consistently in low-cost index funds still builds a meaningful cushion over twenty years.
How much should I have in my emergency fund?
Aim for one month of bare expenses first—somewhere between two and three thousand dollars for many households—then gradually work your way toward three to six months as your cash flow allows.
Should I pay off debt or save first?
Build a small five-hundred-dollar cash buffer first so minor car repairs do not become new credit card debt, then attack high-interest debt aggressively while keeping automated savings running.
Is it okay to pause my retirement contributions for a while?
Life happens, and sometimes income drops or expenses spike. Pausing temporarily to handle an emergency or a job transition is completely normal; just set a calendar reminder to restart them.
Your Next Step
Take one move from this list—just one—and set it up before you close this tab.
You do not need to fix your entire financial life today. You just need to start the engine.
