
Mixing your money with someone else feels like stepping onto a moving train without looking at the tracks.
You might be staring at a pile of unpaid statements on the kitchen counter while your stomach does small, uncomfortable flips. It is easy to assume everyone else figured this out years ago, but nobody talks about the actual logistics of combining paychecks.
This is fixable, and you do not have to guess your way through it.
I rebuilt my own approach to shared expenses after two complete financial disasters, and I learned that the math is actually the easy part. The hardest part is learning how to talk about cash without anyone feeling judged or cornered.
You do not need to answer all fifteen questions by Friday, and you certainly do not need to merge everything at once. Take what works, leave what does not, and move at a pace that keeps your anxiety from running the show.
Quick Tips Before You Start
Keep It Casual
Talk about money over coffee, not across an open laptop at midnight.
Write It Down
Keep a shared note on your phone for numbers and targets as you agree on them.
Take Your Time
Plan for three separate conversations rather than trying to solve everything in one afternoon.
1. Mapping Out Your Individual Debts
Put every balance, every interest rate-like a 21 percent credit card-and every minimum monthly payment onto one shared screen today.
Debt is usually the heaviest baggage either person brings to the table, and pretending it does not exist only makes the anxiety louder. It is terrifying to show someone else your statement for the first time, but doing it stops the guessing game and gives you actual control over cash flow.
If your numbers feel completely tangled and impossible to sort out alone, reach out to a fee-only fiduciary or a nonprofit credit counselor for guidance.
Debt Terms to Know
2. Setting a Hard Timeline for Merging
It is completely normal to feel that rushing into a joint account is the ultimate test of commitment, but moving too fast usually creates avoidable friction.
If you merge your paychecks before you have tested your communication, everyday purchases turn into high-stakes arguments.
Give yourselves a clear six-month trial window where you keep separate checking accounts active while practicing a joint budget.
Starting this month gives you enough runway to spot $50 grocery discrepancies or subscription disagreements before any permanent legal steps happen.
🌱 GROWING TIP
Build a Testing Phase
Run a trial month where you each contribute a fixed amount to a shared bill account while keeping your personal spending entirely separate.
3. Building a Three-Bucket Cash Flow System
I spent the first two years of living with my partner watching our money bleed out in tiny, invisible cuts because every dollar sat in one big checking account and somehow felt available for whatever emergency or whim crossed our path.
Without a physical or digital boundary, rent money routinely funded takeout burgers, and we spent half our evenings arguing about who actually bought the groceries last week.
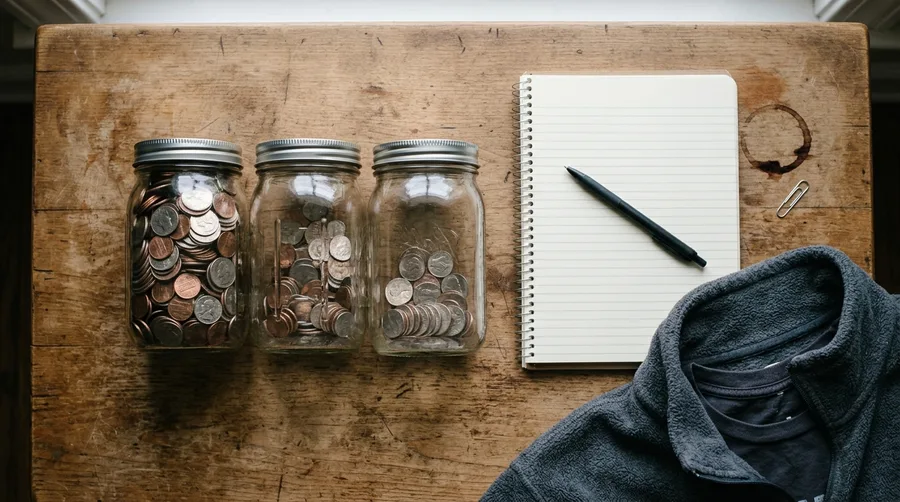
We finally fixed it by moving to a three-bucket cash flow structure that separates fixed bills, debt minimums, and flexible spending into distinct silos so nothing gets double-spent.
The mechanism is straightforward: your paychecks land in a central holding account, and automated transfers immediately siphon money into the bill bucket and the debt bucket before you even see the balance.
Whatever is left over goes straight into the flexible spending bucket for food and fun.
If an unexpected expense hits and your cash runs short, fund buckets one and two fully and let bucket three take the hit.
This system stops lifestyle creep dead in its tracks because your fixed obligations are spoken for automatically every single month.
Spend forty minutes this weekend logging into your banking app and setting up those recurring transfers so you never have to think about them again.
Three Buckets — The Numbers Behind It
🏠 Bucket 1 Target
One month of fixed bills, held one paycheck ahead
📊 Bucket 2 Target
Every minimum, automated two days after payday
🛍️ Bucket 3 Rule
Withdrawn weekly, never daily, to cap lifestyle creep
Skip If
Your pay lands more than twice a month — use a weekly split instead.
4. Establishing a Regular Money Review
Set a monthly date to look at your numbers together without any distractions.
Most couples wait until a bill bounces or an unexpected expense blows up the account before they talk about money, which turns every conversation into a crisis response. When you review things every thirty days, you catch small leaks before they turn into major damage. You are not doing this to police each other or track every penny down to the last cent. You are doing it so that fifty dollars of accidental overspending stays a minor adjustment instead of a surprise deficit.
You want to review three specific things during these check-ins: how much income actually landed in the accounts, where it went during the previous month, and whether your upcoming month looks heavier than usual with birthdays, insurance renewals, or car maintenance. Keep these sessions short, capping them at thirty minutes maximum with coffee or tea, so they do not turn into heavy interrogation sessions where nobody feels safe speaking honestly.
I used to dread these talks because I treated them like performance reviews, which meant we both got defensive about our spending choices. Once we shifted to treating it like a standard household maintenance check, like changing the air filter in the HVAC system, the anxiety dropped away entirely. Consistency beats perfection every single time when you are building a shared life.
This week: put a thirty-minute calendar reminder on your phone for your first review night.
🗺️ Your 30-Day Merged Money Roadmap
Week One
List all individual debts and balances on one shared note.
Week Two
Set up a trial joint account for fixed bills only.
Week Three
Establish your spending threshold and personal allowances.
Week Four
Run your first thirty-minute monthly review together.
5. Creating Personal Permission Slips
About 30% of couples maintain a hybrid model where joint bills are covered proportionally, but individual fun money stays completely separate.
You do not need to merge every single dollar you earn to have a successful partnership, despite what standard advice often implies.
This gives both of you breathing room to buy things without feeling like you need to justify a $40 purchase to your partner.
Scale back whatever feels too restrictive right now so you can protect your peace of mind.
Take 10 minutes tonight to decide on a fixed personal allowance for both of you this month.
Best For
Willpower is a terrible budgeting strategy when you are tired on a Tuesday evening.
Most people believe they just need to try harder to save, but relying on discipline alone is why accounts stay empty.
The fix is removing the choice entirely by setting your shared rent and utility transfers to run for the morning after payday so the money disappears before you can spend it on convenience.
This timing fix changes your success rate overnight because the math happens automatically while you are asleep.
Take twenty minutes this week to log into your online banking, schedule $1,200 or whatever your baseline shared number is to move on the first of the month, and then leave it completely alone.
Merging Styles Compared
The Full Merge
- One central checking account for all income
- Simpler monthly tracking and bookkeeping
- Requires high levels of communication trust
- Best for long-term married households
The Hybrid Split
- Proportional contributions to joint bills
- Independent personal spending accounts
- Great for newly combined households
- Preserves individual financial autonomy
7. Handling Spending Disagreements Calmly
How do you handle it when one person spends $150 on hobbies while the other saves every spare dollar?
People often assume this is an immediate sign of financial incompatibility, but it is usually just a normal clash of priorities and habits.
The fix is establishing a clear spending threshold of $75, above which any purchase requires a quick text heads-up, while anything below it is fair game for personal use.
This keeps mutual trust intact without breeding silent resentment over individual autonomy or financial control.
This week: sit down together and agree on a specific dollar limit for unannounced purchases that respects both partners' peace of mind.
⚠️ COMMON MISTAKE
The Permission Threshold Trap
Never set the discussion threshold too low, or you will end up micromanaging every single grocery trip and coffee run.
8. Reflecting on Past Money Mistakes
Carrying secret money shame into a partnership feels like walking around with a heavy winter coat in the middle of July.
You spend so much energy trying to hide the old financial mistakes that you miss the actual chance to build something steady together.
When I was twenty-four, I put $4,000 of emergency expenses on a credit card with a 24% APR because I had zero cushion in my checking account.
That mistake cost me nearly two years of painful interest payments and taught me how fast a bad Tuesday turns into a long-term anchor.
The mechanism behind that debt trap is relentless: daily compounding interest quietly eats away at every dollar you earn, making it feel like you are running on a treadmill just to stay in the same place.
When you sit down with your partner to talk about combining lives, share your financial trainwrecks out loud instead of keeping them locked away in your head.
Admitting where you messed up strips the shame right out of the room and completely changes the dynamic from judgment to actual teamwork.
Your partner needs to know what past debt or financial trauma you are carrying so they can understand why certain purchases or unexpected bills make you deeply nervous.
This week, pick one evening to talk about your worst financial memory before you ever look at a joint spreadsheet together.
9. Starting With Small Emergency Funds
$500 changes the math on a bad Tuesday.
Most people stall out on emergency savings because they think the first milestone has to be three months of living expenses. It does not. A starter buffer of $500 absorbs flat tires and minor medical bills without forcing you to lean on a credit card at twenty percent interest. Consistency beats big lump sums every single time.
Set an automatic transfer for $25 every payday into a separate account at a completely different bank. The exact amount matters much less than the habit of letting it build without your permission.
10. Weighing the Trade-Offs of Joint Accounts
Everyone says that true partnership means throwing every dollar into one single pool right away.
That is a fast track to resentment when you realize you just traded your financial independence for a shared password.
Merging accounts gives you administrative simplicity, but it costs you privacy.
Buying a birthday gift or spending $40 on a solo lunch suddenly requires a conversation you didn't ask for.
Decide if that lost autonomy is actually worth the ease before you close your individual accounts for good.
This week, keep two separate accounts open while you trial a joint third account for household bills only.
11. Overcoming Scarcity Mindsets Together
Do you view money as a scarce resource that will disappear at any second?
Sound familiar? That anxiety usually comes from watching parents stress over bills during your childhood, absorbing every tense kitchen table whisper about whether the paycheck would stretch until Friday.
The mechanism behind this is entirely behavioral, because survival mode wires our brains to treat every unexpected expense like a direct threat to our safety.
What I believe now: money is a tool for building options, not a scoreboard for your worth, and shifting that perspective takes intentional, daily practice.
Take fifteen minutes this weekend to write down your earliest money memory and share it with your partner over coffee so you can understand where your reactions come from.
When we first tried to save for a trip together, we just threw whatever was left at the end of the month into a joint savings account, which meant we saved almost nothing.
Vague goals give your money permission to disappear into takeout and random errands.
Pick one specific target to fund together over the next six months, attaching a hard dollar amount and a strict deadline to it.
Aim for something concrete like $2,000 for a car repair buffer or $1,500 for a holiday, because a defined target turns a wish into a concrete milestone.
Transfer $150 every two weeks automatically on payday, and check your progress together at the end of every single month.
We use a digital envelope structure to keep flexible spending categories completely separate from our bills.
Without strict boundaries, grocery money tends to bleed into dining-out money by week three. That silent drift is usually what makes you feel like your budget is broken when the system itself is just leaky.
The mechanism relies on sub-accounts within your main banking app: allocate specific dollar amounts for groceries, fuel, and entertainment the moment your pay lands. Instead of trusting a running mental tally, you assign every single dollar a specific job before the month even has a chance to pull it in different directions.
When an envelope hits zero, spending in that category stops until the next pay cycle. That hard wall feels uncomfortable at first, but it eliminates the grey areas that lead to quiet arguments about where the grocery money went.
If you overspend on dining out, you pull the difference from your own personal fun money, never from rent. That rule protects the shared foundation from individual slip-ups.
This system stops the guessing game at checkout because you already know what is available.
Set up three sub-accounts in your banking app this afternoon and assign your weekly limits.
14. Avoiding Common Financial Blame Traps
You feel that heavy, familiar knot in your chest when an unexpected account alert pops up, instantly hunting for someone to pin it on.
It is completely exhausting when a shared card dips below zero and the argument instantly spirals into weaponizing a $75 dinner from three months ago. That backward-looking blame trap destroys trust faster than any math error because it triggers an immediate defensive loop. Instead of fixing the leak, you are both just keeping score.
Stop looking backward this week and focus entirely on the next system adjustment together.
15. Reflecting on Your Financial Partnership
It is normal to worry that your past money habits make you unworthy of a shared future, but financial partnership is about direction, not perfection.
I spent years hiding credit card receipts because I thought perfection was the only way to earn trust, constantly terrified of a $45 balance check finding me out. Turns out, total transparency is much more effective than looking flawless on paper.
Take a deep breath and start with just one honest question tonight.
Frequently Asked Questions
Should we combine our bank accounts immediately?
Most couples benefit from a testing phase of three to six months where you share bill accounts while keeping personal spending separate. This lets you iron out communication habits before making permanent financial changes.
What if one of us earns significantly more than the other?
Proportional contributions work well for unequal incomes. Instead of splitting bills fifty-fifty, each person contributes a percentage that matches their share of the total household income.
Bring up past mistakes without judgment during a calm weekend conversation. Transparency builds trust faster than perfection, and knowing what debt exists prevents surprises later.
How much should we keep in our starter emergency fund?
Aim for a $500 starter buffer to cover minor household surprises before you tackle larger savings goals or aggressive debt payoff.
When should we talk to a financial professional?
If you are dealing with complex tax situations, significant debt that causes constant friction, or retirement planning across multiple accounts, consider consulting a fee-only fiduciary.
Start With This One
If you take one move from this list, open a shared note on your phone tonight and write down your total debt numbers together.
You do not have to solve everything by Friday, and you certainly do not need to merge your entire financial life this weekend. Take a deep breath, keep the conversation honest, and move at a pace that keeps your anxiety from running the show.
