
Most kids learn about money by watching how adults handle panic at the grocery checkout or quiet stress over unopened mail on the kitchen counter.
You do not need a trust fund or a finance degree to shift how your household talks about cash. It starts with simple, repeatable conversations around the dinner table.
Here are eight practical money rules that teach kids the mechanics of building a secure, choice-filled life before they hit their teens.
Quick Tips Before You Start
Use Physical Cash First
Tangible bills make spending real in a way digital screens never quite manage.
Write It Down
Keep a simple paper log of every allowance dollar earned and spent.
Focus on Habits
Consistency matters far more than the exact dollar amount in the jar.
Talk Out Loud
Name trade-offs during everyday errands so kids hear real decision-making.
1. The Three-Jar Cash Split System
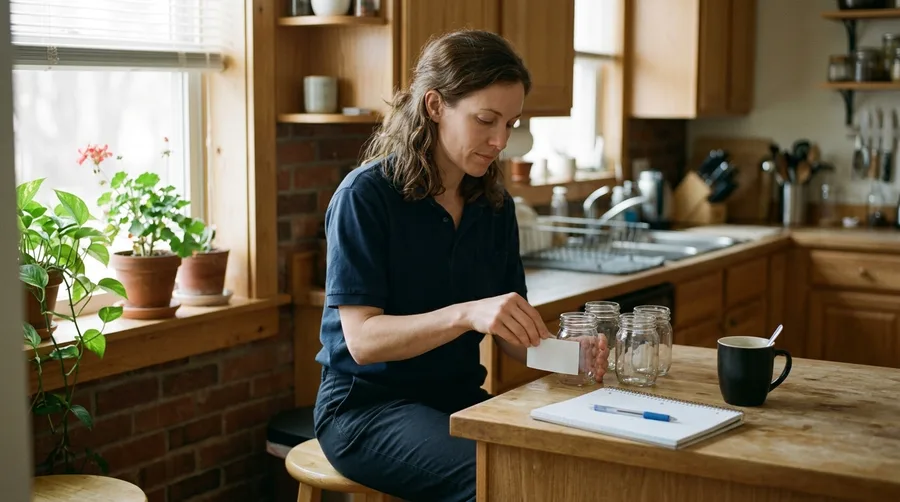
Divide every incoming dollar into three clear categories immediately.
ten percent goes straight to giving, twenty percent goes into long term savings, and the remaining seventy percent is yours to spend on whatever you want.
The mechanism is about prioritization before consumption.
When money arrives pre sorted, impulse buys drop naturally because the spending bucket has a hard boundary.
If an allowance is ten dollars, seven go to spending, two to savings, and one to charity.
It feels small at twelve years old, but the muscle memory carries directly into adult paychecks.
I tried this with my own teenager last year and watched the constant pleading for extra cash drop off within a single month simply because they could see the boundaries of what was left.
The trade off is that it requires discipline on your part to actually enforce the split every single time money enters the house.
Set up the jars this weekend with your child and let them label the fronts with permanent marker.
At a Glance
2. Delaying Gratification Through The Waiting Rule
Wait forty-eight hours before buying anything that costs more than a week of allowance or discretionary pocket money.
Impulse purchasing is an easy trap when digital payments make spending invisible and frictionless.
Forcing a pause breaks the emotional loop between seeing an item and handing over cash, giving your rational brain a chance to catch up with the initial spike of excitement.
If you still want the item after two full days, you can pull from your spending jar without guilt.
Most of the time, the urge fades completely by tomorrow morning.
This week: pick one online cart you have been staring at, close the tab, and set a literal forty-eight hour timer before you even look at it again.
Financial Jargon Decoded
3. Learning From My Own Expensive Mistakes
I bought a forty-dollar video game accessory when I was a teenager that I used precisely twice before it ended up permanently buried at the bottom of a desk drawer.
It felt like the most important purchase in the world on a Tuesday afternoon, and it felt like absolute garbage by Thursday night.
Sharing missteps like that takes the heavy, paralyzing shame right out of money talk and proves to kids that adults are still trying to figure it out too.
When a kid hears about your fifty-dollar regret and the lingering sting that came with it, they finally realize that financial literacy does not come pre-installed.
It comes strictly from trial, error, and talking openly about what you would do completely differently if you had that exact twenty-minute window back.
💡 PRO TIP
Keep Conversations Low Pressure
Never tie financial mistakes to character. Treat a bad purchase as data collection, not a moral failure.
4. Knowing When to Get Professional Advice
You do not have to figure out every tax rule by yourself.
Hitting a wall with complex finances does not mean you have failed. Bringing in a fee-only fiduciary or a certified tax accountant is a smart power move, not an admission of defeat. For roughly $150 to $300 an hour, an expert can spot blind spots that protect your hard-earned cash. I spent three years guessing at my retirement allocations before a planner untangled them in forty-five minutes.
This week, search for a local fee-only professional if your accounts are getting too tangled to manage alone.
Professional Help — At a Glance
👤 Who to Call
Fee-Only Fiduciary
📋 When Needed
Taxes and Investing
⭐ Main Benefit
Unbiased Guidance
The Rule
Always verify credentials before sharing personal financial data.
5. Conducting Monthly Family Budget Reviews
When do you actually look back at the numbers without wanting to close the tab and pretend everything is fine?
Once every four weeks, set aside ten minutes to look at three specific things: where the grocery money actually leaked, how much the savings jar grew by, and what needs adjusting for the next round. You are not doing this to punish yourself for an accidental $80 restaurant trip. You are doing it because visibility builds quiet confidence. I used to dread opening my accounts until I turned it into a low-stakes monthly check-in over a cup of coffee.
This weekend, block out ten minutes and run the check.
The Money Priority Pyramid
From foundation to long-term growth
6. Avoiding Common Lifestyle Inflation Traps
Most people spend every extra dollar they earn as soon as a raise hits their bank account.
Here is the mechanism: when income climbs from $3,000 to $4,000 a month, rent and car payments immediately rise to match, leaving zero net gain in actual wealth.
Teach kids to keep their baseline expenses flat even when their income grows.
The extra money goes straight into investments or savings instead of upgrading the car or buying designer sneakers just to keep up appearances.
This is how families build true financial independence over decades rather than living paycheck to paycheck.
The trade-off is feeling out of step with peers who lease expensive cars, but the payoff is absolute peace of mind when unexpected life events happen.
⚠️ COMMON MISTAKE
The Lifestyle Inflation Trap
Upgrading your lifestyle with every small pay bump keeps you trapped on the working treadmill indefinitely.
7. Giving Yourself Permission to Scale Back
The unspoken rule in personal finance is that if you are not maxing out every account every single month, you are failing.
Drop that belief right now.
If a tight month hits and your budget is entirely squeezed, you do not need to pause your progress entirely or throw your hands up.
Drop the automatic transfer down to $5 and keep the habit alive instead.
Consistency beats perfection every single time.
This week, set a minimum floor of $5 for your savings so a lean month never breaks your momentum.
Quick Money Facts
8. Weighing the True Cost of Debt
Twenty-one percent interest rates turn a small purchase into a multi-year anchor before you even notice.
Borrowing money feels like free cash today, but it steals directly from your future self.
If you put $500 on a credit card and pay only the bare minimum each month, that item ends up doubling in cost over three years.
The mechanism is punishing: compounding interest works against you instead of for you.
Teach kids to calculate the real hours worked required to pay off a non-essential purchase.
When a $100 video game translates to six hours of actual labor, the math changes instantly.
The trade-off is painful because it means saying no to instant gratification right now.
You gain total control over your monthly cash flow instead of letting a plastic card dictate your options.
This week, pick one existing balance and calculate exactly how many hours of work it actually cost you to buy.
Frequently Asked Questions
What age should you start teaching kids about money?
You can start as early as age four with basic coin sorting and piggy banks. By age twelve, kids are ready to manage a small allowance and understand percentage splits.
Should allowance be tied to household chores?
It depends on your family values. Many parents separate basic household contributions from paid extra chores so kids learn both civic duty and earned income.
How much allowance is appropriate for a twelve-year-old?
A common guideline is one dollar per year of age per week, adjusted for what expenses the child is expected to cover themselves, such as snacks or entertainment.
Is it okay if my child blows their spending money immediately?
Yes, absolutely. Letting them experience the regret of spending their entire allowance on a cheap toy is one of the most effective financial lessons they will ever receive.
Where to Go From Here
Teaching kids about money is not about raising Wall Street traders or financial perfectionists. It is about giving them the confidence to make conscious choices on their own terms.
Pick one habit from this list to test this week, and let the rest wait for next month.
