
A yield is exactly the same regardless of which asset pays it.
That assumption breaks down entirely the second you file your taxes.
A $100,000 portfolio yielding 6.5 percent produces a reliable $6,500 cash stream every year, but the expected tax bill rarely matches the actual filing. Real estate trusts do not receive the standard flat rate given to qualified stock dividends.
Instead, those payouts splinter into multiple categories that require matching the specific asset to the correct holding account. Here is a breakdown of the three tax categories, the surprises hidden in tax forms, and the specific accounts that shield those payouts.
| Distribution or Account Type | Tax Treatment | Tax Filing Impact | Best Account Strategy |
|---|---|---|---|
| Ordinary REIT Dividend | Taxed at standard marginal brackets | Box 1a on Form 1099-DIV | Tax-deferred or Roth accounts |
| Return of Capital | Tax-deferred until sale | Lowers original cost basis | Taxable brokerage accounts |
| Roth IRA Placement | Completely tax-free growth | No annual reporting required | Ideal for long-term holders |
REIT Payouts Are Ordinary Income Not Qualified Dividends
Real estate investment trusts skip the corporate tax line entirely, which leaves the tax bill sitting directly on your personal return.
To maintain that special corporate tax-free status, the IRS forces a trust to hand over at least 90% of its taxable income to shareholders. Because the company never paid taxes on that money before distributing it, you pay your standard individual income tax rate on it instead of the much lower qualified dividend rate.
The math hits hard at tax time.
On a $100,000 portfolio throwing off a $6,500 annual cash yield, typically 70% of that money registers as ordinary income. That drops $4,550 straight onto your top marginal tax tier, subjecting that cash to the exact same heavy taxation as your regular salary.
If you hold these assets in a regular brokerage account, that higher rate eats into the yield you originally bought the asset for.
You have to pull up the official IRS marginal rate guidelines to calculate exactly how much of that yield actually stays in your pocket.
The Tax Hit on a $6,500 Payout
Assumes a 24% marginal tax bracket in a taxable account.
Section 199A Tax Deductions Offset Part of the Tax Drag
That heavy ordinary tax rate on your payout gets softened by a specific tax code provision designed to reward qualified business income.
Investors holding real estate trusts in a standard taxable brokerage account can frequently deduct up to 20% of their qualified dividends before doing any math. This tax break, created under Section 199A of the tax code, applies straight to the ordinary income portion of your payout to lower your overall burden.
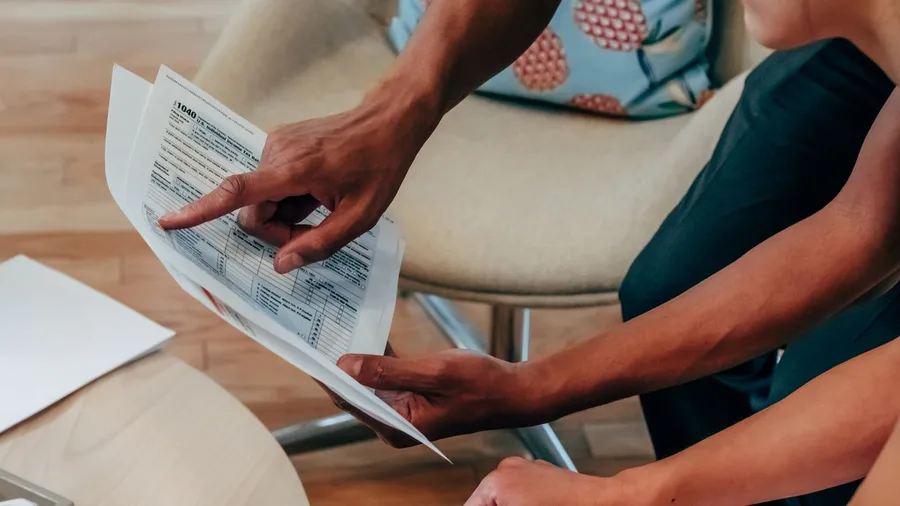
Look directly at Box 5 on your IRS Form 1099-DIV.
Taking that $4,550 ordinary income slice from our $6,500 annual payout example, applying the full 20% deduction shields $910 from taxes entirely this year. This creates a noticeable reduction in your net effective tax rate, helping defend the asset's cash yield against the government.
You do have to run the numbers against your own salary first, because specific income thresholds determine exactly who qualifies to claim this deduction.
Taxpayers earning above those statutory limits often see the taxable account benefit phase out completely, requiring careful planning before filing.
💡 PRO TIP
Check Your Income Thresholds
The 20% Section 199A deduction begins to phase out for high earners. Always verify the current IRS phase-out limits against your adjusted gross income before assuming you get the full deduction.
Return of Capital Lowers Your Cost Basis Instead of Income
While that specific deduction shields a portion of the ordinary money, another distinct slice of the trust's distribution avoids immediate taxation completely.
A trust often classifies a segment of your payout as a return of capital, which defers taxes today but increases your capital gains liability later. On a $6,500 total payout, a typical 15% return of capital allocation means $975 hits your account with zero tax due in the current year.
The IRS does not forget about the money.
Instead of taxing that $975 now, the government reduces your original $100,000 share purchase basis down to exactly $99,025. That lowered basis automatically triggers higher capital gains taxes when you eventually sell the shares, because the taxable gap between your buy price and sell price just widened.
You have to track these cumulative cost basis reductions precisely across multiple tax years to prevent expensive reporting errors upon sale.
If you lose the paperwork and claim your original purchase price later, you will file a faulty return and face a potential audit.
Decoding Your Dividend Statement
Capital Gain Distributions Carry Unexpected Capital Gains Rates
The final slice of a standard payout comes from the trust itself selling physical commercial properties for a profit, passing those long-term capital gains down to the shareholders. This event remains entirely separate from the personal capital gains generated when an investor eventually sells their own REIT shares on the open market.
Those long-term rates sit noticeably lower than ordinary income brackets.
On a standard $6,500 annual distribution from a $100,000 portfolio, a typical 15% capital gain allocation means exactly $975 gets this preferred tax treatment. That specific $975 slice avoids the heavy tax drag applied to the ordinary income portion, keeping significantly more of the cash yield intact for the year.
Tracking down this number requires looking directly at Box 2a on IRS Form 1099-DIV, which separates these specific property sales from standard dividend distributions.
Filing the entire payout as standard income means overpaying the government on a tax break the real estate structure specifically passed down to lower the tax bill. Taking the time to check protects the margin.
Mapping Form 1099-DIV
🏢 Box 1a
Ordinary Dividends
📉 Box 2a
Total Capital Gains
🛡️ Box 5
Section 199A Dividends
The Rule
Never assume the whole payout belongs on one line of your tax return.
While ordinary income classifications complicate taxable accounts, shifting real estate into retirement accounts introduces a completely different hazard. Certain private or debt-financed real estate structures held inside an IRA can generate Unrelated Business Taxable Income, commonly called UBTI. This creates a rare scenario where taxes hit a supposedly tax-free Roth IRA.
Publicly traded equity REITs bypass this trap entirely.
The danger lies directly in debt-financed private real estate funds, which use borrowed money to acquire property. When UBTI from these specific private structures crosses a strict $1,000 statutory threshold in a single tax year, federal rules force the IRA custodian to file IRS Form 990-T to report the business income.
The resulting tax bill is not paid from a standard checking account. The liability gets debited directly from the retirement balance itself, quietly eroding the tax-free principal. A $100,000 portfolio placed in private real estate can leak cash directly to the government, defeating the purpose of the Roth structure.
Stick to publicly traded shares to protect the shield.
⚠️ COMMON MISTAKE
Leverage Inside IRAs
Buying private, debt-financed real estate syndications inside a self-directed IRA frequently triggers UBTI. Stick to publicly traded equity REITs for your retirement accounts to avoid surprise tax debits.
Foreign Property REITs Complicate Foreign Tax Credit Claiming
Retirement accounts already have hidden tripwires for domestic property funds, but crossing a border introduces a completely different layer of tax friction for the investor. Buying an international REIT means dealing with foreign tax authorities.
When a portfolio includes international trusts, foreign governments take their cut before the cash ever hits a brokerage account. If a portion of that $6,500 annual payout comes from overseas properties, the home country automatically applies a withholding tax directly to the distribution.
The exact percentage depends entirely on official tax treaties between governments.
Recouping that withheld money requires proving the loss to the IRS. A standard taxable account allows the investor to claim the Foreign Tax Credit. This process means filing IRS Form 1116 to offset the foreign tax paid against the domestic bill, keeping the total return intact.
Putting these global assets in a retirement account breaks that mechanism.
Because IRAs do not owe current-year taxes, they cannot claim a credit for taxes paid elsewhere. The withheld cash simply vanishes, creating a permanent drag on the yield.
Tax-Deferred Accounts Eliminate Annual Dividend Tax Drag
Matching the right real estate trust to a tax-advantaged account stops the bleeding. A Traditional IRA or a 401(k) pushes the entire tax bill decades down the road.
That structural protection gives a $100,000 portfolio the space it needs to actually grow. The $6,500 cash flow generated each year gets reinvested immediately without a high tax bracket slicing the top off, allowing the compounding engine to run completely uninterrupted year after year.
The catch arrives when you finally withdraw the money.
Tax-deferred accounts treat every single dollar leaving the account as ordinary income. You trade the current tax drag for standard income tax later, losing any preferred capital gains rates entirely.
This strategy fits high earners who expect a sharp drop in their tax bracket after they stop working. If you are paying top marginal rates now, taking the income tax hit in retirement at a much lower rate is a calculated and highly effective mathematical trade-off.
You keep the yield today when it matters most.
⏳ The $100,000 REIT Portfolio Inside an IRA
Initial Allocation
Investing $100,000 at a 6.5% yield generates $6,500 annually, sheltering the $4,550 ordinary income slice from immediate year-one tax drag.
The Breakdown Trap
Public REIT distributions are typically split 70% ordinary income, 15% capital gains, and 15% return of capital. Inside an IRA, this distinction is erased.
Statutory RMD Enforcement
Required minimum distribution rules force annual taxable withdrawals once you reach statutory age, stripping away timing control.
The Conversion Cost
You trade the preferential 15% capital gains rate and tax-free return of capital ($975 yearly) for ordinary income taxation on 100% of final withdrawals.
Roth IRAs Provide Complete Tax-Free REIT Yield Accumulation
Bypassing withdrawal taxes entirely requires moving the asset into a Roth IRA. Holding publicly traded real estate shares here creates a permanent shelter for both annual distributions and your future withdrawals.
Tax-free growth radically changes the math on a $100,000 portfolio throwing off a 6.5% yield. Decades of reinvesting that $6,500 annual payout without a single dollar lost to the IRS maximizes the compounding effect, snowballing the balance far faster than any taxable brokerage equivalent.
Account structure dictates what kinds of trusts actually belong here.
Publicly traded equity shares bypass the heavy Unrelated Business Taxable Income traps that often catch private real estate funds. The standard publicly traded shares remain perfectly safe inside the Roth wrapper.
Federal tax rules currently guarantee that qualified withdrawals of accumulated real estate income after age 59.5 are entirely tax-free. For a long-term investor willing to lock the money away until retirement, this completely eliminates the yield taxation problem from the first payment to the final sale.
It is the strongest shield the tax code offers.
Taxable Accounts Suit High-Return-of-Capital REIT Strategies
Standard taxable brokerage accounts still make sense for trusts built on heavy property depreciation. A high percentage of return-of-capital in the distribution essentially creates its own internal tax shelter right away.
You find these specific assets by pulling their historical investor relations reports. Checking the yearly tax breakdown reveals which real estate trusts consistently classify their payouts as return of capital rather than ordinary income, allowing you to match the correct high-depreciation asset to a normal taxable brokerage account.
This structural tax deferral works continuously until you sell.
That 15% return of capital slice defers taxes year after year, lowering your original cost basis while protecting the current $6,500 cash flow from immediate taxation. The bill waits at the end.
Holding that heavily depreciated asset until death turns that deferred liability into a massive estate planning advantage. The tax code grants a step-up in basis to your heirs, completely wiping out the accumulated capital gains taxes triggered by decades of those original basis reductions.
The massive deferred tax bill simply disappears upon death.
Frequently Asked Questions
Why am I paying higher tax rates on my REIT dividends than on my stock dividends?
Because REITs pass through their taxable income without paying corporate taxes, the IRS taxes the majority of those distributions at your standard ordinary income rates. Regular stock dividends usually qualify for lower long-term capital gains rates.
Is there any tax break available for REIT dividend income in a taxable account?
Yes. Investors can often deduct up to 20% of their qualified REIT dividends using the Section 199A deduction. This lowers the effective tax rate on the ordinary income portion.
Why did my REIT dividend not show up as taxable income on my form?
That portion was likely classified as a return of capital. It defers immediate taxation but lowers your original cost basis, which increases your capital gains bill when you eventually sell.
Can I still owe taxes on REIT income held inside my tax-free Roth IRA?
Yes, if the holding generates Unrelated Business Taxable Income. This usually only happens with private or debt-leveraged real estate structures that cross the $1,000 filing threshold, not standard publicly traded REITs.
Which type of account keeps the most REIT income in my pocket each year?
A Roth IRA provides completely tax-free accumulation and withdrawals, making it the most efficient choice. A Traditional IRA defers the tax drag entirely until retirement, which is the second best option.
Auditing Your REIT Tax Blueprint
Audit the exact tax breakdown of your current holdings by checking Box 2a and Box 5 on your IRS Form 1099-DIV.
If ordinary income is eating your returns, shift those tax-inefficient positions into tax-advantaged accounts to protect future payouts, verifying all current rules against official IRS guidelines.
A 6.5 percent yield on a $100,000 portfolio only delivers its full power if your account structure actively defends it from the tax code. A yield is never just a yield until you know exactly how much of it you actually get to keep.
