
Chasing headline yields straight into a sudden dividend suspension is a painful way to learn how quickly a reliable income stream can disappear when the economy contracts.
That gut-checking experience is why an income-focused investor managing a $100,000 diversified income portfolio needs to look past attractive marketing labels and examine the balance sheet underneath.
Major historical recessions such as 2007-2009 and 2020 proved that twelve common income asset types slashed or suspended their distributions by 25% to 100%.
By evaluating cash flow stability and debt coverage rather than chasing headline yields, investors will be able to decide which assets to eliminate and protect their portfolios from sudden payout cuts.
Quick Tips Before You Start
Check the Payout Ratio
Filter out any asset paying out more than 85 percent of its operating cash flow.
Monitor Leverage
Avoid businesses with debt-to-equity ratios exceeding 2.0 during late-cycle periods.
Diversify Sectors
Spread your $100,000 across uncorrelated cash streams to absorb single-industry shocks.
Prioritize Quality
Accept lower initial yields on senior instruments rather than chasing speculative payouts.
1. Commercial Mortgage REITs Slashed Payouts As Defaults Soared
Watching a high-yielding dividend payment suddenly vanish from your brokerage statement feels like a punch to the gut when you are relying on that cash flow to pay your actual bills.
Commercial real estate investment trusts often ran on heavy leverage dependence long before a downturn hit, frequently pushing debt-to-equity ratios above 2.0 to finance massive property portfolios.
When economic contractions arrived, property valuations plummeted rapidly, causing commercial property default rates to spike as tenants struggled to keep their doors open.
Severe cash flow contraction forced real estate investment trusts heavily exposed to commercial loans to slash their distributions by 25% to 100% without warning.
A $100,000 diversified income portfolio holding commercial mortgage REITs suffered sudden distribution cuts when rental income failed to service underlying debt obligations.
💡 Tip: Keep REIT allocations under 10 percent of your total income portfolio.
| Asset Class | Pre-Recession Yield | Payout Action | Recovery Timeframe |
|---|---|---|---|
| Commercial Mortgage REITs | 8% – 12% | 25% to 100% Slash | 3 to 5 Years |
| High-Yield Corporate Bonds | 7% – 10% | Complete Suspension | Permanent Loss / Restructuring |
| Financial Sector Stocks | 5% – 7% | Eliminated | 2 to 4 Years |
| Energy MLPs | 6% – 9% | 50% to 80% Cut | 3 to 6 Years |
2. High-Yield Corporate Bonds Suffered Deep Coupon Suspensions
Check your fixed-income holdings right now for speculative-grade exposure before credit markets freeze up during the next economic contraction.
High-yield corporate bond issuers carried heavy debt loads and weak credit ratings entering economic contractions, making them exceptionally vulnerable to sudden shifts in market liquidity.
Junk bond default spikes occurred as liquidity dried up completely, triggering widespread credit rating downgrades that left issuers unable to refinance maturing obligations.
Issuers defaulted or restructured debt, causing a total loss of regular coupon income for bondholders who had trusted those headline yields.
A $100,000 diversified income portfolio experienced permanent cash flow interruptions when speculative-grade bond coupons were suspended entirely.
⚠️ COMMON MISTAKE
Ignoring Credit Ratings on High-Yield Debt
Treating high-yield bond funds like cash equivalents leaves your capital exposed to sudden restructuring losses when liquidity vanishes.
3. Financial Sector Common Stocks Eliminated Dividend Distributions
It is completely normal to feel a sense of betrayal when a stock you held for its supposed safety suddenly eliminates its payout entirely.
Major banks and regional lenders operated with thin capital cushions before economic downturns hit, leaving them dangerously exposed when commercial and consumer loans started going sour.
Regulatory capital requirements and surging loan loss provisions forced boards to prioritize cash preservation above all else, abandoning the shareholders who depended on them.
Major banks and regional lenders slashed or entirely eliminated dividends to build required reserves and satisfy regulators who demanded bulletproof balance sheets.
I watched my own dividend income drop by thousands of dollars in a single quarter when institutions I thought were untouchable suddenly hit the pause button.
When boards mandated the complete suspension of common stock dividends, the illusion of permanent banking stability vanished overnight.
A $100,000 diversified income portfolio lost foundational banking yields when these emergency measures took effect across the financial sector.
Reviewing your exposure to the banking sector requires looking past historical stability to examine actual capital cushions and loss reserves.
Financial Sector Vulnerability — The Numbers Behind It
🏦 Leverage Benchmark
Debt-to-equity ratios above 2.0
📉 Loss Provision Threshold
Surging loan loss reserves
✂️ Portfolio Impact
Up to 100% distribution cut
⏳ Regulatory Mandate
Cash preservation over yield
Skip Condition
Avoid banking equities where Tier 1 capital ratios hover near regulatory minimums.
4. Master Limited Partnerships Slash Distributions On Energy Slumps
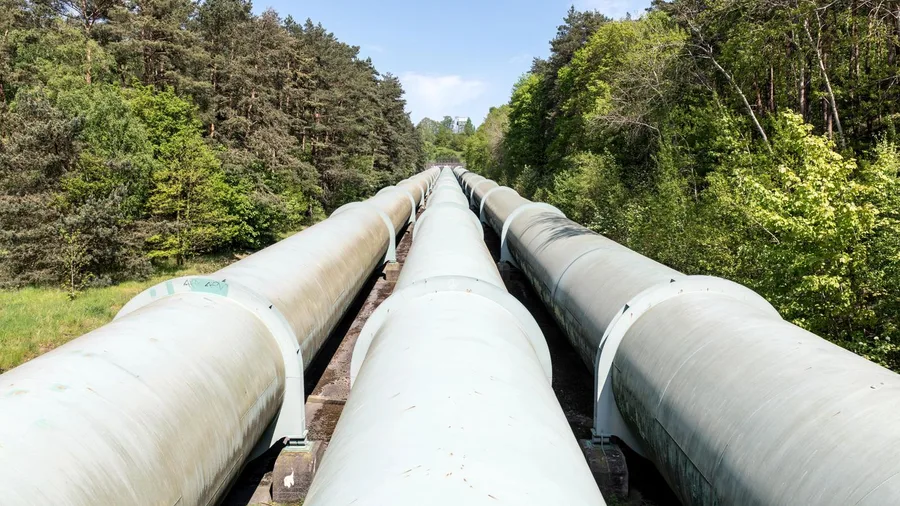
The answer lies in how these massive midstream networks are financed long before the first barrel flows through a pipe. Energy master limited partnerships typically carry heavy capital expenditure commitments funded heavily by external debt rather than cash on hand.
When regional demand contracts and production volumes freeze, the steady tolls collected across thousands of miles of pipeline evaporate almost overnight. Severe volume-based revenue drops collide directly with rigid debt covenant restrictions, forcing management teams to slash cash distributions completely just to maintain basic corporate solvency.
A $100,000 diversified income portfolio holding energy MLPs absorbs painful, sudden payout reductions when throughput volumes plummet during a downturn. It is entirely acceptable to scale back exposure to volatile cyclical sectors rather than weathering every storm with white knuckles.
Portfolio Defense Audit Time Allocation
5. Business Development Companies Trimmed Payouts Amid Asset Writedowns
Sitting at the kitchen table reviewing quarterly statements during past market corrections, the sheer weight of sudden asset writedowns became impossible to ignore. Why did prominent Business Development Companies cut their dividend payouts so drastically when the broader economy slowed down? These specialized lenders provided capital to middle-market businesses carrying high debt-to-equity ratios above 2.0, assuming corporate growth would continue uninterrupted.
Surging non-accruals quickly triggered widespread loan defaults across struggling corporate borrowers, leading directly to severe net asset value declines on the lender books. Regulated investment company rules required these vehicles to distribute the vast majority of their earnings to shareholders, creating a harsh compliance trap.
When massive asset writedowns impaired portfolio values, boards had to slash dividend rates rapidly just to stay legally compliant and preserve remaining capital reserves. A $100,000 diversified income portfolio saw reduced cash flows as BDC dividend rates were trimmed to match impaired asset values.
Acting quickly before mandatory compliance deadlines hit helps protect annual returns from unexpected income shocks.
💡 PRO TIP
Focus on Net Asset Value Coverage
Check whether a BDC trades at a steep discount to net asset value, which often signals hidden portfolio distress.
6. Discretionary Retail REITs Cut Rents And Lowered Distributions
Retail property owners depended on continuous tenant occupancy to service high property mortgages.
Middle-market lending losses transition directly into the physical property and tenant distress experienced by retail real estate landlords. When consumer spending drops, shopping center operators face immediate operational strain.
Tenant bankruptcies caused widespread tenant occupancy loss and forced rent concessions across shopping centers. Retail property owners faced severe income drops, leading directly to reduced dividends to match cash flow.
A $100,000 diversified income portfolio dependent on retail real estate experienced lowered payouts as tenant cash flows dried up. Property debt loads remained fixed while incoming rents collapsed entirely.
Investors must examine underlying lease durations and tenant credit profiles before committing capital. Limiting retail real estate exposure to properties with weighted average lease terms exceeding five years provides a measurable buffer.
Review the rent roll of any real estate holding this week to verify tenant diversification across defensive retail sectors like grocery anchors rather than discretionary apparel.
High yields are rarely a gift; they are the market pricing in the probability of a future payout cut.
— What experienced income investors keep repeating
7. Infrastructure Funds Trimmed Yields Under Passenger Volume Drops
Over the last three to five years, reviewing public infrastructure assets requires looking closely at two distinct balance sheet metrics before investing a single dollar.
Toll roads and airport networks relied on heavy senior debt loads secured by future user fees, creating an invisible ceiling when passenger volumes dropped.
When economic contractions struck, traffic and travel volumes across these transportation networks collapsed by 30% to 50% almost overnight, choking off the cash coming through the turnstiles.
Because lenders required senior debt service to be paid first regardless of economic conditions, the resulting drop in net operating income left zero surplus cash for equity holders, forcing boards to slash payouts.
A $100,000 diversified income portfolio holding these infrastructure funds absorbed severely reduced yields as user-fee revenues fell short of debt obligations, proving that essential public services are not immune to debt math.
Infrastructure Resilience Indicators
8. Closed-End Funds Slashed Leverage and Reduced Distributions
Many investors assume that borrowing money inside a closed-end fund is a safe way to permanently increase cash flow without real downside risk.
In reality, these funds borrowed money against their portfolio assets to push headline yields well above underlying asset returns, operating with debt cushions that evaporated during market panics.
Severe asset price destruction at market bottoms breached strict borrowing limits, activating mandatory deleveraging triggers that forced fund managers to sell holdings into falling markets.
Selling underlying assets at depressed prices locked in permanent capital losses, resulting in permanent distribution rate resets rather than temporary dividend pauses.
A $100,000 diversified income portfolio holding these leveraged funds suffered permanent income destruction when distributions were slashed to match the damaged asset base.
9. Global Shipping Trusts Suspended Payouts On Freight Rate Collapses
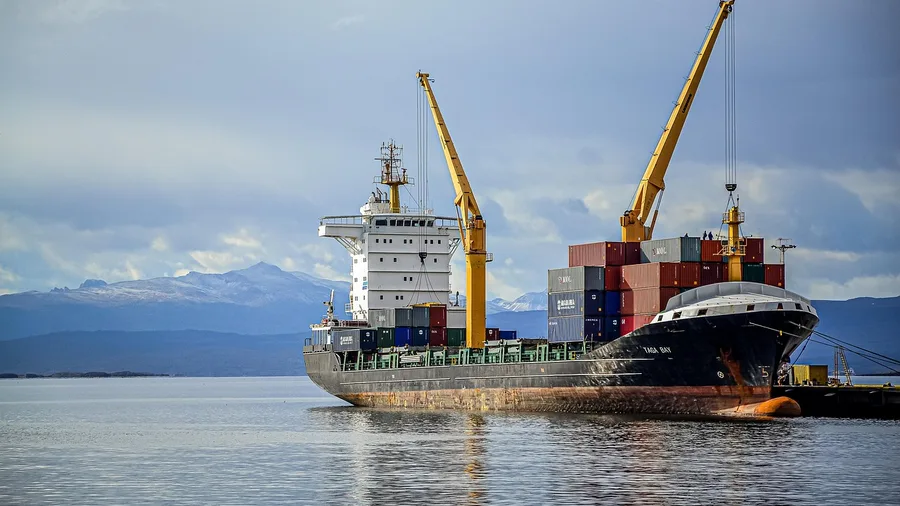
Watching cargo ships sit idle for months in harbor terminals makes the vulnerability of maritime leasing companies immediately clear to anyone reviewing logistics assets.
Container shipping and maritime leasing corporations operated with immense fixed vessel costs and cyclical debt structures that demanded constant global trade volumes to survive.
When global trade volumes contracted sharply during economic downturns, charter rates across international shipping routes dropped by more than 60%, leaving operators unable to service their debt.
Companies halted distributions entirely to achieve immediate cash preservation and keep basic operations afloat, leaving investors with zero payout.
A $100,000 diversified income portfolio experienced complete distribution halts from shipping trusts when freight markets collapsed under the weight of fixed costs.
10. Mortgage Agency REITs Cut Dividends On Prepayment Volatility
Even government-backed paper cannot protect you from violent interest rate swings. Agency mortgage REITs held leveraged portfolios of mortgage-backed securities funded by short-term repurchase agreements.
Interest rate volatility triggered extreme prepayment speeds and hedging losses eating into earnings. Book value erosion forced sudden dividend reductions exceeding 85% of cash flow or complete suspension.
A $100,000 diversified income portfolio exposed to agency mREITs lost substantial income when book values collapsed.
11. Automotive Supplier Income Trusts Halted Distributions Entirely
Cyclical manufacturing income vehicles relied on steady vehicle production schedules and high operating leverage. Credit crunches caused immediate production line shutdowns and severe working capital constraints.
Boards suspended dividends entirely to preserve cash and meet vital operational payrolls. A $100,000 diversified income portfolio holding automotive supplier trusts faced total distribution elimination during the manufacturing freeze.
A common mistake is treating industrial cyclical yields as permanent bond substitutes.
12. Fixed-Rate Preferred Stocks Deferred Distributions During Credit Crunches
Sound familiar? Preferred shares look safe until financial issuers activate non-cumulative clauses. Financial institutions issued non-cumulative preferred shares offering high fixed yields with junior standing relative to debt.
Severe credit crunches threatened capital adequacy, activating non-cumulative distribution terms. Firms skipped dividend payments entirely to satisfy regulatory capital compliance and protect senior creditors.
A $100,000 diversified income portfolio relying on preferred stock income faced unexpected distribution deferrals when financial issuers exercised non-cumulative clauses.
Frequently Asked Questions
Is it too late to start investing for income after 40?
It is never too late to begin building a cash-flowing portfolio. Focusing on quality assets with sustainable payout ratios matters much more than your starting age.
How much should I keep in my emergency fund before chasing dividends?
Aim for three to six months of living expenses in cash before deploying capital into income-producing assets. This prevents you from selling dividend stocks during a market downturn.
Should I pay off debt or buy income assets first?
High-interest consumer debt outpaces almost any dividend yield you can find. Clear out toxic interest obligations before building a stock-based income stream.
Is it okay to pause my dividend reinvestment during a recession?
Pausing automated reinvestment to stack cash reserves is a valid strategy when economic visibility drops. You control the capital allocation.
How can I spot a high-yield trap before it cuts its payout?
Examine the underlying cash flow statement rather than headline yields. If dividend payments exceed operating cash flow, a cut is likely incoming.
Evaluating Cash Flow Stability Over Headline Yields
Protecting your hard-earned capital requires looking past attractive dividend labels to inspect the balance sheet underneath.
An income-focused investor examining a $100,000 portfolio must look past attractive pre-recession yields to identify excessive borrowing above 2.0 debt-to-equity and payout ratios exceeding 85% of cash flow.
Recognizing these structural vulnerabilities safeguards future portfolios against the 25% to 100% distribution cuts that characterize economic contractions.
Audit Your Income Portfolio Today
Review your holdings against the 85 percent payout threshold and trim high-leverage positions before the next economic contraction.
