
Claiming Social Security at 62 means a smaller check, while waiting until 70 gives you more each month – but the total money you get over your whole retirement is the real question.
It is easy to get caught up thinking only about that first payment that lands in your bank account.
The bigger picture involves how much you will collect over years, not just the first few weeks. Your personal health, your other savings, and who else relies on your benefits all weigh heavily on this choice.
This guide will help you pinpoint your own break-even age and stack it against your life's details, so you can pick a claiming strategy that truly fits your retirement path.
| Claiming Age | Monthly Benefit | Cumulative Payout by Age 80 | Cumulative Payout by Age 90 |
|---|---|---|---|
| Full Retirement Age (67) | $2,000 | $312,000 | $552,000 |
| Age 62 | $1,400 | $302,400 | $470,400 |
| Age 70 | $2,480 | $297,600 | $535,680 |
Claiming at 62 Locks In a Significantly Lower Monthly Payment
Claiming Social Security at age 62 locks in a notably lower monthly payment.
For most people, 62 is the earliest age they can start receiving Social Security benefits, but it comes at a cost.
If your Full Retirement Age (FRA) is 67, choosing to claim at 62 means your monthly benefit is permanently reduced by 30%. This significant percentage directly impacts your income for every single month of retirement.
For example, if your Full Retirement Age benefit would have been $2,000, claiming at 62 reduces that to just $1,400 per month. That's $600 less every 30 days.
This is not a temporary dip.
The reduction is permanent, shaping your financial reality for the duration of your retirement. This smaller, guaranteed income stream forms the foundation of your future finances, making it a critical factor to understand before you decide to claim early.
Monthly Social Security Benefit: 62 vs. 70
Based on a $2,000 Full Retirement Age (FRA) benefit
Delaying Until 70 Maximizes Your Guaranteed Monthly Payout
Delaying until age 70 secures the highest possible monthly Social Security benefit. It's how you truly maximize your guaranteed payment.
Your benefit grows through Delayed Retirement Credits, a core feature of the system. For every year you hold off claiming past your Full Retirement Age (FRA) up to age 70, your benefit increases by 8%. This mechanism provides a powerful form of longevity insurance, building a more substantial income for your later years.
If your FRA benefit is $2,000 a month, waiting until age 70 changes that. You'll receive $2,480 each month instead.
These delayed credits stop accumulating at age 70. No further growth occurs.
While delaying means bridging an income gap for a few years in your early retirement, this strategy locks in a much larger, inflation-protected income stream for the rest of your life. That added security can bring a lot of peace of mind.
How Delayed Retirement Credits Add Up
The 'Break-Even Age' Is When Total Payouts Equalize
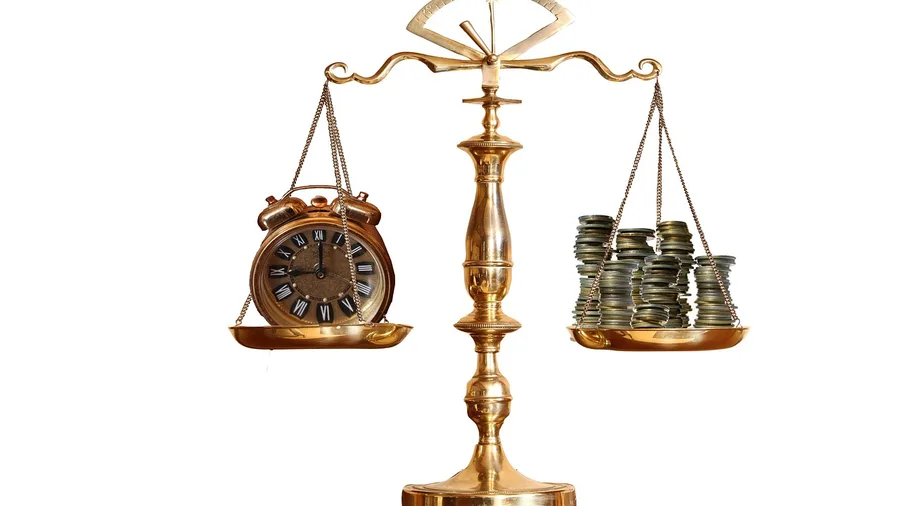
The 'break-even age' is a crucial calculation for your Social Security decision. It's the moment your total benefits claimed early equal your total benefits from waiting.
This age marks the point where the overall cumulative money received by starting at 62 finally equals the cumulative amount you'd get by delaying until 70. It's not just about the size of each monthly payment, but the lifetime sum of all checks.
How do you figure this out? It's a simple formula.
You calculate the total smaller payments received from age 62 up until 70, then divide that sum by the larger monthly difference you'd get by claiming at 70. This tells you exactly how many months of bigger checks are needed to catch up.
It pinpoints the age where the financial advantage of claiming early disappears. After this specific age, delaying until 70 starts yielding more total money. This is a purely mathematical exercise.
Calculate Your Own Break-Even Age to See the Financial Crossover
The easiest way to figure out your personal break-even age is to calculate when the total money from delaying overtakes the total from claiming early.
The calculation involves comparing the cumulative benefits received by claiming at 62 against the eventual higher benefits from waiting until 70. This gives you a clear number, rather than a guess, about when waiting starts to pay off.
Consider someone claiming at 62: they receive $1,400 per month for 96 months (from age 62 to 70), which adds up to $134,400.
If they waited until 70, their monthly benefit would be $2,480. That's a difference of $1,080 each month compared to claiming at 62.
To find the break-even point after age 70, you divide the total benefits received early ($134,400) by that monthly difference ($1,080). This comes out to approximately 124.44 months, or about 10 years and 4 months.
So, added to age 70, this specific individual's break-even age is roughly 80 years and 4 months. Understanding this figure is key to making an informed decision about maximizing your own lifetime benefits.
Break-Even Age — At a Glance
📅 Years Benefits Taken Early (62-70)
8 years (96 months)
💰 Total Early Benefits (62-70)
$134,400
⬆️ Monthly Difference (70 vs 62)
$1,080
⏳ Months to Break Even (post-70)
124.44 months
🎂 Approximate Break-Even Age
80 years, 4 months
Your Health and Longevity Significantly Impact the Best Claiming Age
Your personal health outlook and family history of longevity profoundly affect how long you'll collect Social Security benefits and whether reaching or surpassing the break-even age is likely.
This means if someone were to pass away before that calculated break-even age – say, before 80 years and 4 months in our example – claiming benefits at 62 would have resulted in more total money received over their lifetime.
Conversely, living well beyond the break-even age, perhaps into your late 80s or 90s, strongly favors delaying benefits until age 70.
In that longer scenario, the cumulative total from the higher monthly payments would grow significantly, leading to a much larger overall payout. This is why looking at your personal and family health history, including any chronic conditions, is so important.
Nobody has a crystal ball. But these are real considerations.
Spousal Benefits Change the Claiming Math for Couples
For married couples, the decision one spouse makes about claiming Social Security can significantly impact the benefits available to the other spouse.
A spouse can potentially claim a benefit equal to 50% of their partner's Full Retirement Age (FRA) amount. So, if the higher earner's FRA benefit is $2,000, their spouse might be able to claim $1,000 per month based on their record.
It's a shared financial future.
Delaying the higher earner's claim until age 70 not only boosts their own monthly payment but also maximizes potential survivor benefits. This provides greater income security for the spouse who outlives them, which can be a critical cushion later in life.
Optimizing Social Security for couples often means looking at both spouses' ages, health, and individual benefit amounts together. It's about a coordinated strategy.
Consider both of you.
💡 PRO TIP
Don't Forget Survivor Benefits
For couples, the higher earner's decision at age 70 not only boosts their own check, but it also increases the survivor benefit for the remaining spouse. This is critical for long-term security.
Access to Other Retirement Savings Affects Claiming Flexibility
The presence of other retirement savings can significantly change the math for when you claim Social Security. Having a cushion of your own money, like funds in a 401(k), IRA, or a pension, gives you the flexibility to delay taking those Social Security checks.
This means you can choose to live off these personal savings for a few years, instead of drawing from Social Security immediately at age 62. For example, if you need $2,000 a month to cover your expenses, you could withdraw this from an IRA. This strategy allows your Social Security benefit to continue growing by 8% each year past your Full Retirement Age of 67, up to age 70.
By bridging that income gap with your own invested funds, you're giving your future self a much larger, guaranteed monthly payment. It's a strategic withdrawal: you use one pool of money (your 401(k)) to protect and grow another (your Social Security benefit).
This is a very different situation from someone who relies solely on Social Security for their daily expenses from the moment they stop working. The ability to use other assets to cover those early years effectively buys you time, letting you maximize that permanent monthly payout.
🧭 Decision Path: Delaying Social Security
Assess Current Savings
Determine if your 401(k), IRA, or pension can cover living expenses during the delay.
Calculate Income Gap
Figure out how much income you need from other sources each month while delaying.
Review Health Outlook
Consider your longevity and family history to estimate how long you will collect benefits.
Coordinate with Spouse
Discuss spousal and survivor benefits to optimize for both partners.
Set a Target Claiming Age
Choose the age that balances immediate needs with maximum lifetime benefits.
Continued Earnings Can Reduce Early Benefits
If you decide to claim Social Security before your Full Retirement Age of 67 but you're still working, your benefits might be temporarily reduced by what's called the "earnings test." This is a rule specifically for those who collect early benefits while also earning income above a certain amount set by the Social Security Administration each year.
For instance, if you earn more than the annual limit – which changes every year, but for 2024 it's $22,320 – a portion of your Social Security benefit will be withheld. The rule is that for every $2 you earn over that limit, $1 in benefits is temporarily kept back.
This can be a surprise for people who expect their full benefit check every month.
But here's the important part, and it's a common misunderstanding: those benefits aren't lost forever. Once you reach your Full Retirement Age, the Social Security Administration recalculates your benefit amount. They factor in the money that was withheld, giving you a slightly higher monthly payment for the rest of your retirement. So, while it's a temporary reduction in your early checks, it's essentially a deferred payment that boosts your benefit later on. It's a trade-off: immediate income versus a future adjustment.
Common Mistakes with Working and Claiming Early
Immediate Cash Flow Needs Often Drive Early Claiming
Sometimes, the decision to claim Social Security at 62 isn't about maximizing lifetime benefits, but about meeting immediate, pressing financial needs. Life can throw unexpected curveballs, and for many, claiming early is simply a necessary choice to keep things afloat right now.
Think about common scenarios: an unexpected job loss in your late 50s or early 60s, a sudden health issue that prevents you from working, or the need to care for a family member that requires you to step away from your job. In these situations, waiting until Full Retirement Age or even 70 might not be a viable option. That guaranteed $1,400 monthly payment at age 62, even if reduced, can be a lifeline.
It's important to acknowledge this reality. Not everyone has the luxury of substantial savings or perfect health that allows them to defer income for years. For some, the immediate cash flow from Social Security at the earliest age is the only way to cover essential living expenses, manage debt, or simply put food on the table.
This is a clear trade-off: you get access to crucial funds right away, but in exchange, you accept a permanently lower monthly payment for the rest of your life. It's a choice made out of necessity, not always preference.
Maximizing Lifetime Income Favors Delaying for Many
While immediate financial needs often prompt many to claim Social Security early, maximizing your lifetime income generally favors delaying benefits until age 70 if your health and other savings allow. This choice isn't about willpower; it's a calculated deferral of short-term income for a substantially larger guaranteed payout over the long run.
Those delayed retirement credits are key, adding 8% to your benefit for each year you wait past your Full Retirement Age (FRA) of 67, up to age 70.
That's $2,480 a month instead of $2,000.
This larger payment isn't just more money; it acts like a personal longevity insurance policy. It guarantees you a higher, inflation-protected income stream for as long as you live, which is a powerful safeguard against depleting other savings later in retirement.
Yes, this strategy requires having enough other funds, like your 401(k) or IRA, to live on for those few extra years. It's a real trade-off.
But the payoff can be significant.
Monthly Benefits: Claiming Age Impacts
Claiming at 62
- Your monthly benefit is $1,400, a $600 permanent reduction from FRA.
- Cumulative income is higher initially, then lower after roughly age 80.
- May result in lower potential survivor benefits for a spouse.
- You lock in your benefit amount with no further increases.
Claiming at 70
- Your monthly benefit is $2,480, a $480 permanent increase over FRA.
- Maximizes total lifetime income for a longer lifespan.
- Ensures the maximum possible survivor benefit for a spouse.
- Requires covering living expenses for 3-8 years from other savings.
Frequently Asked Questions
Is 62 too early to claim Social Security?
It depends on your personal financial and health situation. Claiming at 62 results in a permanently reduced monthly benefit, but it can be the right choice if you need immediate income due to job loss or health issues.
How much more will I get if I wait until 70?
Waiting until age 70 can significantly increase your monthly benefit. For example, if your Full Retirement Age benefit is $2,000, waiting until 70 could increase it to $2,480, thanks to Delayed Retirement Credits.
What is my Full Retirement Age for Social Security?
Your Full Retirement Age (FRA) depends on your birth year. For most people born in 1960 or later, it is age 67. You can find your specific FRA on your Social Security statement or the SSA website.
Does claiming early affect my spouse's benefits?
Yes, your claiming decision can affect your spouse's benefits, especially survivor benefits. Delaying the higher earner's claim often maximizes potential survivor benefits, providing greater financial security for the surviving spouse.
Can I work and claim Social Security benefits at the same time?
You can, but an earnings test applies if you claim before your Full Retirement Age. If your income exceeds a certain limit, some benefits may be temporarily withheld. These withheld benefits are typically restored in the form of higher future payments at your FRA.
The break-even age offers a really important way to see the dollar differences between claiming Social Security early versus waiting.
But the best age to claim is never just about math; it is a decision tied deeply to your personal life.
Take a good look at your financial setup, your health outlook, and your family's needs to land on a Social Security plan that genuinely supports your retirement.
The aim here is not simply to get the biggest single number, but to build lasting financial security and peace of mind for all your retirement years.
Ready to Map Your Retirement Income?
Review your latest Social Security statement online to see your personalized benefit estimates at different claiming ages.
