
Unopened medical bills sitting on your counter create a specific kind of quiet dread.
You look at the balance, wonder how an emergency room visit turned into a house payment, and shove the envelope back into the drawer because dealing with insurance feels impossible.
It is not your fault the system is opaque, but the rules have shifted in your favor, and most people have no idea they can push back.
Quick Tips Before You Start
Get the Itemized Bill
Never pay the summary statement without requesting a full itemized breakdown first.
Wait for Insurance
Give your insurance provider 60 days to process claims before panicking over a balance.
Check Your Credit Report
Pull your free reports to see what medical accounts are currently listed.
Call the Billing Office
Ask about hardship programs before agreeing to a payment plan.
1. Pulling Your Credit Reports
I stared at my credit report for twenty minutes last fall convinced the medical collection listed there was some official decree I just had to live with.
Most people assume these files are objective ledgers etched in stone when they are actually messy databases furnished by third parties full of transcription errors and bills you already settled.
Pull your official reports from the three major bureaus using the free annual site this week and look specifically for medical lines that do not belong to you.
💡 Tip: You can access your reports for free weekly online.
⚠️ COMMON MISTAKE
Paying Without Checking First
Never pay a medical collection agency the moment they call without verifying the debt belongs to you and matches your hospital records.
2. The Under-500 Dollar Rule
Under current credit reporting agency agreements, medical collections under $500 do not appear on your credit report at all.
If you see a medical balance of $350 sitting on your Equifax or TransUnion file, it violates current standards.
Contact the reporting bureau immediately to dispute the entry.
This single change removed hundreds of thousands of small collection accounts overnight.
The Reporting Shift
3. Waiting Out the One-Year Grace Period
You probably think that unpaid hospital bill goes straight to your credit report to wreck your score tomorrow morning.
That used to happen, but the rules shifted to give you a full one-year grace period from the date the bill was first past due before medical debt can touch your credit file.
Do not panic and do not pay immediately.
Use that twelve-month window to set up a monthly calendar alert for day 30, 90, and 180, leaving the actual balance alone while you force your insurance company to reprocess the claim or negotiate with the hospital billing department directly.
💡 Tip: Mark the initial bill date on your calendar to track your 365-day window.
4. Starting Small With Your Savings
Financial advice often tells you to stash away six months of living expenses right away, which feels entirely impossible when you are already staring down a stack of overwhelming medical debt.
When every extra dollar feels spoken for by healthcare bills, trying to save can feel completely pointless. But skipping savings entirely just leaves you vulnerable to the next unexpected clinic copay or emergency prescription refill.
You do not need to fix everything this afternoon. Start with an achievable financial floor instead of an intimidating target. Even tucking away $25 a month into a separate account quietly builds a small, reliable cushion.
Consistency beats perfection every single time in personal finance. Building the habit of saving a tiny amount first matters far more than hitting an arbitrary milestone you cannot sustain on your current income.
Build the habit first and scale the amount later when your breathing room eventually expands. Open a separate account this week and set a tiny automatic transfer for your next payday.
Medical Debt Reality
Consumer Financial Protection Bureau data
5. The Deadline That Protects Your Score
365 days is the exact margin of error you get before a medical debt finally touches your credit report.
Time is your absolute greatest leverage when dealing with hospital billing departments, yet most people treat a bill like an immediate emergency that requires panic.
The mechanism here is a federal grace period designed to give patients a chance to catch insurance processing errors and billing department mix-ups before permanent score damage occurs.
If a medical bill sits unpaid for longer than that full one-year mark, it becomes eligible for credit bureau reporting and can drag down your borrowing power for years.
That means you have a twelve-month window to dispute discrepancies, request itemized statements, and force insurance companies to do their actual jobs without ruining your credit score in the process.
Mark that one-year anniversary right now on your phone calendar and treat it as a hard deadline for action instead of shoving the statement back into a kitchen drawer.
I missed a similar window on a lab bill years ago simply because I was too exhausted by the process to open the envelopes, and fixing the resulting drop on my report took six months of phone calls.
This week, check the date of service on your oldest outstanding medical bill and set a reminder for thirty days before its specific one-year mark so you stay entirely ahead of the clock.
💡 PRO TIP
Use the One-Year Buffer
Never panic when a collection letter arrives on day thirty. You have twelve full months to settle the claim before credit bureaus even know it exists.
6. My Own Billing Nightmare
Medical bills carry a quiet kind of intimidation that makes you want to pay them just to stop looking at the envelope.
I spent four months arguing over a $1,200 lab fee that my insurance company had already approved but failed to disburse, bouncing between four hospital departments before finally demanding a supervisor and asking for the itemized billing code sheet.
It turned out they had double-billed for an anesthesia consultation that never happened, which taught me to never trust a statement at face value and to always request the raw coding before reaching for your credit card.
💡 Tip: Always keep a log of every phone call, including the representative name and reference number.
7. When to Call a Professional
Sometimes you reach a point where your patience runs out and you need to hand the fight to someone else.
It is entirely normal to hit a wall when a hospital billing department puts you on hold for forty minutes and then transfers you to an automated system that hangs up. You are not failing at this just because a two-thousand-dollar error requires a specialist to untangle.
Certified patient advocates and nonprofit credit counselors know the exact insurance terminology that triggers a formal review.
They often work on a sliding scale or charge a flat fee around $150 to $300 to audit your billing statements and catch discrepancies you would never spot on your own.
I spent three frustrating weeks trying to fix a laboratory coding error myself before I finally called someone who did it for a living, and she got the charge dropped in forty-eight hours. Pride is an expensive luxury when it keeps you wrestling with complicated paperwork.
Paying a professional to make a large billing mistake disappear protects your financial health.
This week, search for a certified member of the Alliance of Professional Health Advocates or reach out to a reputable nonprofit credit counseling agency.
Backup exists for a reason.
Medical Debt Action Lanes
- Dispute under-$500 bills on credit reports — These should not be there under current rules.
- Negotiate payment plans before day 365 — Keep bills off your credit file by acting within the grace period.
- Ignore collection calls without verification — Always demand written validation of the debt first.
8. The Hidden Cost of Settling Too Fast
Why does paying off a disputed medical bill immediately just to make the phone calls stop turn into such an expensive mistake?
It feels like the fastest way to buy back your peace of mind when collection agencies start calling three times a day, but once you hand that money over, getting it back if you discover an insurance error or a billing duplicate is nearly impossible.
The mechanism here is unforgiving: collection agencies and hospital billing departments process incoming payments instantly, but reversing a transaction once it clears can take months of bureaucratic friction with no guaranteed payout.
The trade-off is real, asking you to tolerate a few weeks of uncomfortable collection notices and ringing phones while you actually verify the math against your insurance explanation of benefits.
Patience saves real money, so this week take a deep breath, ignore the pressure tactics on the phone, and spend twenty minutes cross-referencing every single line item before you part with a single dollar.
9. Overcoming the Fear of Hospital Billing
You assume that if a hospital bill arrives with your name printed on the front, the total is a fixed mathematical fact that you simply have to figure out how to afford.
That persistent myth keeps millions of people staring at unopened envelopes for months because hospital billing departments routinely miscode procedures or fail to apply negotiated insurance discounts properly before mailing out that terrifying first statement, driving up the initial numbers unnecessarily.
I spent nearly six months hiding a $1,400 lab bill under a stack of kitchen clutter out of pure dread, assuming my paralyzing anxiety meant I was fundamentally incapable of managing my own life.
What I believe now is completely different: billing offices operate on the quiet expectation that stressed patients will feel overwhelmed, give up, and pay the inflated sticker price out of sheer exhaustion.
Break that cycle by opening just one envelope today, locating the insurance adjustment column, and comparing it to your health plan paperwork before sending a single dollar.
💡 Tip: Treat opening mail as a weekly administrative appointment rather than an emotional event.
Medical Billing Jargon Decoded
10. Reviewing Your Accounts Quarterly
Every ninety days is the window where errors still have soft edges before they harden into long-term score drops.
Put a recurring reminder in your phone for the first Saturday of every quarter to pull your reports and look strictly at new medical entries or unexpected collection balances.
Catching a mistaken $350 lab charge in month three takes ten minutes to dispute, whereas catching it in year two takes months of phone calls and a bruised credit score.
11. Building a Three-Bucket System
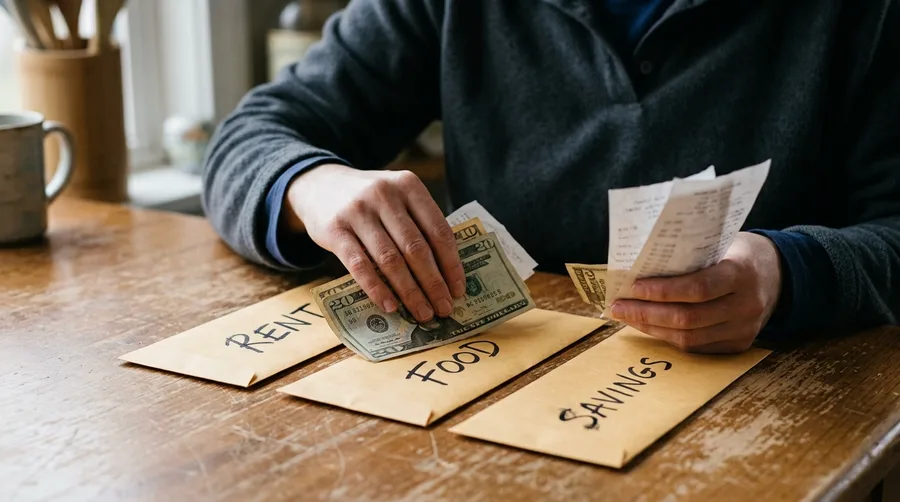
Divide every paycheck into three distinct categories the exact morning the deposit clears.
Most money systems fail because they treat all available cash as one giant pool, which is how a surprise $150 medical copay accidentally swallows the grocery money you needed for Thursday.
Bucket one handles fixed survival costs like rent, utilities, and insurance.
Bucket two is strictly reserved for debt minimums and active medical payment plans, keeping those obligations from bleeding into your daily life.
Bucket three covers flexible spending for gas and food, leaving you with a hard ceiling that stops runaway spending before it starts.
I used to keep everything in one checking account and just hope for the best, which meant I was constantly guessing whether I could afford a prescription.
Set up these three separate accounts this week and let automation move the money for you.
Your Seven-Day Medical Debt Audit
12. Giving Yourself Permission to Pause
You are allowed to stop for today and pick this back up when your brain has some actual room in it.
If staring at hospital paperwork after a fifty-hour work week makes you want to close the folder and pretend it does not exist, scale the goal down to just 15 minutes instead of a full audit. Total burnout happens when you try to fix three months of medical billing mistakes in a single exhausted evening.
Open one single billing envelope tonight, look at the service date, and leave the rest of the pile for Saturday morning when you actually have coffee and quiet.
13. Fixing Common Hospital Billing Mistakes
I spent three hours on the phone last spring arguing over a $450 charge for a routine blood draw that should have been fully covered.
Most people assume hospital billing departments never make mathematical errors, so they just pay whatever notice lands in the mailbox. They miscode procedures, fail to apply insurance adjustments, and bill patients for services covered under preventative care mandates because these massive systems rely on manual data entry prone to daily oversight.
The fix is simple: always request the detailed itemized bill with CPT billing codes and cross-reference them against your insurance policy booklet. Catching a single miscoded room charge or lab fee can drop a bill by hundreds of dollars instantly.
It feels awkward to question a medical facility, but you are not being difficult. Take ten minutes today to call the billing office and ask for the itemized breakdown before you send a single dollar.
14. The Honest Cost of Challenging Bills
Is spending three frustrating afternoons on hold with an insurance company actually worth the effort?
The honest cost of challenging a hospital bill is pure annoyance, requiring you to navigate endless phone trees and repeat yourself to five different representatives while trying to work a regular job.
The trade-off is saving anywhere from $500 to thousands of dollars in erroneous charges by refusing to pay for mistakes that were never yours to begin with.
Set aside one hour this Tuesday afternoon, grab a cup of coffee, and call the billing department to request a detailed itemized statement.
15. Automating Your Financial Defense
You might feel like your financial life is constantly playing catch-up against unexpected medical bills, and that exhaustion is completely valid when every month feels like a tightrope walk.
Setting up an automatic monthly transfer of $50 into a dedicated health savings or emergency buffer account every single payday changes the dynamic entirely.
Taking willpower out of the equation ensures your cushion grows without requiring daily decisions that you simply do not have the mental bandwidth to make after a long week.
Willpower is a finite resource, whereas automated banking rules operate in the background without needing your permission or your daily attention.
This simple setup protects you from future unexpected clinic visits and keeps your household finances stable over the long run.
When a $400 unexpected lab fee lands in your mailbox six months from now, the cash is already sitting there waiting instead of forcing you onto a high-interest credit card.
Take four minutes in your banking app today to schedule the transfer and close the book on medical debt stress.
You do not need to figure out the whole system right this second; just set that one automated rule and let consistency do the heavy lifting.
Frequently Asked Questions
Does paid medical debt still show up on credit reports?
No. Under current credit bureau rules, once a medical collection debt is paid or settled, it must be removed from your credit report entirely, regardless of the amount.
How long do medical bills stay on your credit report before being removed?
Medical debt cannot be reported for the first 365 days, giving you time to resolve insurance issues. Once reported, unpaid medical collections automatically fall off after seven years.
What should I do if a collection agency calls about a medical bill?
Never agree to pay over the phone immediately. Request written validation of the debt, check it against your itemized hospital records, and verify whether it exceeds the 365-day grace period.
Can hospitals sue me for unpaid medical bills?
Yes, healthcare providers can legally sue patients for unpaid balances, but many non-profit hospitals have financial assistance policies they must offer before taking legal action.
Are medical bills under $500 completely safe from credit scores?
Yes. The three major credit reporting agencies stopped including medical collection accounts under $500 on consumer credit reports, meaning they cannot lower your score.
Your First Step This Week
You do not need to fix every medical bill by Friday afternoon.
Pull your credit reports today, find one erroneous or small collection account, and start the dispute process while the new rules work in your favor.
