
You stare at your bank app on a Tuesday night, wondering where three weeks of pay went.
It feels like discipline is failing you, but the real issue is simply that unassigned money spends itself before you notice.
You are not bad with money, and you do not need a three-hour weekly spreadsheet ritual to fix this.
Zero-based budgeting is just a way of giving every single dollar an assignment before the month starts, and once it is set up, it takes less time than making coffee.
Quick Tips Before You Start
Keep It Brief
Spend exactly eleven minutes on Sunday morning doing your weekly check-in.
Separate Funds
Keep bill money in a distinct account so you never accidentally spend rent.
Write It Down
Use a simple paper notebook if fancy apps make you feel overwhelmed.
1. Accepting the Initial Friction
You hate opening the app because you expect bad news.
That lingering dread is the exact reason most budgets quietly collapse within fourteen days. You open the tab, see a number lower than you hoped, and close it right back up.
setting up your first zero-based plan takes about forty-five annoying minutes where you have to look directly at charges you would rather pretend didn't happen. It feels heavy at first, almost like punishing yourself for past mistakes. But you are not looking at the numbers to feel bad about a $60 dinner or an impulse buy; you are doing it so your spending becomes a deliberate choice instead of a monthly surprise.
If you skip this friction, you stay stuck.
The exhausting cycle of wondering where your paycheck went on the twelfth of the month continues because nothing is mapped out. The math will not fix itself while you are avoiding it.
The payoff arrives the following week when every single dollar finally has an assigned job and the background anxiety drops away completely. You stop guessing if you can afford groceries on Thursday because you already verified the category balance on Monday. The mechanism is simple: clarity replaces panic. Do the hard forty-five minutes one single time, and you buy yourself months of genuine mental quiet.
This week: block off forty-five minutes on your calendar, pour a cup of coffee, and open the last thirty days of bank statements without flinching.
💡 Tip: Play a favorite podcast while building your first budget to keep the mood light.
💡 PRO TIP
The Eleven-Minute Rule
Set a timer on your phone for eleven minutes every Sunday. When it rings, close the app and walk away.
2. Catching Expenses Before They Hit
Some people think budgeting is just tracking what already left your account. That is history, not a plan.
Waiting until bills arrive means you are permanently reacting, and unassigned cash tends to vanish into convenience spending. With average credit card interest rates sitting around 20 percent according to Federal Reserve data, letting bills surprise you carries a steep penalty. A single neglected expense put on plastic can quietly add months of compounding interest and financial strain to your plate.
I used to wait for the due dates to dictate my entire month, feeling a familiar knot in my stomach every time an alert popped up on my phone.
Real control means assigning dollars before the calendar page even turns. Open your banking app right now, look at last month's fixed costs, and write down the exact total for rent, utilities, and insurance. Assign those specific dollars first so you stop paying for ordinary living expenses with borrowed money, and give yourself a genuine head start instead of playing catch-up.
Where Your Money Goes
Federal Reserve SHED, 2024
3. Running Your Weekly Review
Are you actually looking at your categories twice a week, or just hoping for the best?
Open your banking app for exactly three minutes every Wednesday to check remaining balances across your main buckets.
That quick look stops surprises dead in their tracks before a $40 overage turns into a bounced transaction fee by Friday night.
I used to avoid my balance screen for weeks out of pure anxiety, and every single time that avoidance cost me real money.
📅 The Four-Step Weekly Routine
Log In
Open your tracking tool on Sunday morning.
Assign Cash
Allocate incoming paychecks to specific categories.
Check Balances
Review remaining amounts in grocery and gas funds.
Adjust
Move small surpluses to savings immediately.
4. Assigning Every Single Dollar
Give every single dollar a distinct job right when your paycheck clears.
Unassigned cash in a checking account is an invitation to accidental spending because money without a label always finds somewhere to go. When you move $300 to groceries, $150 to fuel, and $50 to savings on payday morning, you remove the guesswork that causes end-of-month panic.
I used to leave a buffer in my main account just in case, and it always vanished on takeout by Thursday. Assigning every dollar down to zero stops that leak completely.
Payday Allocation — At a Glance
🏠 Bills First
Cover rent & utilities
🍎 Food Next
Set grocery cash
💡 Buffer
$50 minimum save
Core Rule
Assign every dollar before noon on payday.
5. Rebuilding After Early Mistakes
It is completely normal to feel like you are failing when your very first zero-based budget completely falls apart by week three and leaves you staring at a negative balance.
I blew my first three zero-based budgets straight into the ground because I completely failed to include recurring pet supplies and basic haircut costs in my math. Every single month ended with an unexplained deficit, and it felt discouraging enough to make me want to quit entirely.
Real life simply refuses to fit into neat little spreadsheet columns, and your spending plan has to bend without snapping.
Everything finally clicked into place when I stopped pretending my life was entirely predictable and added a dedicated $100 miscellaneous category to the plan. That modest cash buffer absorbed the random everyday surprises, which allowed the rest of the system to finally stick around long enough to work.
This week, open your banking app, look at your last statement, and intentionally carve out a small padding line for the invisible costs you always accidentally omit from your initial calculations.
Best For
6. Building the Three-Bucket System
I used to keep all my money in one checking account and just guessed whether I could afford groceries after rent cleared, which is exactly how I accidentally spent my electric bill on takeout back in 2021.
The fix is separating your cash into three distinct buckets: fixed bills, debt minimums, and flexible spending, keeping your rent money physically isolated so you never accidentally touch it for smaller purchases.
This simple structure prevents accidental overspending by removing guesswork, and you can set it up in about ten minutes this afternoon by opening one separate savings account for your bills.
Traditional Budgeting vs Zero-Based
Traditional
- Tracks spending after it happens
- Leaves unassigned cash floating
- Relies on vague monthly guesses
Zero-Based
- Assigns every dollar in advance
- Leaves zero unallocated cash
- Uses exact weekly check-ins
7. Giving Yourself Permission to Scale Back
You do not need to track every single penny down to the cent if doing so drives you completely crazy.
If itemized receipt logging makes you want to quit, stop doing it immediately.
Perfectionism is the quiet killer of consistency.
When people try to capture every twenty-cent discrepancy across twelve different categories, cognitive fatigue sets in fast.
The mechanism here is simple behavioral economics.
When a system requires excessive emotional energy, your brain treats it as a threat and looks for an excuse to abandon it entirely.
Round your numbers to the nearest dollar and group minor purchases into a general miscellaneous pocket of about $50 to $100 a month.
Consistency matters far more than obsessive precision.
A slightly imperfect budget that you actually maintain for twelve months beats a flawless spreadsheet you abandon by Friday afternoon.
I spent my first three months trying to log every single stick of gum and felt like a failure every time my totals were off by $3.
Once I let go of the micromanagement and allowed myself rough round estimates, my tracking habit finally stuck.
Give yourself permission to make this easy enough that you can actually stick with it through your busiest, most exhausting life seasons.
This week: take your strictest spending category, loosen the reins by 10 percent, and see if your stress drops without your savings falling apart.
💡 Tip: Drop penny-counting entirely and round every category to the nearest five dollars.
Budgeting Jargon Busted
8. Starting Small With Twenty Dollars
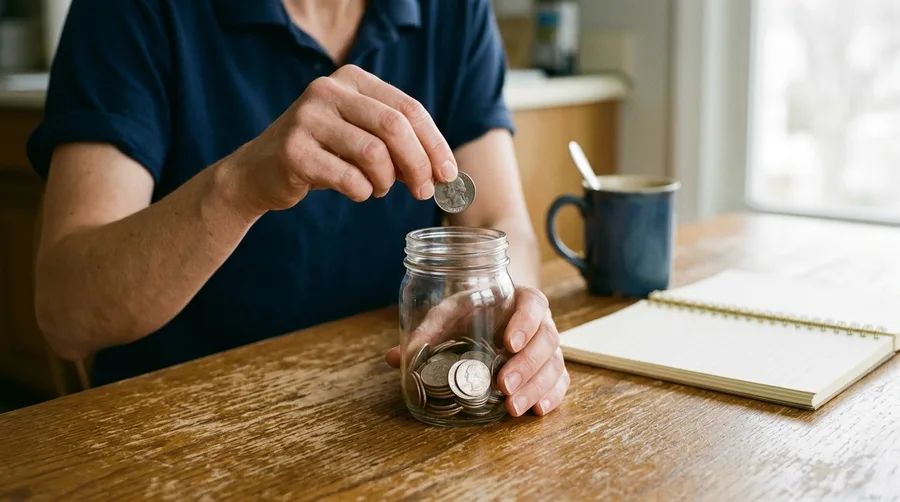
Starting with just $25 a month feels completely pointless when your credit card balance is thousands of dollars high.
automation removes the psychological friction of deciding, while small, consistent deposits compound cash flow buffers over time instead of leaving your checking account vulnerable to every minor grocery run.
Open your banking app right now and schedule a single recurring transfer of $25 for every payday morning, because starting tiny is infinitely better than waiting around for a windfall that never arrives.
9. Dropping the Scarcity Mindset
You might believe that budgeting means punishing yourself and never buying coffee again.
That scarcity trap makes you abandon your plan the moment you want a small treat, leaving you feeling like a failure over a $5 latte.
a budget is simply a tool that tells your money where you want it to go so you can spend guilt-free on things that actually matter.
When I finally stopped treating every dollar spent as a moral failing, my savings rate actually went up by about 15% because I stopped binge-spending out of frustration.
What I believe now is that intentional spending feels much better than accidental scarcity, and you can test this by setting aside just $20 this week explicitly for pure enjoyment without guilt.
10. Automating Your Core Transfers
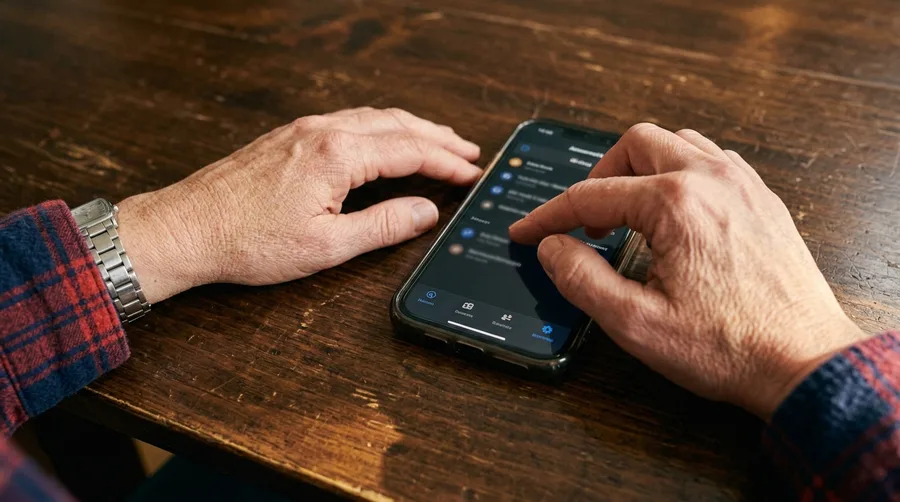
Set up automatic transfers for the exact morning your paycheck lands instead of waiting until the end of the month. I used to sit at my kitchen table every single Friday night moving money around manually, and it wore me down until I stopped doing it altogether.
Schedule rent, savings, and bill payments to move automatically within two hours of your paycheck hitting the account. This timing fix ensures your money goes where it belongs before you even see a single dollar of it sitting in your main spending balance, bypassing the temptation to spend it elsewhere.
Willpower is a terrible budgeting strategy when you are tired after a long shift.
Open your banking app this week and schedule just one recurring transfer, even if it is only $25 for your emergency buffer or your next utility bill. It takes about four minutes to set up once, and while it feels a little rigid at first, it takes the daily decision fatigue completely off your plate.
Let background systems do the heavy lifting so you never have to think about it again.
11. Fixing Category Over-Complication
Forty-two separate spending categories is a recipe for quitting by Wednesday.
I once tracked things down to fancy soap and notebook pens before realizing I was just punishing myself with paperwork instead of actually managing my cash.
Keep your main buckets down to six or seven essentials like housing, food, and utilities so your weekly review stays under eleven minutes.
Cut the micro-management this week and combine everything else into one catch-all miscellaneous bucket capped at $50.
12. Knowing When to Get Professional Help
Is this the moment you actually need to call someone else into the room?
Sometimes your numbers reveal debt levels or income gaps that a simple spreadsheet cannot solve on its own. When high-interest credit card balances are swallowing half your paycheck every month, basic budgeting is just a Band-Aid rather than a real fix.
The mechanism here is straightforward: interest rates hovering around twenty percent will outpace almost any personal savings plan you try to build alone. That is not a reflection of your discipline. It is a math problem that requires a different set of tools.
Consider talking to a nonprofit credit counselor or a fee-only financial fiduciary to review your specific situation. They can help you structure a debt management plan or look at options that an app simply cannot evaluate for you.
Getting outside guidance on heavy debt is a sign of practical strength, not failure. This week, look up one accredited nonprofit counseling agency in your region and check their credentials before you make the call.
13. Tracking Your Progress Weekly
Open your accounts every Sunday morning with a cup of coffee and look at where your money actually went.
I started doing this weekly check-in because monthly budgets felt too far away to stop any real damage, and seeing my grocery fund balance drop in real time immediately stopped those impulsive weekend takeout orders.
That tiny weekly habit saved me over $200 last month alone simply by catching small leaks before they turned into holes, so set a phone reminder for this weekend and just look at the numbers without judgment.
14. Capitalizing on Payday Timing
You might feel like waiting for a cleaner calendar before you start fixing your money.
That urge to wait for Monday or next month is completely normal, but it mostly just keeps the anxiety alive for another thirty days.
The best time to map your cash flow is right now, exactly as you are, before holiday spending or unexpected bills catch you off guard.
If you start your zero-based plan this month, compounding and cash flow habits lock in before heavy seasonal expenses hit your accounts.
every month you delay is another four weeks of wondering where your income leaks out in real time.
Waiting until January or next year only delays the mental relief you need right now, letting another $500 or $1,000 slip away entirely untracked.
Take forty-five minutes this weekend to build your baseline and put every single dollar to work before it has a chance to disappear.
Your future self will thank you for getting ahead of the curve.
15. Fixing Rigid Spending Categories
You stare at the screen, see you went twenty dollars over on groceries, and instantly feel like the whole system is broken.
That heavy feeling of guilt is entirely unnecessary and completely counterproductive to keeping your finances on track.
A zero-based budget is meant to be a living guide that bends with your real life, not a rigid prison sentence where one misstep ruins everything.
When an overage happens, simply roll it over by borrowing ten dollars from your entertainment fund next week to balance the ledger.
This week: open your tracker, adjust one tight category by ten dollars without shaming yourself, and watch how quickly the stress lifts.
Frequently Asked Questions
How long does zero-based budgeting actually take each week?
Once your initial categories are set up, a weekly check-in takes about eleven minutes. You simply log in, review remaining balances, and allocate incoming paychecks.
What should I do if my income changes every month?
Base your zero-based budget on your lowest expected monthly income. When you earn extra money, assign those surplus dollars to savings or extra debt payments.
Do I need a special app to do zero-based budgeting?
Not at all. A simple paper notebook, a basic spreadsheet, or any banking app works perfectly. Choose whatever method feels easiest for you to maintain consistently.
What happens if I overspend in a specific category?
Simply cover the difference by moving a small amount from another flexible category like entertainment. It is a normal part of adjusting your spending plan.
Is zero-based budgeting good for paying off debt?
Yes, because assigning every dollar ensures that debt minimums and extra payments happen automatically before discretionary spending takes over your paycheck.
Start With This Eleven-Minute Habit
You do not need to overhaul your entire financial life by Friday afternoon.
Open your notebook, write down your fixed bills, and give your next paycheck a clear assignment.
