
You stare at the minimum payment due on your screen and feel that familiar knot in your stomach. The math says one thing, but your actual life says another, and the numbers never seem to line up the way the textbooks promise.
It is easy to believe you are simply bad with money when every month ends with zero left over. That belief is entirely wrong.
Financial advisors often dismiss emotional strategies in favor of rigid spreadsheets, ignoring how humans actually behave under stress. Real progress starts when you fix the behavior first and let the mathematics catch up later.
Quick Tips Before You Start
Gather Statements
Print every current bill and balance so nothing stays hidden.
Freeze New Charges
Put your credit cards in a drawer and remove them from your phone wallets.
Call Lenders
Ask every credit card company for a temporary interest rate reduction.
Pick One Payday
Align all your automatic debt payments with the exact date your paycheck lands.
1. Start With the Smallest Balance First
Is $25 a month enough to make any real dent when you owe thousands of dollars?
It feels utterly pointless to throw pocket change at a mountain of debt when your monthly interest charges alone outpace your contributions, making the total balance look frozen week after week.
The math can feel discouraging, but that misses why this specific approach actually works.
Small contributions build immediate behavioral momentum that keeps you emotionally engaged long after the initial novelty of your budget wears off and life gets complicated.
Even $25 a month, moved automatically on payday, does more than $0 a month you keep meaning to transfer tomorrow.
💡 Tip: Name your smallest debt something motivating in your banking app, like 'The First Win'.
💡 PRO TIP
The Psychology of Quick Wins
Clearing one tiny balance in the first thirty days triggers a dopamine response that sustains your energy for the much larger accounts waiting behind it.
2. Automate Fixed Minimums Today
The worst part about owing money is the low-grade dread of checking the calendar to see whose bill is due tomorrow.
Missing a single due date triggers late fees and damages your credit score instantly.
Set every minimum payment to autopay right now so you never miss another deadline and take the daily anxiety of remembering dates completely off your plate for good.
Monthly Debt Servicing Layout
Assumes standard household baseline expenses.
3. Scale Back Your Fixed Commitments
I cut my cable package and three streaming services when my grocery bill spiked unexpectedly last winter, and that extra $120 a month changed my cash flow overnight.
Scaling back your fixed commitments feels intensely restrictive until you realize how much mental peace buying back your breathing room actually provides for your household.
Fixed expenses are the invisible anchors holding your debt in place because they drain your checking account automatically before you even get a chance to direct those dollars toward your balances.
You do not have to live like a monk forever or cancel every single joy in your life, but trimming the absolute excess for six solid months accelerates your payoff timeline significantly.
This week: open your last three bank statements, pick two recurring bills you barely touch, and cancel them to free up your first $40 or $50 right away.
4. Attack the Deadline Before It Hits

Introductory zero percent APR periods expire much faster than most people expect, quietly turning manageable balances into high-interest traps.
The mechanism is punishing: once that promotional window closes, the deferred interest often hits all at once at rates sitting around twenty or twenty-one percent, according to Federal Reserve data.
Target any promotional balance with a hard expiration date this week, move whatever extra cash you have toward it, and call your provider to confirm the exact date the clock runs out.
⚠️ COMMON MISTAKE
Ignoring Promotional Expiration Dates
Waiting until the final month of a zero-interest offer often leaves you scrambling to pay lump sums when standard 22% APR kicks in.
5. Accept the Trade-Offs Honestly
Roughly 21% is where average credit card interest rates sit according to Federal Reserve data from late 2024, meaning every single dollar you leave unpaid quietly costs you about 20 cents every single year in pure interest.
That is the hidden engine keeping balances stuck.
The math of compounding interest works against you just as aggressively as it works for investments, turning a moderate balance into a permanent monthly tax on your future earnings.
The trade-off is brutal: every extra dollar you scrape together to send toward an aggressive debt payment is a dollar you cannot spend on convenience, travel, social events, or even basic breathing room for the next twelve to twenty-four months.
That realization stops the financial bleeding because it forces you to weigh every discretionary purchase against how much longer you actually want your debt to drag out.
I spent two grueling years saying no to weekend trips, cutting out restaurant meals, and driving an aging car so I could finally wipe out a $14,000 credit card balance that had been hanging over my head like a cloud.
While it felt agonizingly restrictive back then, the psychological freedom on the other side is entirely unmatched.
No real financial move is entirely free of discomfort, so you have to choose your hard carefully.
This week, look at your upcoming month and consciously choose one discretionary spending category to pause so you can redirect that exact cash toward your principal balance instead.
6. Reframe Your Core Money Beliefs
You tell yourself you are just naturally bad with numbers.
That scarcity mindset keeps you hiding from your statements instead of opening them.
New belief: financial literacy is a learned skill, not an inherited trait. Open one account dashboard today for five minutes and just look at the raw data without judging yourself.
Quick Sequence Flow
7. Consult Professionals When Numbers Cross the Line
Book an hour with a nonprofit credit counseling agency or a fee-only fiduciary when your total unsecured debt exceeds your annual take-home pay.
Standard DIY repayment methods often stall out under crushing interest once balances reach that proportion, turning a math problem into a marathon you cannot win on willpower alone.
Getting an objective outside perspective ensures you do not waste years fighting debt structures that genuinely require formal restructuring or a formalized debt management plan.
Nobody walks into these offices to be judged, and the first consultation is usually free.
Bring your exact numbers this week and let someone who looks at these ledgers all day help you draw a clean line under what comes next.
8. Build a Monthly Review Habit
People assume that tracking your debt means staring at a spreadsheet every single night until your eyes blur.
That is the fastest way to burn out and quit entirely.
The real move is a single monthly touchpoint rather than a daily obsession.
Set a recurring calendar reminder for the final Sunday of every month to check your progress against your baseline targets.
Look specifically at three things: your total remaining balance, your average monthly interest charges, and whether your automatic transfers cleared correctly.
I used to avoid looking at my statements for six months at a time because the guilt felt heavier than the interest, which only let the fees compound silently in the background.
Checking the numbers once every thirty days keeps you connected to your goals without turning into an exhausting daily panic.
Open your calendar app right now and block off twenty minutes for this coming Sunday.
9. Establish a Three-Bucket Cash Flow System
30 days is usually how long a single checking account lasts before accidental spending eats into money that was supposed to pay your electric bill.
Keeping all your cash in one pile guarantees you will eventually spend your rent money on groceries or an unexpected dinner out without even realizing you crossed a line.
We use a three-bucket system: bucket one holds fixed living expenses like rent and utilities, bucket two handles debt minimums and extra payments, and bucket three covers flexible weekly spending.
Separate your funds across different accounts at your bank so the physical temptation to pull from your bill money disappears completely.
If you fall short mid-month, fund buckets one and two fully before letting flexible spending take the hit.
Skip this structure if your pay lands more than twice a month; use a weekly cash envelope method instead if irregular income makes static buckets hard to maintain.
This mechanical separation removes willpower from the equation entirely, leaving your cash flow running smoothly on autopilot.
The Cash Flow Transformation
10. Avoid Common Payoff Pitfalls
What do you do when a $600 car repair lands right on the week you planned to drop an extra payment toward your balance?
The most common mistake is raiding the money you already earmarked for debt, promising you will replace it next paycheck. You rarely do, and the psychological momentum breaks instantly. I pulled from my payoff pile twice for minor emergencies, wiping out six weeks of hard work in ten seconds.
Leave your payoff cash untouched, and let a small separate buffer absorb the blow instead. This week, move your debt payment money into a restricted holding spot so you cannot accidentally spend it.
11. Automate Every Extra Transfer

You might worry that putting your extra debt payments on automatic pilot feels risky when your checking account balance is already tight.
Take a deep breath because you are not losing control by handing over the wheel; you are actually protecting yourself from your own exhaustion.
Relying on monthly willpower to manually transfer extra cash to your debt target fails nine times out of ten because life gets loud and busy.
By the time you remember to make the extra $150 or $200 transfer toward your principal balance, something else has already pulled at your attention.
Set up an automatic recurring transfer for the exact morning your paycheck lands so the money moves before you even see it in your spending balance.
End-of-month saving means you save whatever survived, and what survives is usually nothing after rent, groceries, and unexpected life costs.
Payday saving means the number is decided before the month gets a vote, delivering a completely different success rate across the year.
This is a timing fix, not a discipline fix, and it takes about four minutes to configure safely inside your mobile banking application.
Do it today and you never have to think about transferring funds manually again.
12. Reflecting on My Own Balance Transfer Mistakes
I thought balance transfer cards were a absolute magic bullet when I first consolidated $8,000 of credit card debt back in my twenties.
Moving that balance to a zero percent APR promotional card felt like an immediate victory, so I completely relaxed my daily spending habits instead of executing an aggressive payoff plan.
When the promotional window finally expired, I was left staring down a remaining $5,000 balance plus a steep 3% transfer fee that effectively swallowed whatever cash buffer I had managed to save.
The lesson was harsh: a transfer card buys you breathing room and stalls the interest clock, but it does not magically erase the underlying principal balance.
This week: if you are eyeing a balance transfer, calculate the exact payoff date before the rate jumps and set up auto-drafts to clear the principal entirely.
Our Top Payoff Priorities
13. Establish a Simple Envelope Habit
Digital spending makes money feel completely invisible until a transaction notification catches you off guard.
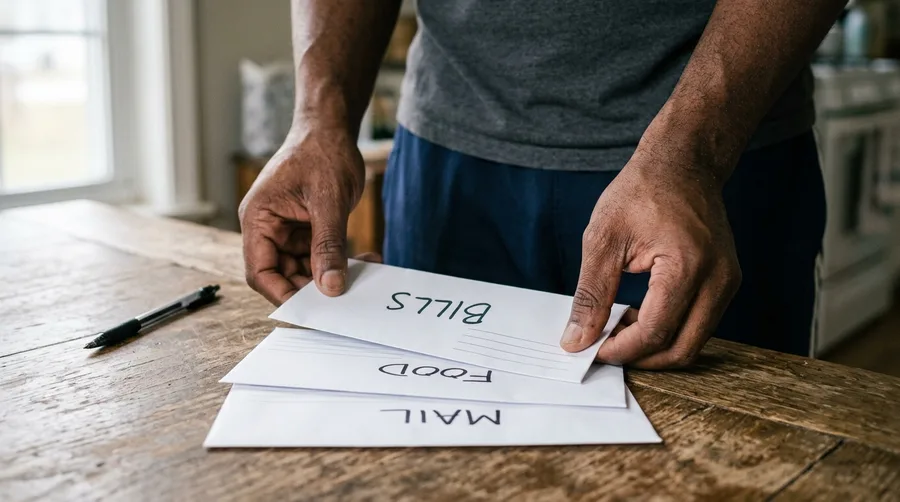
Cash envelopes slow down impulse purchases because handing over actual paper bills hurts our brains differently than tapping a plastic card. Allocate $100 a week for your highest-friction category like groceries or dining out, and leave the cards at home. I dropped my weekly discretionary spending by $40 the first month I tried this because holding the physical cash made every trade-off real.
This weekend, label three envelopes and fill them with your set cash limits.
14. Correcting Your Spending Triggers
Late-night cart filling is rarely about the items themselves and almost always about pure exhaustion or stress looking for an easy emotional exit.
The common mistake is trying to fight that late-night urge with sheer willpower alone when your defenses are completely drained. Delete every single shopping app off your phone today so checking out takes more than two taps, and give yourself a mandatory 24-hour cooling window before spending $40 or $60 on items you will likely forget by Tuesday.
It feels inconvenient, but removing that friction is the only thing that actually stops the cycle.
15. My Journey Out of Credit Card Debt
Stop letting the balance sit there while you try to calculate the exact optimal interest rate.
Carrying $18,000 in consumer debt made me feel like I was running uphill with a weighted vest for four straight years, and math alone was not enough to get me out.
The turning point came when I stopped trying to outsmart the spreadsheets and focused entirely on knocking out the smallest balances first to build momentum.
Seeing that first card hit a zero balance gave me the psychological fuel I needed to keep going through the harder accounts.
Reaching debt freedom did not happen overnight, but building a repeatable system made every paycheck feel less stressful until the balance finally hit zero.
Frequently Asked Questions
Is it too late to start paying off debt if I am over 40?
It is never too late to take control of your cash flow. Starting at 40 simply means focusing heavily on high-interest balances and maximizing employer retirement matches simultaneously.
Should I pay off debt or save an emergency fund first?
Build a starter emergency fund of $500 to $1,000 first so unexpected car repairs do not instantly push you back into new credit card debt. Once that cushion exists, pivot all extra funds to your debt payoff plan.
Should I pause my retirement contributions while paying off debt?
Only pause contributions if you are facing severe financial distress, and try to keep at least your employer match if one is offered. Stopping retirement savings entirely for a short debt sprint is a personal choice, but weigh the lost compounding time carefully.
How do I choose between the debt snowball and debt avalanche methods?
Choose the snowball method if you need psychological wins to stay motivated, or the avalanche method if you want to minimize total interest paid. Both work if you stick with them consistently.
Your First Step This Week
You do not have to overhaul your entire financial life by Friday afternoon.
Pick just one small account off this list, set up an automatic transfer for your next payday, and let momentum take over from there.
