
You sit at the kitchen table on a Tuesday night staring at an online bank portal, wondering where the last paycheck went.
It feels heavy, like you are failing a test everyone else studied for.
The truth is simpler and kinder: willpower is a terrible system for managing money.
When you rely on remembering to transfer funds every two weeks, you are betting against exhaustion.
Systemizing your cash flow removes the daily negotiation with yourself entirely.
Quick Tips Before You Start
Separate Banks
Keep your savings at a completely different institution than your checking account.
Align Paydays
Schedule all automated transfers for the morning after your direct deposit hits.
Audit Once
Cancel recurring subscriptions before you set up any permanent routing rules.
1. Split Your Direct Deposit at the Source
Most people wait for money to land in their checking account before trying to save whatever is left over.
That approach treats saving as an afterthought, which means you save whatever survived the month and nothing survives.
The mechanism is straightforward: routing a set percentage straight to savings before you ever see it bypasses temptation completely, removing willpower from an equation where willpower usually loses.
Ask your payroll department to split your direct deposit so that 10 percent goes directly to a separate high-yield savings account that sits at a completely different bank.
If your employer does not allow split deposits, set up an automatic transfer for the exact morning your paycheck clears, and give yourself about two pay cycles to adjust to living on the remaining balance.
💡 Tip: Start with just 3 percent if 10 feels too steep today.
⚠️ COMMON MISTAKE
The Checking Account Trap
Leaving your entire paycheck in one primary checking account is an invitation to spend money that was meant for bills or savings.
2. Automate Every Single Fixed Bill
It is easy to beat yourself up when a late fee hits because a due date slipped past while life was loud.
That oversight costs the average household hundreds of dollars every year in penalties without a single thing to show for it.
The fix is to route every recurring utility, insurance policy, and loan payment to autopay on the exact same morning each month, keeping a $500 buffer in that checking account to stop accidental overdrafts.
Do that this afternoon and let the software handle the calendar.
Autopay Setup — At a Glance
⚡ Frequency
Monthly
🛡️ Buffer Target
$500 minimum
⏰ Timing
2 days post-payday
Core Rule
Never autopay variable credit card balances in full without checking the statement first.
3. Build a One-Month Buffer Zone
$4,000 sitting in a checking account that you do not touch is the exact line between surviving a month and finally breathing.
Living paycheck to paycheck keeps your nervous system in a low-grade state of constant panic. When you are always spending money you earned last week, every single unexpected expense feels like a catastrophe waiting to drop.
The goal here is simple: break the cycle by building a buffer so you are paying this month's bills with last month's income. For a household spending $4,000 a month, that means accumulating a $4,000 cushion over several pay periods, keeping it entirely separate from your everyday spending so you are never tempted to pull from it for groceries.
It takes time, and it requires cutting discretionary spending temporarily. I spent two agonizing years living on the edge before I finally built that buffer, and the psychological relief was honestly worth every single sacrifice along the way.
If one month feels completely impossible right now, give yourself permission to scale it back without quitting altogether. Aim for two weeks of basic expenses first and let yourself catch your breath before you worry about the rest.
Even setting aside $50 from your next paycheck gets the engine moving.
This week, open a separate savings account at a completely different bank, label it the buffer fund, and move your first small slice into it.
💡 Tip: Park this buffer in a separate high-yield savings account so you are not tempted to spend it.
Buffer Account Rules
4. Accept the Trade-Offs of Automation
Is automation really as effortless as people claim?
The honest answer is no, because setting up the system takes about three frustrating hours of remembering passwords, linking accounts, and double-checking routing numbers. You also lose a noticeable slice of daily spending flexibility since roughly 70 percent of your paycheck is sequestered before you even see it.
That rigidity is the exact feature that makes the system work.
Spend twenty minutes this weekend logging into your primary bank portal to map out your fixed transfers.
🚀 Your 90-Day Automation Roadmap
Month 1
Set up direct deposit split and core bill autopays.
Month 2
Build your initial one-month buffer zone.
Month 3
Conduct your first quarterly review and scale up.
5. Establish a Three-Bucket Cash Flow System
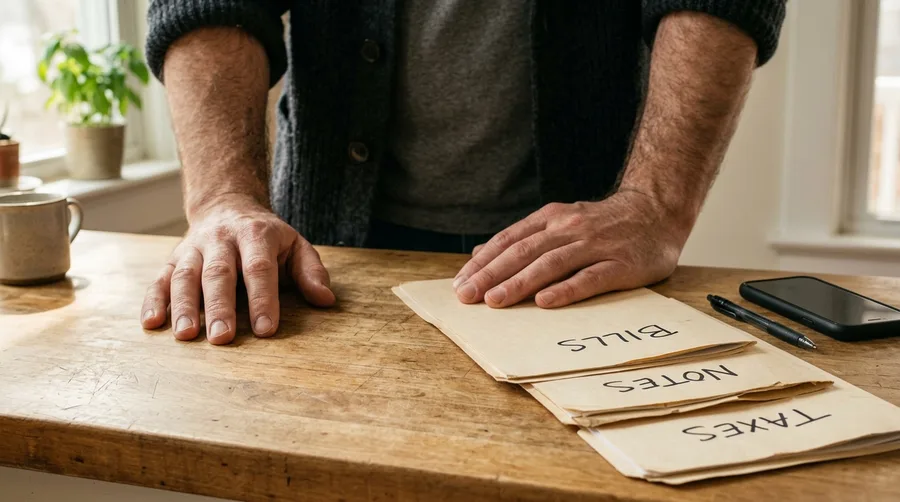
Looking at one giant checking account balance gives you a false sense of security until you realize your rent payment is due in three days.
Managing all your money in a single pile makes it nearly impossible to track where your actual priorities stand, leaving you guessing whether that grocery run will bounce.
Divide your cash flow into three distinct digital buckets: fixed bills, debt minimums, and flexible spending, so your money has a job the second it lands.
Bucket one covers housing, utilities, and insurance, while bucket two handles minimum debt payments automatically.
Bucket three is what you have left for groceries, gas, and fun, and this simple architecture keeps you from accidentally spending your rent money on weekend takeout.
Log into your banking app this afternoon and open two additional savings accounts to use specifically as your first two buckets.
💡 PRO TIP
Naming Your Accounts
Rename your digital sub-accounts with specific labels like 'Property Tax' or 'Car Repair' so you instantly know what the money is reserved for.
6. Start Small With the Twenty-Dollar Floor
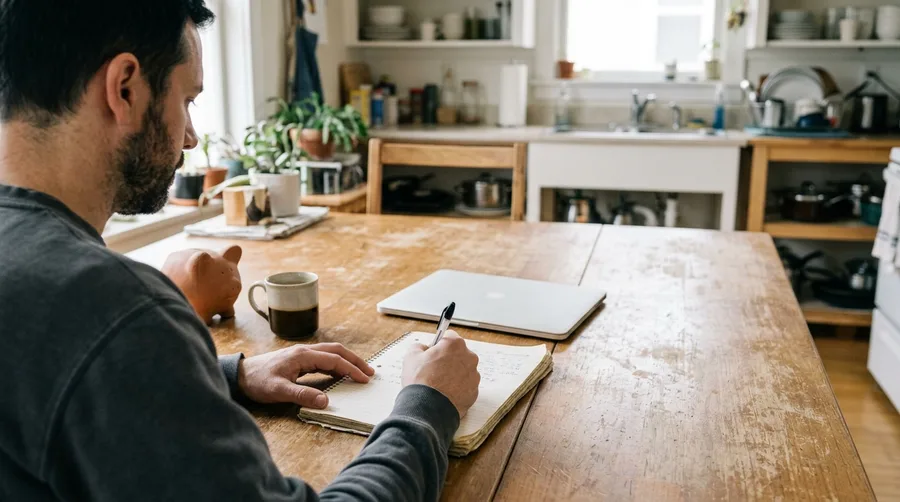
I kept putting off opening a savings account because my budget only had fourteen dollars left over at the end of the pay period, and saving fourteen dollars felt like a joke.
That is the paralysis talking.
People stall out on building a cushion because they assume that if they cannot stash away five hundred dollars every single month, the effort is entirely pointless.
The mechanism of consistency relies on a simple behavioral truth: starting tiny builds the routing habit before your income ever catches up to your ambitions.
Even twenty dollars a month, moved automatically into a separate account, creates a baseline rhythm that compounds over time without demanding daily willpower.
Set up a tiny automatic transfer today, even if it feels completely insignificant right now, and scale it up by ten dollars every three months as your cash flow loosens up.
Willpower vs. Systemization
Willpower Approach
- Trying to remember to save every payday
- Checking account balances with anxiety
- Relying on discipline when stressed
- Saving whatever is left over
Automated System
- Transfers happen without your input
- Checking accounts hold only bill money
- Systems remove daily decision fatigue
- Savings happen before spending starts
7. Rebuilding My Finances After a Rough Year
Stop trusting your willpower to save money after a bad year.
When my car broke down and medical bills piled up at the same time, my savings account dropped straight to zero. I sat at the kitchen table staring at the statements, realizing that relying on daily discipline alone was the exact reason I kept failing.
I finally spent an entire Saturday setting up automated transfers for every single bill and savings goal, removing my own ability to interfere with the money before it hit the right accounts.
Within twelve months, that single afternoon of setup tripled my total savings rate, moving my balance from a stressful absolute zero back up to $4,500 without me having to make a single hard choice on payday.
Block out two hours this weekend to automate your core transfers so your savings grows on autopilot.
Automation Impact Factors
8. Consult a Professional for Complex Portfolios
There always comes a point when a generic spreadsheet or a basic automated transfer is simply no longer enough to handle your money safely as your financial life moves forward and your goals inevitably change over time.
Automating basic cash flow is straightforward and essential for daily survival, but advanced tax strategies, capital gains planning, and multi-account retirement investments require personalized guidance that generic online articles simply cannot provide for your unique household.
When your net worth grows past your early milestones or your tax situation becomes genuinely complex, schedule a single session with a certified fee-only fiduciary who is legally bound by ethics to act solely in your best interest.
They review your specific numbers and accounts thoroughly without trying to sell you proprietary investment products or locking you into hidden advisory commissions that slowly drain your long-term returns over decades of steady compounding.
Hiring expert help costs real money, often ranging from $150 to $300 an hour for a targeted review, which can definitely sting when you are used to managing every single dollar on your own kitchen table without outside interference.
You certainly do not need this level of professional depth for a basic paycheck and a standard emergency buffer, so do not rush into paying for consultations before your financial life actually demands that extra layer of complexity.
Keep your automated foundation running smoothly in the background while you gather your tax documents and recent account statements, and then book a single consultation to get expert input on the tricky details that trip people up.
9. Beat the Deadline on Retirement Contributions
That nagging feeling in the back of your mind about retirement savings usually hits hardest when the year is almost over.
Waiting until December to fund your account means missing out on months of potential compounding growth, where your money earns returns on itself. Spreading your investments across twenty-four pay periods instead of one lump sum also smooths out market volatility so you are not buying at the absolute peak.
Take four minutes today to log into your portal and bump your contribution percentage up by one percent.
10. Take the Willpower Out of Your Spending
You are not weak-willed because you bought something you did not plan for.
The entire digital retail ecosystem is built to bypass your rational brain in about three seconds.
Delete your saved credit card numbers from every single shopping app and browser profile right now.
Adding even thirty seconds of manual card-typing friction gives your nervous system time to settle down and ask if you actually need the item.
Combine this with automated savings that move cash out of your checking account the morning payday hits, so the temptation simply is not there to begin with.
11. Review Your System Every Quarter
Open your calendar right now and schedule a recurring reminder for every ninety days.
An automated financial system is not a kitchen appliance that runs forever without maintenance.
Life changes faster than your bank rules do, and a setup you built a year ago might be starving your current goals.
When the quarterly alert pops up, spend twenty minutes auditing three specific things: your active subscriptions, your current savings percentage, and any recent pay increases.
Insurance companies love to quietly raise policy rates by 10 percent after the first six months, assuming you will not notice the difference on autopay.
Streaming services and internet providers do the exact same thing with promotional pricing that quietly expires.
Catching those creeping price hikes during a quarterly review stops hundreds of dollars from leaking out of your flexible spending bucket every single year.
If you got a 3 percent raise last month but your automated transfer to savings stayed at the old dollar amount, you just absorbed that extra cash into lifestyle inflation without realizing it.
Tune the numbers upward by at least 1 percent every quarter to capture that raise before you get used to spending it.
Keeping your system synchronized with your actual income ensures your financial growth finally keeps pace with your real life.
12. Overcome the Scarcity Mindset Trap
For three full years, I stared at a checking account balance hovering under $150 every single Tuesday before payday.
That kind of constant financial pressure convinces you that you are fundamentally bad with money, which stops you from building any system at all.
What I believe now is simpler: mechanics beat worry every time. Set up a transfer of just $15 today, let the automation handle the heavy lifting, and watch how quickly your outlook shifts when the math finally starts working for you.
13. Track Your Net Worth Monthly
Am I actually making any progress, or am I just spinning my wheels while the bills keep coming?
Checking your bank balance every single day feels like watching paint dry while random expenses bounce the total up and down. That daily noise creates a low-level hum of anxiety because everyday transactions make the chart look like a chaotic roller coaster that tells you nothing about your actual trajectory.
Set a calendar reminder for the first of every month to log your total assets and liabilities in a basic spreadsheet. List everything you own in one column and every debt in another, subtract the second from the first, and leave the document alone for thirty days.
I used to check mine weekly and panicked every time a minor car repair dipped the balance, which completely missed the point of tracking. The real shift happens when you look at a six-month trend line and realize the trajectory is climbing upward despite the messy individual weeks.
Open a blank sheet tonight, put today's date at the top, and write down your two core totals to start your baseline.
14. My Biggest Automation Mistake
When I first tried automating my savings, I set the transfer amount to $500 a week and wiped out my checking account within two weeks.
I had to scramble, reverse the transfer, and pay a $35 overdraft fee because the math in my head did not match my actual cash flow rhythm.
Start conservative with your automated amounts and scale up by $25 a month as you learn what your account can actually handle without breaking.
A sustainable system beats an aggressive one you have to cancel.
15. Lock in Your System Before Friday
The biggest myth in personal finance is that reading enough articles will eventually train your brain to execute good financial habits without needing any structural support behind them.
It always fails because willpower is a genuinely finite resource that completely evaporates by Thursday afternoon when you are tired, busy, and just trying to get through the work week without extra stress.
When you rely on daily motivation to save manually, you are fighting your own psychology every single month and usually losing the argument against convenience and immediate comfort.
Automation bypasses that friction entirely by treating your savings like a non-negotiable fixed bill that leaves your checking account whether you feel disciplined on any given Tuesday or not, letting you build a cushion in the background.
Take twenty minutes to log into your bank portal right now, set up one recurring transfer of $50 for the exact morning your paycheck lands, and lock in your new system before Friday arrives.
Frequently Asked Questions
Is it too late to start automating my finances at 40?
It is never too late. Setting up automated savings and bill pay immediately reduces financial stress and accelerates your savings rate, regardless of your age.
How much should I have in my emergency fund before investing?
Aim for one month of bare expenses first, then build toward three to six months in a high-yield savings account before locking money into long-term investments.
Should I pay off debt or save first?
Build a small one-month buffer first to stop the cycle of new debt, then tackle high-interest consumer debt while maintaining a modest automated savings habit.
Is it okay to pause my automated savings for a month?
Yes, life happens and unexpected expenses arise. Adjust your automated transfers downward temporarily, then restart them as soon as your cash flow stabilizes.
Start With This One Transfer
You do not need to overhaul your entire financial life by Friday afternoon.
Pick one move from this list, open your banking app, and set up your very first automated transfer right now.
Consistency and systems will carry you much further than willpower ever could.
