
Whether your monthly take-home is ₹15,000 or ₹1.5 lakh, those same six months can reshape where your money ends up. It won't happen by suddenly earning more, but by finally seeing it clearly.
Most people are not bad with money. They are just busy. Rent leaves, an EMI leaves, Swiggy leaves, a subscription you forgot about leaves, and nobody is writing any of it down. That is the whole problem in one line.
So here is the deal for the next six months. One job per month, done in order. By the end you will know where every rupee goes, have a buffer in the bank, a plan for your loans, money in index funds, a health and term policy, and a system that runs without you remembering anything.
The example running through this whole plan is a ₹60,000 monthly take-home: ₹30,000 on needs, ₹15,000 on wants, ₹15,000 not really accounted for. Slide your own numbers into the same slots.
Quick Tips Before You Start
Log it at the moment
Record the payment when you make it, never at month-end when the ₹17 UPI is a mystery.
Three buckets only
Needs (rent, EMI, food, utilities), Wants (clothes, parties, gadgets) and Investments. No fourth pile.
Cut the ghost debits
A gym membership you have not used in three months is the easiest money you will ever find.
Give yourself two minutes a night
A nightly entry habit beats a heroic spreadsheet session on the 30th.
Slow is fine
If the buffer takes three months instead of one, nothing is broken. Going hungry to hit a number is.
1. Month 1: The Expense Audit
Start with the boring month, because everything else in this plan leans on it. For 30 days you log every single payment the moment it happens – UPI, card, cash, EMI, auto-debit – not at month-end. You will not remember what that ₹17 UPI on the 21st was for, and honestly, neither would anyone else.
Use whatever app you will actually open: ETMoney, Money Tracker, Money Manager, Walnut or Cred on your phone, or a plain spreadsheet if old-school suits you. The tool does not matter. The consistency does, because a tracker you abandon on day nine tells you nothing about where your money went.
If most of your spending is cash, add a wallet log you update at night and reconcile the wallet against your notes every Sunday. Cash is where money disappears quietly – a chai here, a auto fare there – and those small untracked notes are often why the month-end total feels wrong.
At month-end, split everything into Needs (rent, EMI, food, utilities), Wants (clothes, parties, eating out, gadgets) and Investments. Investment can be zero this month, and that is fine. Then mark the surprises in both directions: ₹4,000 on delivery apps when you assumed ₹2,000, or a subscription auto-debit you forgot existed – and note which wants can be trimmed next month.
💡 Tip: Separate one-time wants (a phone) from monthly ones (delivery apps). A big purchase month should not make you panic about your regular spending.
⚠️ COMMON MISTAKE
The Ostrich Trap
Looking away does not remove the danger. One month of honest tracking is uncomfortable for about three days and useful for the next thirty years.
2. Month 2: The First Safety Net

Where Month 1 was about seeing, this one is about building – and the tool here is a bucket, not a budget cut. Picture a trapeze artist: the swing is the fun part, but nobody performs without the net underneath. Your net is one month of needs sitting in your savings account.
In our ₹60,000 example, needs come to ₹30,000, so the target is ₹30,000 available at any point. Not invested, not locked in a fixed deposit you cannot touch at 11 p.m. – just there. If ₹12,000 is your needs figure instead, then ₹12,000 is the number you are chasing.
Fund it from the wants you flagged last month: the unused gym debit, the extra delivery orders, the two streaming subscriptions you barely watch. Find more fixed expenses to cut without touching food, rent or the car payment. This is a temporary trim, not a vow of poverty. You are not banning fun, only redirecting it for a month or two.
And if ₹30,000 in one month means skipping meals, take three months instead. Essentials stay. A buffer built by starving yourself is not a buffer, it is a different problem wearing the same name.
| Month | Main move | Target or checkpoint |
|---|---|---|
| 1 | Expense audit: log every rupee, sort into needs, wants, investments | Zero investment is fine; find the surprises |
| 2 | Build the first safety net | One month of needs, e.g. ₹30,000 in savings |
| 3 | Loan cleanup, or grow the emergency fund | Credit card (₹40,000 at 36%) first, then the personal loan; fund ₹90,000 or ₹1,80,000 |
| 4 | Start investing and buy insurance | 30% safe assets at age 30, 70% into Nifty 50 and Nifty Next 50 index funds; ₹1 crore term to age 60 |
| 5 | Increase income | ₹5,000-₹10,000 a month extra from one route, 90-day checkpoint |
| 6 | Automate everything | Bills, SIPs, EMIs and premiums on fixed dates just after income lands |
3. Month 3: The Loan Cleanup
It is the evening the card statement arrives, and the minimum due looks so reasonable that you almost pay it and close the app – except now you know your spending and you have a net, which means the loans stop being background noise. Write down every one: card balances, personal loans, your mortgage, student loans, the BNPL you keep forgetting.
Now split them. Good loans build something that can earn for you – education and home loans, usually under 10%. Bad loans fund things that lose value or earn for someone else: car loans, personal loans for gadgets or groceries, credit cards at 35-40%, loan apps at 28-60%. Personal loans sit around 14-15%.
Sort the bad loans by outstanding amount, smallest first, and clear them one at a time. That is the snowball method, and it works because each cleared loan feels like a win. In our example, you attack the ₹40,000 credit card at 36% before the ₹2,00,000 personal loan.
The catch: this can take years, and that is fine. Borrowing or trading to speed it up is how a manageable debt becomes an unmanageable one – a ₹50 lakh mix of education, home and failed business debt cleared over 12 years is the slow version that actually works. No loans at all? Then grow the fund to ₹90,000 on a stable salary, or ₹1,80,000 if your income is freelance or irregular.
💡 Tip: Good loans can run long. Bad loans get attacked. Do not confuse the two on a spreadsheet and start prepaying your home loan while the card balance compounds at 36%.
Good Debt vs Bad Debt
Let it run
- Rate below roughly 10%
- Interest may be tax-deductible – check Section 24(b) for home loans
- Never prepay before the emergency fund is full
- Education loan: pay only the interest while studying
Clear it fast
- Rate above 10%: every spare rupee goes here
- Credit card first in our example: ₹40,000 at 36%
- Then the ₹2,00,000 personal loan at 14-15%
- Moving it to a 0% balance transfer still costs a 2-3% fee – read the fine print
4. Month 4: Investing and Insurance

This is where it finally changes. After three months of tracking, trimming and loan triage, you have a number you can commit each month without guessing.
Your automated deductions – EPF, and NPS or PPF if you have them – already form the safe base, roughly 7.5%. Keep them going, but do not try to maximise them. They are the floor, not the whole plan.
Then split your investment amount by age. A simple rule: the percentage equal to your age goes into safer assets such as debt funds, gold or REITs – so a 30-year-old puts 30% there and 70% into equity. Start that equity in Nifty 50 and Nifty Next 50 index funds, and compare them on expense ratio and tracking error before you pick. Leave mid- and small-cap funds for later, once you have watched a few months of volatility without panic-selling.
Insurance is the other half of this month. Buy a separate family health policy for yourself, your spouse and children, and another for your parents – do not rely only on employer cover, because leaving that job lapses it and resets your waiting periods.
For life cover, take term insurance to age 60: ₹1 crore cover at the lowest possible premium you can find. Return-of-premium and endowment plans charge far more for the same protection, and you can check that gap yourself on an aggregator like Policybazaar before you sign anything.
5. Month 5: The Income Boost
Once you have squeezed your expenses as far as they can reasonably go, the only lever left is the other side of the equation. You can only trim so much before life stops being worth living, so this month you go the other way, and there is no ceiling on income.
Pick one route, not five. A raise at your current job, a job change, a freelance service built on skills you already have, tutoring, a digital product, part-time consulting, or rent from a room or asset you are not using. The fastest to test is usually a raise conversation or one freelance service you can offer this week, so start there rather than signing up for everything at once.
Here is why this feels different from every other money task. Your expenses are now balanced, so anything extra is straight profit. Add 5,000-10,000 rupees a month and none of it gets eaten by new costs, which means you get to split it, some to actually enjoy and some invested. Spend the whole raise on a bigger car and you have just recreated the problem you spent four months solving.
Expect it to take longer than a month, so budget time and money for skill-building. Book a course if a specific skill is the gap, and set a 90-day checkpoint. If the raise conversation or the freelance gig has not produced money by then, change route rather than repeating the same attempt and hoping this time is different.
📅 The Six Months, Start to Finish
Month 1
Log every expense as it happens and sort it into needs, wants and investments.
Month 2
Build one month of needs as a buffer in the savings account.
Month 3
List all loans, separate good from bad, clear the smallest bad one first.
Month 4
Start index fund SIPs by age split, and buy health and term insurance.
Month 5
Add ₹5,000-₹10,000 a month from one income route, with a 90-day check.
Month 6
Automate bills, SIPs, EMIs and premiums on fixed dates just after income.
6. Month 6: The Automation Setup
You replace willpower with a system. Because let's be honest about how month seven usually goes: the plan ends, the motivation fades, and by the second week you're back to checking your balance before every swipe.
Automation quietly takes out the two things that wreck good intentions – discipline and mood. Set your bill payments, SIPs, EMIs and insurance premiums on fixed dates and they happen whether you feel inspired or not. No waiting for the market to dip before you invest. No deciding to put in whatever is left at month-end, because we both know something never is.
But automation without visibility is just a subscription to confusion. Build one calendar or dashboard that shows what leaves your account, on which date, and why it leaves. That is the difference between control and guesswork – the people who handle money well aren't careless with it, they just know exactly where it goes and when.
Start with three payments, not eleven. Each one needs a fixed amount and a date you can review monthly, so something like your rent or home EMI, one utility, and one index fund SIP is a perfect first set. Fixed amounts matter here because a variable bill you haven't mapped can slip past the balance sitting in that account.
Take the ₹60,000 example: rent or EMI at ₹12,000 on the 5th, electricity at ₹1,800 on the 7th, SIP at ₹10,000 on the 10th. Assume salary lands on the 1st, so everything clears with days to spare. Run it for one month, watch it work, then add the next batch.
💡 Tip: Pick a debit date 2-3 days after your salary or a confirmed client payment lands, never the same day, so a late credit does not bounce the payment.
Automate Without Overdrawing Your Account
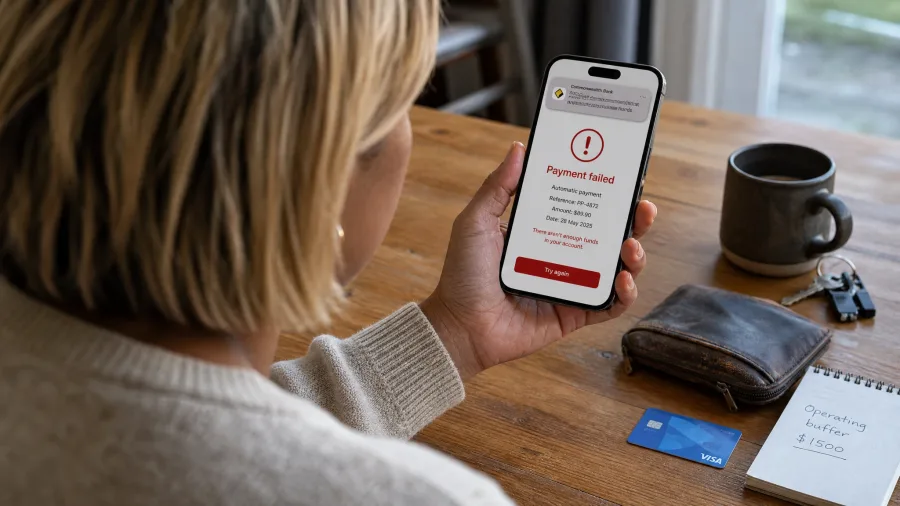
Here's the catch nobody warns you about: automation only helps if the money is actually sitting there when the debit fires. So before you set a single date, map your income dates against your debit dates. If salary lands on the 3rd, don't schedule a SIP for the 1st – move non-critical SIPs and bills a few days later, after a confirmed salary or client payment has come in. Once the dates line up, learn how automating every financial decision removes willpower from the equation altogether.
Second, keep a small operating buffer in the account that handles auto-debits. About one week of needs – around ₹7,000 in the ₹30,000-needs example – and keep it separate from your emergency fund. That cushion absorbs a late salary or a slightly higher electricity bill without a bounce and the charges that come with one.
Then stay awake. Turn on alerts for every auto-debit and do a two-minute weekly check of that account. If a payment fails, pause the next discretionary SIP before you reach for new debt.
And when cash is genuinely tight, protect rent, EMIs, utilities and insurance first. Pause the investment SIPs, then restart them once the buffer is back to ₹7,000.
Frequently Asked Questions
Do I need a budgeting app to do this 6-month financial plan?
No. A spreadsheet works, and cash spenders can keep a wallet log with a Sunday reconciliation. What matters is logging at the moment of payment, not the tool you pick.
What if I cannot save a full month of needs in Month 2?
Take two or three months and trim wants, not essentials. Skipping meals to hit a number is the wrong trade – the buffer is meant to reduce stress, not create it.
Should I clear loans or build the emergency fund first?
Do both in order: the starter buffer in Month 2, then loans and a bigger fund in Month 3. If you have no loans at all, push the fund to ₹90,000 on a stable salary and ₹1,80,000 if your income is irregular.
How much should a 30-year-old put into index funds?
Roughly 70% of the investment amount into equity, starting with Nifty 50 and Nifty Next 50 index funds, and 30% into safer assets like debt funds, gold or REITs. That safe share should rise as you get older.
For pure protection, yes. Term gives the highest cover for the lowest premium. Return-of-premium and endowment plans cost noticeably more for the same cover – check the quotes side by side on an aggregator before deciding.
What is the smallest useful income boost in Month 5?
₹5,000-₹10,000 a month from one route – a raise, a job change or a single freelance service. Because your expenses are already balanced, that amount is close to pure profit to invest or enjoy.
Month 6 Is Not the Finish – It Is the Handover
Six months of small, boring, repeated actions is what separates people who control their money from people who hope. Nothing here needed a windfall, a hot tip or a shortcut.
When the six months end, the plan stops and the system takes over: dated debits, a visible dashboard, a buffer sitting quietly in the account, and a reason written down for every outflow.
Your next action is one item long. Open your banking app now, pick the first payment to automate – rent, EMI or one SIP – and set its date two or three days after your salary lands.
Revisit that calendar at the end of the month. If a loan payment is competing with your safety net, the loan can wait a cycle. If your income is irregular, keep the buffer at six months of needs before adding anything new.
Set One Date Today
Open your banking app, pick the first bill or SIP to automate, and schedule it two or three days after your income arrives. That single date is Month 6 done.
