
You hear about ordinary earners retiring with massive portfolios and assume they gambled on a perfect stock, while your own steady contributions feel like they barely move the needle.
The reality is completely unglamorous.
The engine behind a seven-figure balance is almost never a brilliant trade, but a mundane setting inside a standard brokerage app. True wealth builds when the cash a fund pays out goes straight back into buying more shares of that exact same fund.
Putting those payouts back to work without lifting a finger accelerates standard gains into massive momentum. Here is the math behind that compounding gap, and the exact clicks needed to turn the machinery on.
| Timeframe | Taking Cash | Reinvesting (DRIP) |
|---|---|---|
| 30 Years | $415,000 | $650,000 |
What Is a DRIP?
A Dividend Reinvestment Plan catches the cash a stock pays out and immediately uses it to buy more of that exact same stock.
It runs entirely in the background.
Instead of letting those quarterly payouts sit idle in a settlement fund, the system automatically sweeps them back into the market. You do not have to log in, you do not have to place a manual trade, and major brokerages charge zero fees for the service.
The system buys fractional shares right down to the decimal point, which means every single cent of the payout goes straight to work.
A lot of investors let small dividends sit uninvested because a $14 payout cannot purchase a whole share of an expensive index fund. The automatic plan ignores the share price entirely and simply hands you the exact fraction that your cash is worth.
Nothing gets left behind.
Setting it up takes about three clicks in the account preferences menu, and then the cycle repeats itself for decades.
The Terms to Know
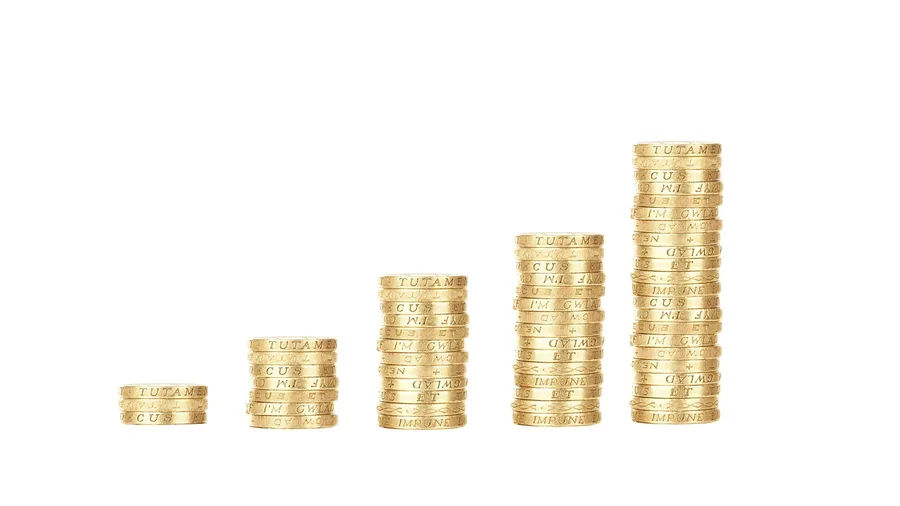
Every sliver of a share you automatically acquire starts generating its own payout. Those tiny pieces set off a compounding loop that quietly builds momentum over decades.
Look at the math of a standard setup. You start with a $10,000 initial investment and add $500 every month. Assume a broad fund that averages a 5% bump in stock price appreciation and pays a steady 3% dividend yield.
If you take those quarterly payouts in cash, a 30-year timeframe of steady contributions gets you to a final portfolio value of approximately $415,000.
That is a perfectly respectable result.
But leaving the cash in the account changes the math entirely. Reinvesting that money over three decades means the new fractional shares you buy today start generating their own 3% yield tomorrow. The payouts buy more shares, which produce larger payouts, which buy even more shares.
The cycle accelerates silently in the background of the account.
Automating the purchase pushes that final balance to approximately $650,000. You put in the exact same amount of capital, but the automated reinvestment creates a massive $235,000 gap.
The $235,000 Difference
Assumes a 30-year timeframe, 3% yield, and 5% appreciation.
The Tax Bill Still Comes Due
The IRS tracks that compounding chain reaction and taxes the reinvested dividends as regular income in the exact year they are issued.
The government considers the dividend paid the moment it hits your brokerage, even though the automated system immediately uses it to buy more stock. Because the cash never actually touches your checking account, this rule often catches new investors completely off guard at tax time.
The account type dictates how you handle it.
Activating this strategy inside a tax-advantaged space like a Roth IRA or a traditional retirement account completely shields those annual payouts from immediate taxation. You can leave the automation running in the background for decades without ever having to report the internal math on your yearly tax return.
Running the exact same setup in a standard taxable brokerage account creates a different reality.
You have to keep outside cash available in your regular bank account to cover the tax liability on those reinvested amounts. The broker will send a 1099-DIV form in early spring listing the total dividends you earned, and you will owe taxes on money you cannot easily spend.
It is a trade-off for the growth.
The Container Rules: Caps and Access
Taxable Brokerage
- Fully liquid: pause the DRIP or sell shares at any age without penalty
- Uncapped space: handles the full $500 monthly with zero IRS maximums
- Rate tiers: most U.S. stock dividends qualify for the lower 15% bracket
- Best for: early retirement bridges or timelines shorter than 20 years
Tax-Advantaged (IRA / 401k)
- Age locked: cashing out the growth before 59½ triggers a 10% penalty
- Deposit ceilings: annual IRS limits restrict how fast the balance scales
- Mandatory exits: traditional accounts force withdrawals starting at age 73
- Best for: the core 30-year compounding timeline where growth matters most
Flipping the Switch in Your Brokerage
Knowing exactly how the tax bill works means you are clear to actually log in and turn the machinery on.
Finding the button takes under two minutes.
Nearly all modern brokerage platforms park this setting slightly out of sight, usually under account preferences or individual position details. You are looking for a simple toggle next to your core dividend ETF that asks what to do with payouts, and you want to flip it to reinvest.
The major brokers run these fractional purchases completely for free.
They skip the standard trading fees and commissions because the system handles the math automatically, dropping those fractional slices straight into your portfolio without human intervention.
That automation provides an unexpected protective layer.
Taking the manual work out means you never have to log in on a bad Tuesday to manually enter a buy order. When the market turns ugly, keeping your hands off the keyboard prevents the emotional urge to hoard cash.
Setting it up today saves you from making bad choices during the next panic.
⚙️ Automating the Process
Log In
Open your brokerage account on a desktop browser for the easiest navigation.
Locate Settings
Search for 'Dividend Reinvestment' or check the preferences under your specific positions.
Select Funds
Check the box next to the broad index funds you want to automate.
Confirm
Save the changes and let the brokerage handle every future quarterly payout.
That distance from the daily market noise turns a terrifying drop into an active mathematical advantage.
Red numbers actually speed up the strategy.
Combining a steady $500 monthly contribution with an automatic reinvestment plan enforces strict dollar-cost averaging over thirty years. You are buying the exact same asset on a rigid schedule, regardless of whether the index is hitting all-time highs or dropping fast in the middle of a bad quarter.
A sudden crash directly lowers the share price.
Because the cash dividend payout remains relatively fixed during a dip, that same amount of cash now purchases a significantly larger fraction of shares. The exact same yield suddenly buys more property.
This is how the system rewards a boring approach.
When the market eventually recovers and share prices appreciate again, those additional, cheaper fractional shares lower the average cost basis of the entire portfolio. You own more pieces of the fund, and you bought those extra pieces on clearance.
The math works precisely because the reinvestment happens automatically while everyone else is freezing in panic.
A market drop lowers the share price, meaning your fixed cash dividend automatically purchases a larger fraction of shares.
— The exact math of dollar-cost averaging
When to Finally Take the Cash
That massive accumulation of shares eventually hits a ceiling where growth gives way to needing actual cash to live on.
You do not leave this running forever.
A dividend reinvestment plan strictly serves the wealth accumulation phase of life. It exists entirely to maximize your total share count over decades of working years, turning an initial $10,000 investment into a massive pile of assets you can eventually draw from when you stop working.
Retiring changes the math entirely.
Leaving the workforce shifts your main priority from aggressive wealth accumulation straight over to wealth preservation. The portfolio must now generate the living expenses that your regular paycheck used to cover.
The exit strategy takes exactly one click.
Switching the setting to 'off' at retirement immediately converts the asset into a steady stream of passive cash income. The underlying shares remain untouched in the account, but the payouts finally start flowing straight to your checking account to buy groceries.
The $235,000 gap you built by reinvesting all those years now acts as the foundation for your retirement.
💡 PRO TIP
The Retirement Pivot
Turn off the DRIP one to two years before you actually retire. That builds up a cash buffer so you aren't forced to sell shares in a down market.
Frequently Asked Questions
Does a DRIP cost money to run?
No, nearly all major brokerages process automated dividend reinvestments for free without charging trading commissions.
The brokerage will purchase a fractional share. If the stock is $100 and your dividend is $10, you automatically buy 0.1 shares.
Can I choose to reinvest only some of my dividends?
Yes, you can turn the DRIP on for specific funds or stocks in your portfolio while letting others pay out in cash.
How do I track my cost basis with a DRIP?
Your brokerage tracks the cost basis of every fractional purchase automatically, so you do not have to calculate it yourself at tax time.
The Next Five Minutes of Your Wealth Plan
Open a new tab, log into your brokerage account, and locate the dividend reinvestment settings for your core index funds. Change that toggle to 'on'.
That single switch is the actual boring secret behind millions of seven-figure balances. The hardest part of the entire strategy is simply leaving the account alone to compound for thirty years.
You never needed to find the perfect winning stock. You just needed to let the machine run.
Check Your Brokerage Settings Today
Log in and verify that your core index funds have dividend reinvestment turned on.
