
You sit at the kitchen table on a Sunday night, staring at a banking app that seems to empty itself faster than it fills. The monthly bills are paid, but the account balance feels suspiciously light given how little you actually bought.
It is easy to blame the large purchases or the occasional weekend dinner, but the real financial drain usually hides in plain sight.
When I finally committed to writing down every single transaction for ninety straight days, I expected the culprit to be takeout or online shopping. I was completely wrong.
This guide walks through the actual mechanics of a spending audit, what leaks to look for, and how to fix your cash flow without living on a strict, miserable diet of nothing.
Quick Tips Before You Start
Write Everything
Capture every single purchase for thirty days straight without judging the totals.
Separate Accounts
Move fixed bills into a dedicated checking account so they never mix with spending money.
Automate Payday
Set transfers to happen the exact morning your paycheck clears.
Cut One Thing
Cancel a single unused subscription today rather than planning to do five later.
1. The Reality Check of Manual Tracking
Four hundred dollars vanished from my checking account every single month without a single warning.
I fully assumed I had a firm handle on where my money went, but those missing funds hid inside small, repeatable transactions that never registered on my daily radar or caused any worry.
The mechanism is straightforward because digital payments remove the physical friction of handing over paper cash, making spending feel completely invisible until the balance drops. When you tap a plastic card instead of counting physical bills, your brain fails to register the actual cost in real time, turning minor daily habits into major financial leaks.
For my first month of tracking, I kept a physical notebook right in my bag and wrote down every single receipt immediately. It was tedious, slightly painful, and entirely eye-opening to watch how casual convenience quietly ate through my paycheck.
Your next action is to grab a plain notepad today and commit to writing down every single purchase you make this week without any self-judgment.
The Hidden Leak Totals
Average monthly discrepancy found during the first 30 days of manual tracking
2. Starting With a Tiny Floor
You have to overhaul your entire lifestyle to make saving worth doing.
That belief keeps the spreadsheet closed and the app unopened for months on end. The truth is much smaller and less exhausting. Setting up an automatic transfer of just twenty-five dollars a month into a separate account completely beats the zero dollars you keep meaning to move on payday. Consistency outlasts grand intentions every single time because it takes willpower entirely out of the equation.
Log into your banking app right now and schedule that tiny transfer before you overthink it.
💡 PRO TIP
Automate Your Smallest Transfer
Set up a recurring transfer for the day after payday, even if it is just ten dollars. Building the habit matters more than the initial sum.
3. Knowing When to Get Professional Help
Book an appointment with a nonprofit credit counselor or a fee-only fiduciary when the math simply stops working on your own terms.
If your minimum monthly debt payments consume more than fifty percent of your take-home pay, no budgeting spreadsheet in the world will solve the underlying structural gap. I spent months shuffling balances before realizing that spending less on groceries could not fix an obligation that completely outgrew my income.
Search for a certified professional who does not earn commissions on products, and bring your actual statements to a single session before you burn through your last reserves of emergency cash.
4. Building the Core Emergency Fund
The quiet dread of an unexpected car repair or a sudden medical bill is usually what sits heavy on your chest, knowing that a single bad Tuesday can instantly derail a month of careful planning.
Without a buffer, every surprise turns straight into high-interest debt.
Aim for one month of bare expenses first, covering rent, groceries, utilities, and debt minimums, which for a lot of households sits right around $2,000 to $3,500. Get that initial floor secured before you worry about investing or aggressive debt payoffs, because this cash cushion is the only thing that stops old balances from creeping right back up.
I learned this the hard way after raiding my own savings multiple times, which only finally stopped when I moved the money to a completely different bank where I could not touch it on a whim for weekend groceries.
This week, open a separate high-yield savings account at a totally different institution and transfer your first $50 into it to make the fund officially real.
5. Reviewing Your Progress Regularly
Looking at your bank statement for the first time in six months feels a little like stepping onto a scale after the holidays, and that dread is exactly why most people just close the tab.
You are not doing this to punish yourself for buying takeout, and a stray $12 lunch is not what broke your finances.
Checking your numbers once a month keeps small spending drifts from turning into major budget disasters before you even notice they are happening.
The mechanism here is purely about feedback loops and behavioral awareness, because seeing the numbers in black and white removes the emotional fog of guessing where your paycheck went.
Set a recurring calendar reminder for the final Sunday of every month to look over three specific metrics: total inflow, fixed bill changes, and discretionary spending variance.
Keep your review session brief, as twenty minutes is genuinely plenty of time if you look at the right categories instead of auditing every single transaction line by line.
Over time, these regular check-ins transform your relationship with spending from reactive anxiety to calm control.
This week: open your calendar app right now, drop a repeating reminder for the last Sunday of the month, and decide you will spend exactly twenty minutes looking at the big three numbers without any judgment.
6. Accepting the Real Cost of Convenience
Cutting convenience items saves money, but it also costs you extra time and effort.
Canceling meal delivery services means you will spend Sunday afternoons cooking batches of grain and chopping vegetables, saving roughly $150 to $200 a month while giving up your only quiet afternoon of the weekend.
Name that trade-off explicitly before you change your routine, because a budget requiring superhuman discipline will inevitably fail by week three.
This week, pick just one convenience habit to drop and trade ten minutes of planning for it.
7. Overcoming the Scarcity Mindset
Are you actually just bad with money, or are you just tired of carrying stress you never asked for?
That internal narrative is usually a learned response to past financial friction rather than a permanent personality flaw. When every week feels like damage control, your brain starts treating scarcity as your default baseline.
What I believe now is that systems replace panic. Set up one automatic transfer of $25 this Friday and let a structure do the heavy lifting your mood shouldn't have to carry alone.
⚠️ COMMON MISTAKE
The Perfection Trap
Do not abandon your budget just because you overspent in one category this week. Adjust the remaining days and move forward without self-punishment.
8. Fixing Subscription Creep and Auto-Renews
I sat at my kitchen table last year and found four different streaming apps I had not opened in six months, all quietly draining my checking account one small bite at a time.
Subscription businesses rely entirely on your daily inertia to stay profitable month after month without requiring any active thought or conscious choice from you.
The common trap is signing up for a free trial, forgetting to cancel before the billing cycle hits, and accumulating an invisible stack of monthly charges for cloud storage, music apps, and forgotten hobby kits we rarely touch.
You are not irresponsible for letting this happen, but ignoring it keeps you stuck.
Open your bank statement right now and highlight every recurring monthly charge under $50. Cancel at least two of them today, and set a calendar alert for thirty days from now to review the rest of the list. The whole cleanup takes ten minutes and instantly frees up your cash flow.
Subscription Audit Transformation
9. Capitalizing on Compounding and Timelines
You might be sitting there calculating how far behind you are, wondering if starting now even matters when you are already years into your career or family life.
It matters entirely.
Compound interest is simply earnings generating their own earnings over time, which means starting today does heavy lifting that a larger deposit next year cannot quite match.
If you put in $200 a month and it earned an average of 7% a year, which no one can promise since some years drop entirely, you would have somewhere around $17,000 after five years and closer to $40,000 after ten.
The exact math matters less than the shape of it, and waiting for the perfect income level to begin only burns the one resource you cannot buy back.
This week: set up one automatic transfer of $25 and let the timeline start working for you.
10. Giving Yourself Permission to Scale Back
Drop the strict rules the moment your life hits a major disruption.
We treat a personal budget like an unbending contract, but a rigid plan breaks the second a real crisis or a chaotic life transition hits your household.
When a medical emergency, a cross-country move, or an unexpected caregiving demand takes over your calendar, trying to maintain every single tracking category guarantees total burnout.
The mechanism here is simple psychological bandwidth preservation: your brain only has so much capacity during a crisis, and fighting a complex financial tracking system drains the energy you need for survival.
Instead of quitting the entire system out of sheer exhaustion, strip your routine down to a single baseline habit for the next 30 to 60 days.
Drop your tracking down to monitoring just your checking account balance twice a week and paying your fixed baseline bills on time, letting all the optional categories go completely.
I spent six straight months caring for an ailing family member while working full-time, and trying to categorize every $4 grocery trip nearly caused me to throw my whole financial ledger in the trash.
Consistency is not about maintaining flawless perfection during a disaster, but rather about staying loosely tethered to your money so you do not have to start from absolute zero when things finally settle down.
This week: write down the exact two essentials you will keep tracking during your hardest months, and explicitly give yourself permission to drop the rest.
The Resilient Budget Flow
11. Automating Payday Transfers Instantly
I spent three years manually moving $50 into savings every single Friday, and I missed at least half of them because life got loud.
Relying on willpower is a losing game when you are tired. Set up an automatic transfer that pushes $50 or $100 into your separate account the exact morning your paycheck lands, removing choice from the process entirely. When the money vanishes before you even see it, your daily spending naturally adjusts around what is left without requiring extra mental effort. Open your banking app right now and schedule that recurring transfer for your next payday.
12. Structuring Your Cash Flow Into Three Buckets
How do you stop watching your entire paycheck vanish into a single blurry pool of money before the middle of the month even arrives?
The secret is abandoning the single account model entirely.
Managing money becomes much easier when you stop treating your checking account as one giant pool of available cash.
Divide your income into three distinct buckets: fixed bills, debt minimums, and flexible spending, so every single dollar has a clear job description the second it hits your bank.
Hold your fixed bill money in a separate account so rent and utility payments are completely isolated from your weekend grocery money, keeping your essential survival funds safe from impulse buys.
If you fall short during a tight month, fund buckets one and two fully while letting the flexible spending take the hit, because missing a mortgage payment costs infinitely more than eating rice and beans for a few days.
This simple structure prevents you from accidentally spending your electric bill money on casual dining, removing the mental math required to figure out if you can afford basic life necessities.
Set up this three-bucket split on your next payday and watch your month-end anxiety drop significantly as the system quietly does the heavy lifting for you.
13. Reviewing Your Spending Triggers
It is almost never about the item waiting in the cart, and almost always about a heavy Tuesday afternoon or a deep wave of boredom.
Stress and emotional exhaustion lower our cognitive defenses, turning a mindless phone scroll into a $45 impulse order before we even register the checkout screen. Once a month, take ten minutes to review your recent non-essential purchases and look for the emotional thread connecting them.
This week, delete your saved card details from your phone and enforce a strict 24-hour waiting rule on any non-urgent item over $20.
14. Avoiding Common Grocery Store Traps
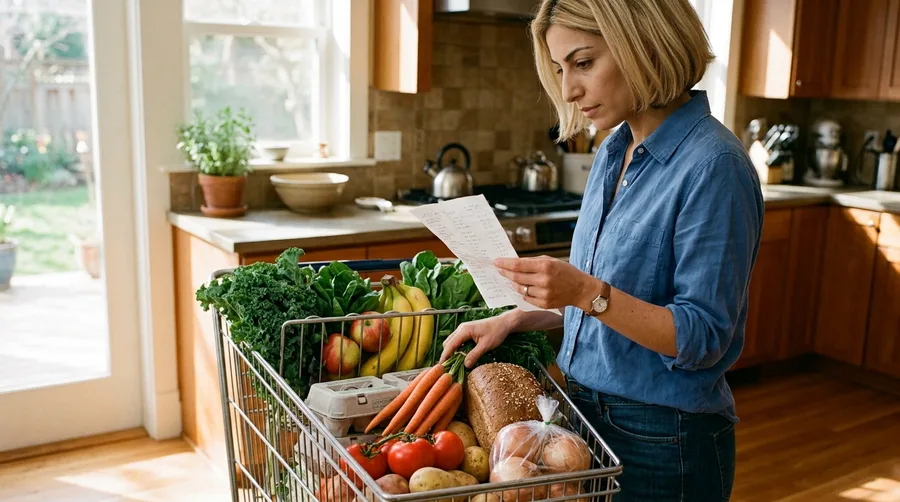
Fifty dollars slips out of the grocery budget almost every week without a single luxury item making it into the cart.
Walking into the supermarket hungry turns every colorful display into an emergency purchase, leading straight to pre-packaged items that quietly inflate the total at the register.
The trap is not a lack of discipline, but a setup designed to separate tired shoppers from their cash through clever end-cap placement.
Eating a small snack before leaving the house changes the physical urge to buy convenience foods we do not actually need.
Stick strictly to a written list and keep your cart moving along the perimeter where real ingredients live to keep weekly spending right on target.
15. Starting Your First Tiny Audit
You do not need an elaborate software setup to begin understanding your spending habits.
Most people avoid looking at their accounts because they expect a disaster, but a tiny audit starts with just thirty days of past transactions in a simple paper notebook or a blank spreadsheet.
The mechanism here is purely behavioral, because seeing the actual numbers bypasses the anxiety and lets your brain process where the cash really went without the emotional weight of self-blame.
Look for three small leaks rather than trying to fix your entire financial life by Monday morning, and set up one automatic transfer of $25 a month into a separate savings bucket to build the habit.
Give yourself grace as you figure out what works for your specific paycheck, knowing that starting small is infinitely better than waiting for a perfect moment that never arrives.
Frequently Asked Questions
Is it too late to start organizing my finances at 40?
It is never too late to gain control of your money. Starting at 40 still gives you decades of earning and compounding potential, especially if you focus on automating your savings and cutting hidden subscription leaks right away.
How much should I keep in my emergency fund?
Aim for one month of bare living expenses first to cover immediate surprises, then gradually build toward three to six months. The exact target depends on your job stability and monthly fixed obligations.
Should I pay off debt or save money first?
Build a small starter buffer of $500 to $1,000 first so minor emergencies do not add more debt. Once that safety net exists, direct your extra cash toward high-interest balances while maintaining your minimum payments.
Is it okay to pause my savings contributions during a tight month?
Yes, absolutely. Life fluctuates, and forcing yourself to save when your income drops leads to burnout. Pause non-essential transfers temporarily, cover your basic needs, and restart your deposits when things stabilize.
Your First Step This Week
You do not need to overhaul your entire financial life by Friday afternoon to see results.
Pick one small move from this list—cancel a forgotten subscription or open a separate savings account—and do it today. Your future self will thank you for the extra breathing room.
