The $612 car insurance bill clears on a Thursday, and the balance you were counting on for groceries is $180 lighter by Friday morning.
You have a steady paycheck. You also have no idea where the last one went, and there is a budgeting app on your phone you stopped opening some time in February. You do not want another system. You want one small thing you will actually keep doing.
So the routine here is not an app and not a plan. It is five checks in a fixed order at the kitchen table, Sunday at 7pm, with a phone timer set to ten minutes and a printed checklist in front of you.
What that buys you is narrow and real: you see the free cash number, you catch a bill before it lands, you move spare cash to savings, and you leave with exactly one task for the week. It will not reorganize your whole financial life, and it does not pretend to.
Tonight you can run the long version once, gathering balances and due dates and setting the Sunday timer. Then you will know where you stand and what the ten minutes will and will not fix.
| Step | Minutes | What you do | What it catches |
|---|---|---|---|
| 1 | 2 | Open the banking app and read the checking balance | A balance that dropped faster than the week |
| 2 | 3 | Scan last week's transactions line by line | Charges you do not recognize, duplicates, price creep |
| 3 | 2 | List every bill due before the next payday | A big annual bill landing in one paycheck |
| 4 | 2 | Move cash above the $500 buffer into savings | Idle money that gets spent instead |
| 5 | 1 | Pick one money task for the week | Everything else that would otherwise stretch the review |
What the Ten Minutes Actually Consist Of
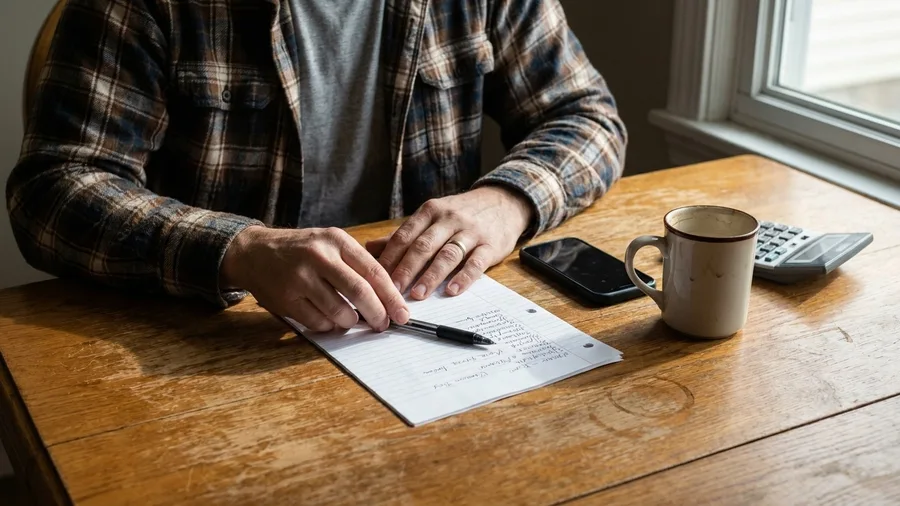
You sit down at the kitchen table on a Sunday at 7pm with three things: your banking app open, a printed checklist of five items, and a phone timer set to ten. Nothing else gets a place at the table – no spreadsheet, no second screen, no app you downloaded and forgot.
The five checks run in the same order every week, and the clock splits roughly like this. Two minutes on the balances in front of you. Three minutes scrolling last week's transactions, not to judge them but so the $60 is a choice instead of a surprise. Then two minutes on what comes out before the next payday lands.
The last four minutes are where the review earns its keep. Two of them move whatever sits above a $500 checking buffer across to savings – that cushion is yours to name and then leave alone. The final minute picks one money task to carry into the week, and only one.
Take a household bringing home $4,200 a month, with $2,600 already spoken for by rent, utilities, insurance and minimum debt payments. That leaves $1,600 for groceries, gas and everything else, and all five checks work off that split rather than off zero-based budgeting you would have to build first.
The boundary rule is the part that keeps this at ten minutes instead of swelling to an hour: anything not on the checklist either becomes the one-minute task or waits until next Sunday. Write the stray thought on the back of the sheet and move on.
Jot down what you noticed, close the app, and let the timer decide when you stop – not the size of the pile.
Why Weekly Beats a Monthly Deep Clean
Seven days is the interval because a paycheck can be broken by a single badly timed bill, and a month is long enough for that bill to land first. Picture the $612 car insurance premium that comes due every six months. Seen on a Sunday, two weeks before it hits, you have room to shift the due date or park the cash. Seen at a monthly review, the damage is already sitting in your balance and the next check is the one that absorbs it.
That is what the weekly pass is built to catch – timing – and it is why the ten minutes are worth repeating so often. A monthly deep clean does the opposite job. It is where patterns show up, and it is the only place they do.
Two subscriptions at $31 a month combined, still billing quietly, are close to invisible inside a single week's spending. Whether savings are actually climbing from $3,100 toward the $7,800 emergency-fund target is a question no Sunday answers either, because one week's sweep of $80 tells you nothing on its own.
So the honest split looks like this. If your paycheck tends to run out before the month does, the weekly review is the one to keep. Lay a longer sitting on top of it once a year, when you set the savings number and recheck where you are against it.
The deep clean does not go away because you started reviewing on Sundays. It holds the two things ten minutes will never see: creep you have stopped noticing, and slow progress toward a number that sits months out.
Weekly review vs. monthly deep clean
Weekly 10 minutes
- Run it Sunday 7pm, timer on, five checks in order
- Time split: 2 min balances, 3 min transactions, 2 min bills, 2 min sweep, 1 min task
- Sweep rule: keep $500 in checking, move anything above it
- Ten minutes a week is about 8.7 hours a year
Monthly (or annual) deep clean
- One longer sitting a year, not a monthly habit
- Ask one question: is savings climbing from $3,100 toward $7,800?
- Reset the savings number, then leave it alone
- Skip it if each week is already a scramble – do the Sunday first
The One Number to Read First
The number that decides your week is free cash, and it is three figures and one subtraction: checking balance minus bills due before the next paydate minus the $500 buffer. Say checking holds $1,320 and $740 of bills land before you are paid again. Take off the $500 that stays put, and free cash is $80.
The raw balance flatters you. $1,320 looks like money you could spend, but $740 of it is already spoken for and $500 of it is the cushion that keeps a timing error from turning into an overdraft. The gap between what the app shows and what you can actually use is the whole reason the weekly pass exists.
When free cash is positive, you sweep everything above the $500 buffer into savings. In this example that is $80, and the typical weekly sweep runs $60 to $150. Against the $3,100 already saved and a $7,800 target, that is steady progress you can see without tracking a single grocery receipt.
When free cash is negative, you do not raid the buffer to pretend the week is fine. The one task becomes moving a due date or cutting that week's variable spending, which is a decision made on a Sunday with days still ahead of you.
Balances, transactions and bills all feed this figure, but the action comes from the result. Read free cash first, and the rest of the ten minutes has a point.
⚠️ COMMON MISTAKE
Do not treat the balance as spendable
The most common slip is reading the checking balance as money you have. Subtract the bills due before payday and the $500 buffer first, then decide. A balance of $1,320 can mean $80.
What Ten Minutes Cannot Fix
A routine that moves cash and times bills cannot raise your income, build your credit, or invest a single dollar, so it will not put you ahead of 90% of anyone. The review sweeps spare cash to savings and it catches timing. Those three jobs are the whole job list.
That is worth saying plainly, because the headline number is framing, not a measurement. No study is cited for it, and nothing here claims a measured share of people who do this and a share who don't. What the routine actually buys is smaller and firmer: your free cash is $80 this week instead of a guess, and the $612 car insurance bill shows up on a Sunday while you can still move the due date.
Some problems sit entirely outside the ten minutes. For what you're paid, what's withheld, and what your benefits cover, the answers live in your employer's plan documents and in the IRS withholding estimator, which you can run online with a recent pay stub in hand. For a debt balance that has not moved in months, a nonprofit credit counselor will look at the whole picture. The review can flag both needs and write them into the one task slot. It cannot do the work itself, and it shouldn't be asked to.
The emergency fund is the clearest example of the line. Savings hold $3,100 against a $7,800 target, three months of committed costs in the $4,200 example, and the weekly sweep of $60 to $150 is what closes that gap over time. The review moves the money. It is not the fund. If a $1,400 car repair lands this week, ten minutes at the kitchen table changes nothing about that. The $500 buffer is not raided to make the week look fine, and neither is the emergency fund, because it isn't one yet.
How It Survives Past Week Three
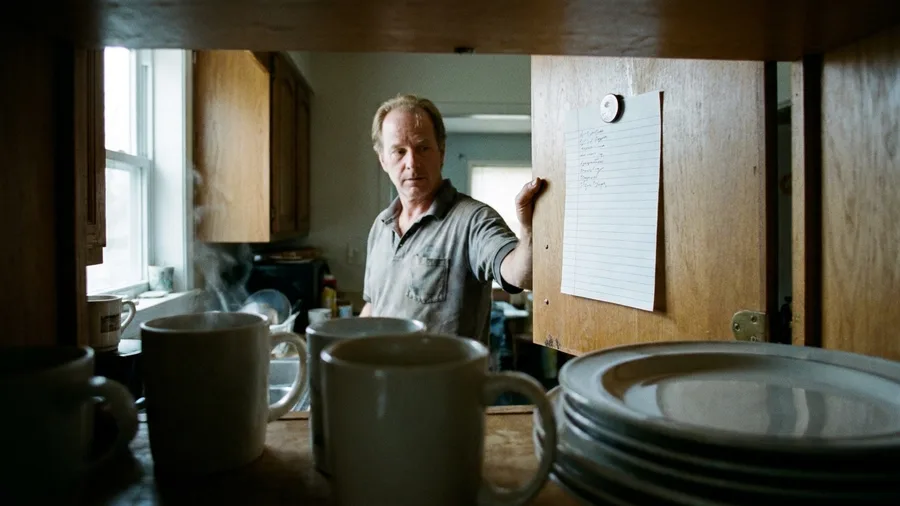
A time and a place hold a habit better than motivation does, which is why this one follows the Sunday ritual at the kitchen table at 7pm with a timer running on the phone. Motivation quits around week three. A slot on the calendar doesn't need to feel like it.
The timer is the strictest part of the deal. When it goes off, the session is over, finished or not. Anything unresolved does not get another five minutes; it becomes the week's one task, the same one-minute slot the five checks already produce. That single rule is what keeps a ten-minute review from quietly turning into an hour, which is how most money systems die.
Expect to miss a Sunday. A birthday, a late shift, a week that just gets away from you, and the streak is broken. The rule that saves the habit is never miss twice: a missed Sunday gets a two-minute Monday catch-up that checks free cash and nothing else, and the next Sunday returns to the full five checks. One missed week is a gap. Two in a row is how the whole thing ends.
Tape the checklist inside a cabinet door, the one you open for coffee or plates, so the list stays visible without you having to remember it exists. It is the same five items every week, in the same order: balances, transactions, bills due before payday, the sweep above the $500 buffer, one task. The list does the remembering. You just show up.
📆 The first four Sundays — what the timer forces
Session one runs long, on purpose
Expect 30 to 40 minutes here — not a failure of the habit, just the setup cost. Write every recurring bill's amount AND due date next to it, including the annual and six-month ones like the $612 car insurance that lands in one paycheck.
Your one deciding number
Checking minus bills due before the next payday minus $500. That figure is the whole decision rule: positive means sweep the difference, negative means the sweep waits and the shortfall becomes this week's task.
Week two: what a normal sweep looks like
In the $4,200 example, $60 to $150 typically moves. If several sweeps land in a row, the emergency fund is heading for $7,800 — from $3,100 that is 31 to 78 weeks of Sundays, not months.
Week three: the timer goes off mid-check
It will, at least once. Whatever is unfinished does not get the next check's minutes — it goes in the one-task slot and waits seven days. That is the rule working, not the review failing.
The missed Sunday, handled
Monday catch-up is two minutes and one question only: is there free cash above $500? No transactions, no bills, no new task. Then the next Sunday is full five checks, no catching up on what was missed.
When to stop trusting the slot alone
If three sweeps in a row come back negative, the review is fine and the committed costs are the problem — $2,600 of $4,200 leaves $1,600 for everything else. That is a budget conversation, not a habit one.
Your First Session Takes Longer
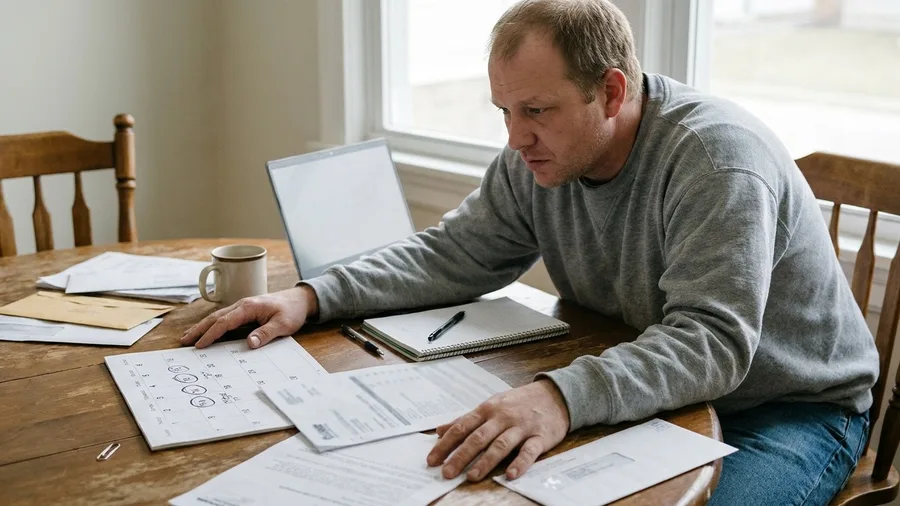
The one exception to the cap is the sitting you do first: budget thirty to forty minutes, not ten, and then never give it more than ten again. It runs long because you are building the kit every later session will assume – logins you have to hunt for, a bill list that does not exist yet, two payday dates you have to look up rather than remember.
That is the whole cost. One longer evening buys the dial tone.
Spread across the table for that first session: every account with today's balance in it, every recurring bill with the day it comes out, and the next two payday dates. Not the amounts you assume – the ones on the statements. If a login is lost, reset it now and write the new one somewhere you will find it at 7pm on a Sunday, because hunting for it again is what turns ten minutes into thirty.
While you are already sitting there, put the Sunday 7pm timer in the phone and tape the printed five-item list inside a cabinet door. The list is the same five items every week – it is the fixture, not the work.
Finish by writing down two things on that sheet. The free-cash number: checking minus the bills due before your next payday minus the $500 that stays put. In the example household that means $1,320 minus $740 minus $500, which leaves $80 free, or $80 that is actually yours to move. Then the one task for the week, and only one, because a second task is how a ten-minute habit starts asking for twenty.
The longer first session is what makes the other fifty-one short ones possible, and it happens exactly once.
Frequently Asked Questions
Is a ten-minute weekly money review really enough?
It is enough for the job it is built for: catching bill timing and small leaks before they turn into debt. It will not raise your income, build credit or invest anything. Run it weekly and keep one longer sitting a year for the bigger picture.
What if my income is irregular or I get paid weekly?
Swap the "bills due before the next payday" check for a rolling fourteen-day window and keep everything else the same. The free-cash formula still works; only the date range moves.
How big should my checking buffer be?
Start at $500. It covers most of the surprises that actually hit people and keeps you from overdrafting on a badly timed bill. Once it feels easy, raise it to one month of committed costs.
Should I sweep to savings or pay down debt first?
Keep the $500 buffer first, then run the arithmetic on your own debt: compare the interest rate you pay against the rate your savings account earns. When the two are close, the psychological win of a shrinking balance often matters more than the math. If the debt is large or the accounts are confusing, a session with a nonprofit credit counselor or a fee-only fiduciary will settle it.
What if I miss a Sunday?
Do a two-minute Monday catch-up that only checks free cash, then return to the full five checks the next Sunday. The rule is never miss twice, because two in a row is where the habit quietly ends.
Do I need an app or can this be paper?
One banking app plus a printed checklist is enough. The checklist taped inside a cabinet door does more for consistency than any subscription, because it does not depend on you remembering to open something.
Tonight's Job Is the List, Not the Timer
Tonight, before anything else, write two lists: every account with what is in it right now, and every bill with the date it comes out. Add your next two paydays, subtract the bills due before them and the $500 that stays in checking, and you have your free cash number. Then put a repeating Sunday 7pm timer in your phone and leave the table with one task for the week, written down.
The 90% in the title is framing, not a measured finding. Do this because it makes you the person who knows their numbers, and because a $612 bill seen two weeks early is a phone call instead of a credit card balance.
The paycheck that vanished and the app you abandoned do not meet a bigger system here. They meet a printed checklist, a timer, and about 8.7 hours a year. The person who knows their numbers can act before the month ends, not after it, and Sunday at 7pm is the smallest repeatable way to become that person. Set the timer now.