
Skip the new roof and it is $14,000 in one unlucky spring. Skip the tooth and it is $4,800 for the implant and crown. Skip the plan for a fall and it is $2,600 a month for private home care, arriving on a Tuesday with no warning.
Here is why nobody sees these coming. A retirement spreadsheet gets built around groceries, travel, and the mortgage that finally disappeared, because for forty years payroll quietly swallowed the small stuff. Dental came out before you ever saw the money, so nobody wrote down a line for it. Then a tooth breaks and the quote lands with no paycheck left to absorb it.
The bills that actually surprise people all arrive outside payroll: $2,600 for a pair of hearing aids, $2,600 a month for home care, that $14,000 roof on a 28-year-old house, and a tax reset when a single filer pulls $20,000 from a retirement account.
All seven can be named, priced, and sorted into two piles: budget now, or absorb later with cash. That sorting is the whole point of this piece. A house fund and a health fund cover the first pile; cash you set aside covers the second, because no policy will. You do not have to fund all seven this month. Start with the two that match your roof and your health, and let the fall open-enrollment check on Medicare.gov handle the rest.
Quick Tips Before You Start
Price the gap, not the plan
Before you book anything, pull the plan's Evidence of Coverage on Medicare.gov and read the dental, hearing and vision sections line by line.
Give the house fund a name
Keep it in a separate account from the emergency fund so a roof quote never competes with a car repair.
Recheck Part B and your supplement every fall on Medicare.gov instead of letting it auto-renew.
Reset withholding after the first year
When a household goes from two filers to one, the same income is taxed under different rules — check the withholding estimator on IRS.gov.
Write down the family help
Which days, which jobs, what gets reimbursed. A standing commitment nobody renegotiates is the one that quietly costs the most.
Health bills that never touch the budget
Payroll quietly handled a lot of health costs for thirty years. Dental came out of the paycheck, vision came out of the paycheck, and the premium was a deduction you never saw hit the account.
Then the paychecks stop and the deductions stop with them — but the needs don't. This first group is the one that arrives directly from coverage gaps, which makes it the easiest to overlook and the easiest to plan for once you know the number.
1. Dental, hearing and vision are yours to pay
Because dental stopped being a payroll deduction the day you stopped getting a paycheck. The coverage you had at work does not follow you into Medicare, and most people find that out at the front desk with a treatment plan in their hand.
Dental, hearing and vision are the three gaps most likely to hit in the same year, and they hit as cash. In the example household the surprise was a broken tooth: $4,800 for one implant and crown, and $2,600 for a pair of hearing aids. Two procedures, one season, more than $7,000 that the old spreadsheet never had a column for.
The reframe is small and it changes everything: this is not a medical bill, it is a health-fund line. Working-years dental came out of your check before you ever saw it. Now it comes out of savings, so it has to be planned for the way the check used to be.
Before anything gets booked, pull the plan's Evidence of Coverage on Medicare.gov and read what it actually pays for dental, hearing and vision. Then price the $180-a-year dental savings plan against paying the same work in cash. That sentence on the brochure is not the same document as the coverage rules.
And waiting has its own price. A broken tooth left alone becomes an extraction and a denture instead of a crown, and the bill climbs past the $4,800 quote. If there is no health fund yet, the $4,800 and the $2,600 are absorb-later cash, pulled from savings the month they land.
💡 Tip: Get the treatment plan in writing with procedure codes before you agree to anything. It is the only way to price two offices against each other.
| Cost | When it shows up | Amount in this example | Budget now or absorb later? |
|---|---|---|---|
| Dental implant and crown, plus hearing aids | When coverage gaps surface after Medicare starts | $4,800 + $2,600 | Budget a health-fund line; absorb later if there's no fund |
| Part B plus supplement premium | Every month, re-priced annually | $610 a month | Budget now — it's a fixed monthly figure |
| Private home aide after a fall | Weeks after a hospital stay | $30/hour, 20 hrs/week, about $2,600 a month | Absorb later — no paycheck-era line covers it |
| Roof and water heater | First decade of retirement | $14,000 + $1,600 | Budget now via a house fund |
| Walk-in shower, grab bars, entry ramp | Before the fall, ideally | $3,200 + $1,900 | Budget now via a house fund |
| Tax shift from joint to single filing | The first year filing alone | $20,000 withdrawal taxed differently | Budget now — withholding can be reset |
| Family help for appointments and errands | As help becomes a standing commitment | $400 a month plus about 10 hours a week | Budget now if reimbursed; absorb later if not |
2. Premiums don't stop climbing when work does
The common belief is that once you are on Medicare, the coverage is settled and the monthly charge is a fixed fact of life. Here is the truth: that charge is re-priced every single year, whether or not you use a dollar of care.
In the example household, a couple both 67, the health coverage runs $610 a month, Part B plus a supplement on top of it. They paid that figure for a few months and treated it as a number that had already been decided. Then the fall notice landed in the mailbox with a new premium, and the assumption fell apart.
This is where the arithmetic gets uncomfortable. The $610 comes out of a combined Social Security check of $2,900 a month. The Social Security figure moves on its own schedule, set by the annual cost-of-living adjustment; the premium moves on a different schedule, reviewed and repriced each year on Medicare.gov. The two clocks rarely match, so even in a year when nothing else in the budget changes, the gap between what comes in and what the policy takes can widen. Reading up on which states tax retirement income helps you see how much of that money actually survives the tax bill. No new expense had to appear. The premium alone did it.
That is why the plan gets rechecked every fall rather than auto-renewed. A household with predictable, low-use care may find a lower-premium option that works fine for what they actually need; a household with high-use care may find the supplement they already carry is worth the cost, and the recheck confirms it. Either way the number gets looked at instead of assumed.
So the automate-it move is simple. Set a repeating calendar reminder for early fall, go to Medicare.gov, and read what the plan actually covers and what it now costs. Set it once and leave it alone the rest of the year, so the decision does not rest on whether anyone remembers in October.
The monthly premium is the one line on this list that can be budgeted now, as a fixed figure going out every month. Any increase is a different animal: it has to be absorbed out of the Social Security check when it arrives. Budget the base, absorb the bump.
If the reader does only one thing this week, it is to put the reminder into a phone or a paper calendar, set to repeat every year, so the repricing never goes unchecked. It costs nothing and it takes a minute.
⚠️ COMMON MISTAKE
Never let the plan auto-renew unread
Most households re-price their premium whether or not anyone looked at the coverage. Spend twenty minutes in October on Medicare.gov comparing what you used against what the plan pays for, and you stop paying for care you will never touch.
3. One fall becomes hourly home care
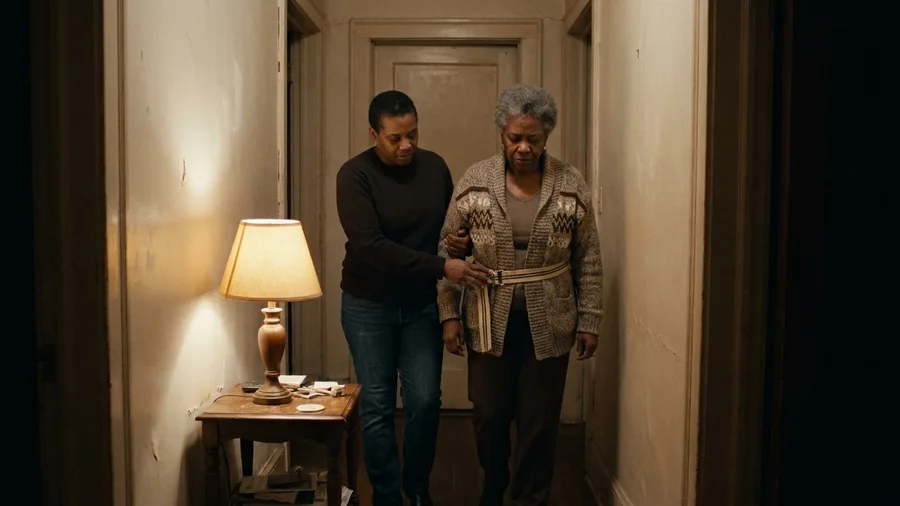
Price the first six weeks of help before anyone needs it, because Medicare pays for the hospital stay and not for the aide who comes after. For the categories that rise rather than fall, see expenses that go up in retirement and build them into the same plan.
A single fall can turn into $30 an hour, 20 hours a week, about $2,600 a month for six weeks, paid privately. That money goes to the home aide, never to the hospital bed, which is why a good supplement can still leave a household writing checks the month after discharge.
The move is to ask the discharge planner for the agency's hourly rate in writing before any agreement is signed, so the $30 figure is confirmed on paper before care starts. A household with a local adult child who can cover the first fortnight does not face the full six-week bill. Everyone else should plan on the $2,600 a month as absorb-later cash, never insurance.
Where the health fund stands
Figures reflect the example household in this article, not a national average.
The house you're staying in
The house does not retire when you do. It keeps aging on its own schedule, and it sends bills for the privilege.
This group is the one people underestimate most, because the working-years budget treated repairs as occasional noise rather than a predictable cost with a known timeline.
4. The house keeps sending you bills
Nothing about the roof is an emergency today. That is the trap. It will not stay a quote forever, and no one is going to send a reminder before it becomes a bill.
The house keeps failing on its own schedule, the way the body does. In this example the roof is 28 years old and quoted at $14,000, and the water heater is $1,600, and those are the two most likely to land in the first decade of retirement. Defer the cheap one and it grows: a $1,600 water heater left to leak becomes a $6,000 floor-and-ceiling job. That is the absorb-later penalty, paid in cash you may not have set aside.
So give the house its own bucket, kept apart from the emergency fund so neither one quietly drains the other. Size it to the two biggest items you can already name, the roof and the water heater, and add to it monthly. If the roof is five years out and you set aside $230 a month, you are most of the way to $14,000 by the time the shingles go, and the $1,600 heater sits inside the same fund without touching your grocery money.
Both of those are budget-now items. The repair you put off is the one you can only absorb later.
If you rent, this line is not yours. Yours is the annual rent increase, and it arrives with a letter instead of a roofer.
💡 Tip: Get three quotes on the roof and ask each one what the warranty covers. A $14,000 job with a five-year workmanship guarantee is cheaper than a $12,500 job with none.
5. Aging in place has a remodel price tag
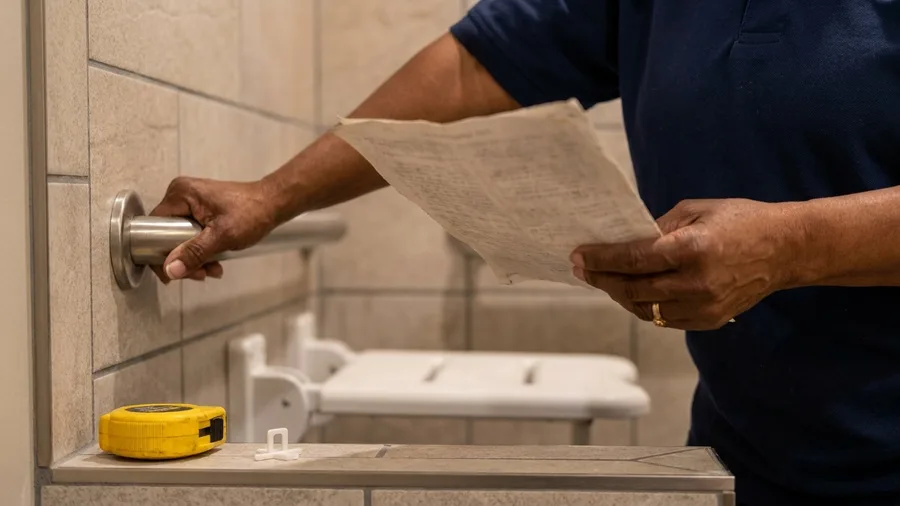
$3,200 for a walk-in shower and grab bars. $1,900 for an entry ramp. That is what staying in your own house costs once the stairs start to argue with you.
Grab bars and better lighting come first, before the bathroom remodel, because the fall is cheaper to prevent than to treat. Skip them and you meet the $2,600 a month home aide on the other side of a broken hip. The $3,200 and $1,900 go in the house fund as budget-now jobs, and the return is the care you never have to buy.
Now the part that needs your own numbers. If the only bedroom is upstairs and the full bathroom remodel lands in the same year, sit down with a fee-only fiduciary or a local aging-in-place specialist and price moving against remodeling before you sign a contractor's estimate. That comparison depends on your house, your town, and your health, and no article can make it for you.
Fixing up vs. moving out: the costs that are not on the contractor's quote
Stay and remodel
- Budget-now jobs: shower $3,200, ramp $1,900
- Age the house too: roof $14,000, water heater $1,600
- Remodel cost stays tied to your house, not rent
- Absorb-later risk: an aide at $30/hr if a fall happens
Move instead
- Roof and water heater stop being your problem
- $14,000 and $1,600 leave the list; rent replaces them
- One predictable check, but it rises with the market
- Due diligence: price movers and waiting lists first
The paperwork nobody re-reads
Two costs in this article are decided by forms rather than by prices. Neither one appears anywhere on a working-years spreadsheet.
The first is the tax shift that comes with filing alone. The second is the quiet assumption that family help is free. Both change the household's real income, and both get ignored until something goes wrong.
6. The tax bill shifts when you file alone
Sit down this month and reset your withholding. Do it before the next withdrawal clears, not after the bill shows up. The year a household goes from two filers to one, the same income gets taxed under different rules, and the rules do not care that nothing else about your life changed.
In this example a $20,000 withdrawal last spring was the first taste of it, and the preparer reset withholding only after the first year of filing single. Check the current rules and the withholding estimator on IRS.gov rather than a figure you remember from your working years. Withholding is the budget-now piece, because it can be fixed. The beneficiary forms are the absorb-later surprise: pull them out in the same sitting, because they decide what the household keeps.
The spouse who has never seen the return is the one caught out.
💡 Tip: Check the current rules and limits on IRS.gov each year — not a figure you remember from the working years.
7. Your kids' free help isn't free
There is a quiet guilt in accepting help you never agreed to pay for, and a quieter worry that everyone has stopped counting. In this household the daughter runs the appointments, and the running tab is $400 a month in groceries and gas plus roughly 10 hours a week behind the wheel. That is a bill with no invoice attached, which is exactly why nobody ever reviews it.
What starts as a favor for a few weeks hardens into a standing commitment, and no one sits down to ask whether it still fits. The smallest move available is to write the arrangement down: which days she drives, which errands she covers, and what gets reimbursed at the end of each month. Ten minutes and one sheet of paper puts the $400 and the hours into a budget line instead of a family assumption, so the help can be seen and kept honest.
Reimbursing even $50 of that $400 this month is a real start. A household without a daughter nearby does not get this discount at all, so the same gap runs at the $30-an-hour aide rate and has to come from cash set aside later.
🗂️ The order to do this in
Price the gaps
Read the plan's Evidence of Coverage on Medicare.gov and write down what dental, hearing and vision cost you.
Open two accounts
One health fund and one house fund, separate from the emergency fund, so neither bill raids the other.
Transfer the monthly premium plus a $50 buffer into the health fund on payday.
Book the fall review
Put October on the calendar to recheck the plan on Medicare.gov instead of auto-renewing.
Reset the withholding
Run the IRS.gov withholding estimator for the year you first file alone.
Write the family arrangement
Days, jobs and reimbursements on one page, so the $400 and 10 hours become a budget line.
Frequently Asked Questions
Why did the dentist bill land on me?
Working-years dental coverage does not carry into Medicare, so the whole $4,800 for an implant and crown can arrive as a single bill. Read the plan's Evidence of Coverage on Medicare.gov before you book, and price a dental savings plan against paying cash for the specific procedures you need.
Part B and supplement premiums are re-priced annually, whether or not your care changes. That increase lands against a Social Security check that moves on its own schedule, which is why a fall review on Medicare.gov matters more than the auto-renew default.
What happens if one of us can't manage alone?
A hospital stay can turn into weeks of privately paid help — in this example $30 an hour, 20 hours a week, about $2,600 a month for six weeks. Ask the discharge planner for the hourly rate in writing before signing an agency agreement, and check whether family can cover the first fortnight.
How much should sit in a house fund?
Size it to the two biggest items your house is likely to hand you. Here that is a $14,000 roof and a $1,600 water heater, so the target is $15,600, kept separate from the emergency fund and topped back up the month after you spend from it.
Should I pay for the remodel or move?
Compare the two on one page. If you are facing a second-floor bedroom and a full bathroom remodel in the same year, moving is worth pricing seriously. If the jobs are a $3,200 walk-in shower, grab bars and a $1,900 ramp, the remodel is cheaper than one year of hourly care.
Is it okay if I can only fund one of these right now?
Yes — pick the house fund or the health fund, whichever bill is closer, and start at any amount. A small automatic transfer beats a large one you keep meaning to set up, and the other lines can wait a paycheck or three.
Fund two lines, absorb the rest with cash
Fund two lines and leave the rest as cash. The house fund gets sized to a $14,000 roof and a $1,600 water heater. The health fund takes the $4,800 implant, the $2,600 hearing aids, and the $180-a-year dental savings plan, so the coverage gaps stop arriving as surprises.
Two costs cannot be insured at all. A private home aide runs $30 an hour, about $2,600 a month for six weeks of help, and the family load of $400 in groceries and gas plus roughly 10 hours a week of driving has no policy behind it either. Cash set aside is the only defense. The tax piece is handled separately, by resetting withholding as a single filer this month.
So the first thing to do is the enrollment review. Go to Medicare.gov before fall open enrollment and write down exactly what your plan covers for dental, hearing, and vision, then put that dollar gap next to your health fund. That was the line missing from the paycheck-era spreadsheet. Seven bills can be named before they arrive, and naming them turns the warning into a number you can prepare for.
Get the two numbers written down
Open Medicare.gov, find your plan's dental, hearing and vision sections, and write the dollar gaps on one page. That page is your health fund target.
